

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
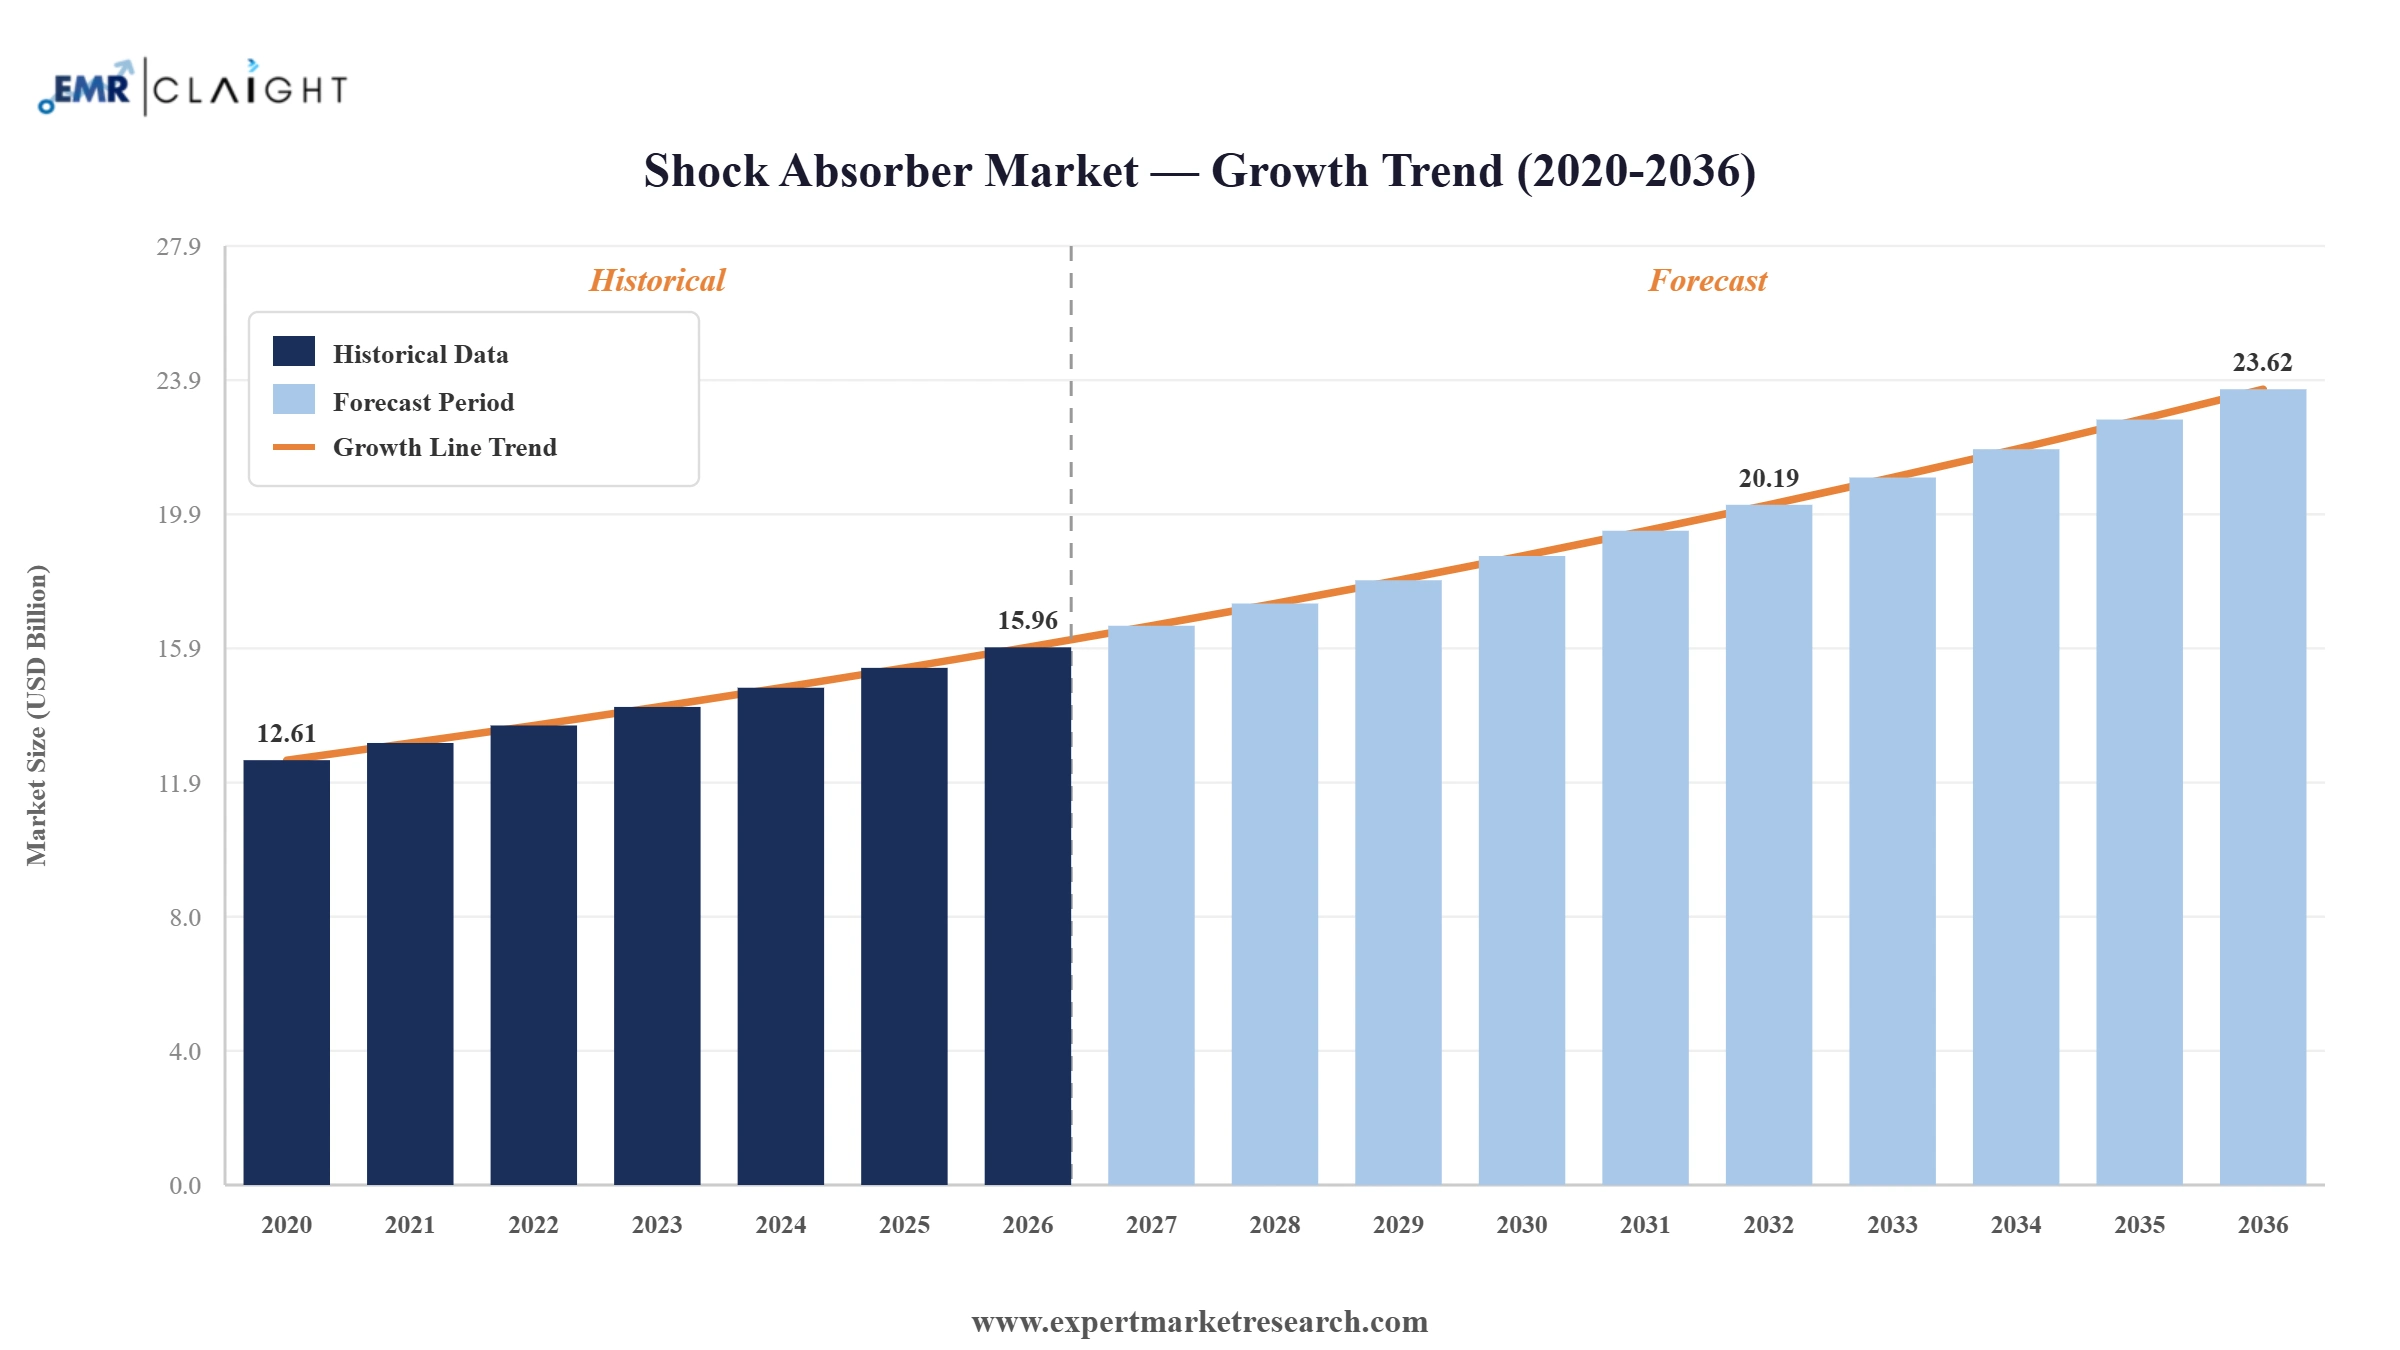
The global shock absorber market attained a value of USD 15.35 Billion in 2025 and is projected to expand at a CAGR of 4.00% through 2035. The market is further expected to reach USD 22.72 Billion by 2035. Rising vehicle production, growing consumer demand for ride comfort, and expanding electric vehicle adoption are helping suppliers differentiate their damping technologies across every vehicle category. Growing consolidation among suspension technology suppliers and rising investment in active and semi-active systems is further encouraging manufacturers to widen their product portfolios worldwide.
A shock absorber is a mechanical device engineered to absorb and dampen shock impulses, converting kinetic energy into heat to smooth out irregularities on the road surface. Hydraulic shock absorbers hold a substantial share of the market owing to their widespread use, proven reliability, and lower manufacturing costs across mass market vehicles. Rising vehicle production across emerging economies continues to widen the buyer base for shock absorbers worldwide.
Demand is concentrating around suppliers able to combine established engineering expertise with expanded manufacturing capacity. In January 2025, Sona Comstar invested 4 million dollars in ClearMotion to accelerate the commercial rollout of its proactive suspension technology, reflecting growing supplier interest in software driven damping systems. This capacity driven positioning is converting rising demand for reliable, high volume suspension components directly into expanded adoption across the global shock absorber market.
Suppliers across the shock absorber market are converging on a common development direction, widening from conventional passive damping toward intelligent, sensor integrated active suspension systems. Suppliers are increasingly pursuing strategic partnerships to combine damping expertise with complementary air spring and electronic control capabilities across their product portfolios. This shift is reshaping competitive dynamics among suppliers, favouring companies who can demonstrate integrated suspension system capability over those offering only standalone shock absorber components.
Read more about this report - Request a Free Sample
| Global Shock Absorber Market Report Summary | Description | Value |
| Base Year | USD Billion | 2025 |
| Historical Period | USD Billion | 2019-2025 |
| Forecast Period | USD Billion | 2026-2035 |
| Market Size 2025 | USD Billion | 15.35 |
| Market Size 2035 | USD Billion | 22.72 |
| CAGR 2019-2025 | Percentage | XX% |
| CAGR 2026-2035 | Percentage | 4.00% |
| CAGR 2026-2035 - Market by Region | Asia Pacific | 4.6% |
| CAGR 2026-2035 - Market by Country | India | 4.5% |
| CAGR 2026-2035 - Market by Country | Saudi Arabia | 4.4% |
| CAGR 2026-2035 - Market by Type | Gas Charged | 4.8% |
| CAGR 2026-2035 - Market by Technology | Active | 4.7% |
| Market Share by Country 2025 | Australia | 2.3% |
Miller Performance Parts, parent company of BMR Suspension, completed its acquisition of Heidts Automotive, which will now operate as Heidts Suspension. The two brands will continue operating independently while collaborating on new product lines for American muscle and late model vehicles. Suppliers across the shock absorber market can use targeted acquisitions to expand their aftermarket suspension portfolio while preserving each acquired brand's distinct customer base.
Fox Factory entered into a cooperation agreement with Engine Capital, appointing two new independent directors and forming a board level transformation committee. The initiative aims to enhance operational performance and profitability following recent acquisition related pressures. Suspension suppliers across the shock absorber market can use governance restructuring to signal renewed strategic discipline to shareholders and industry observers watching closely.
Gabriel India completed the acquisition of ride control assets from Marelli Motherson Auto Suspension, adding 3.2 million shock absorbers and 1 million gas spring units of annual manufacturing capacity. The deal includes a technical and licensing agreement further enhancing the company's technological capabilities. Suppliers across the shock absorber market can use strategic asset acquisitions to expand manufacturing capacity and broaden their customer base rapidly across regions.
Brembo completed its acquisition of a 100 percent stake in Öhlins Racing, a leading manufacturer of premium suspension technology for motorcycles and cars, in a deal valued at 405 million dollars. The transaction marked the largest acquisition in Brembo's history. Suppliers can use landmark acquisitions to enter adjacent high-performance suspension segments and broaden their aftermarket presence globally.
Chassis system suppliers are increasingly unveiling software defined suspension concepts at major trade events, integrating damping systems with by-wire steering and braking technologies worldwide. This is reshaping product roadmaps across the global shock absorber market, favouring suppliers who can demonstrate integrated, software driven chassis platforms. In September 2025, ZF presented its Chassis 2.0 concept at IAA Mobility, combining active and semi-active damping with electronic roll stabilisation and rear axle steering into one integrated platform.
Component manufacturers are increasingly acquiring specialised vibration control technology firms to strengthen their North American manufacturing presence and broaden their suspension portfolios. This is reshaping competitive positioning across the global shock absorber market, favouring manufacturers who combine established scale with targeted specialist acquisitions. In March 2025, Continental completed its acquisition of Vibration Control Technology, a US based company specialising in suspension and vibration control components for passenger and commercial vehicles across North America.
Regulators are increasingly approving new type approval rules that explicitly cover adaptive suspension systems alongside broader driver assistance technologies nationwide. This is reshaping compliance priorities across the global shock absorber market, favouring suppliers who can demonstrate regulatory alignment for advanced damping systems. In May 2025, the European Union approved a new type of approval regulation for advanced driver assistance systems, including adaptive suspension, aimed at improving road safety across the European Union.
Suspension suppliers are increasingly showcasing dedicated two-wheeler damping and rider assistance technology at motorcycle focused trade events, separate from broader passenger vehicle suspension displays worldwide. This is reshaping product visibility across the global shock absorber market, favouring suppliers who can demonstrate purpose-built two-wheeler engineering. In October 2025, Hitachi Astemo showcased next generation motorcycle suspension systems alongside rider assistance technologies, highlighting improvements to safety, comfort, and riding stability across varied road conditions.
Aftermarket suspension suppliers are increasingly using major trade events to showcase expanded product coverage for commercial trucks, trailers, and buses nationwide. This is reshaping product visibility across the global market, favouring suppliers who can demonstrate broad OE reference coverage at scale. In January 2026, PRT Heavy Duty exhibited at Heavy Duty Aftermarket Week in Grapevine, Texas, showcasing gas charged shocks and air springs covering more than 5,000 OE references across multiple vehicle categories.
The Expert Market Research's report titled "Global Shock Absorber Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Type
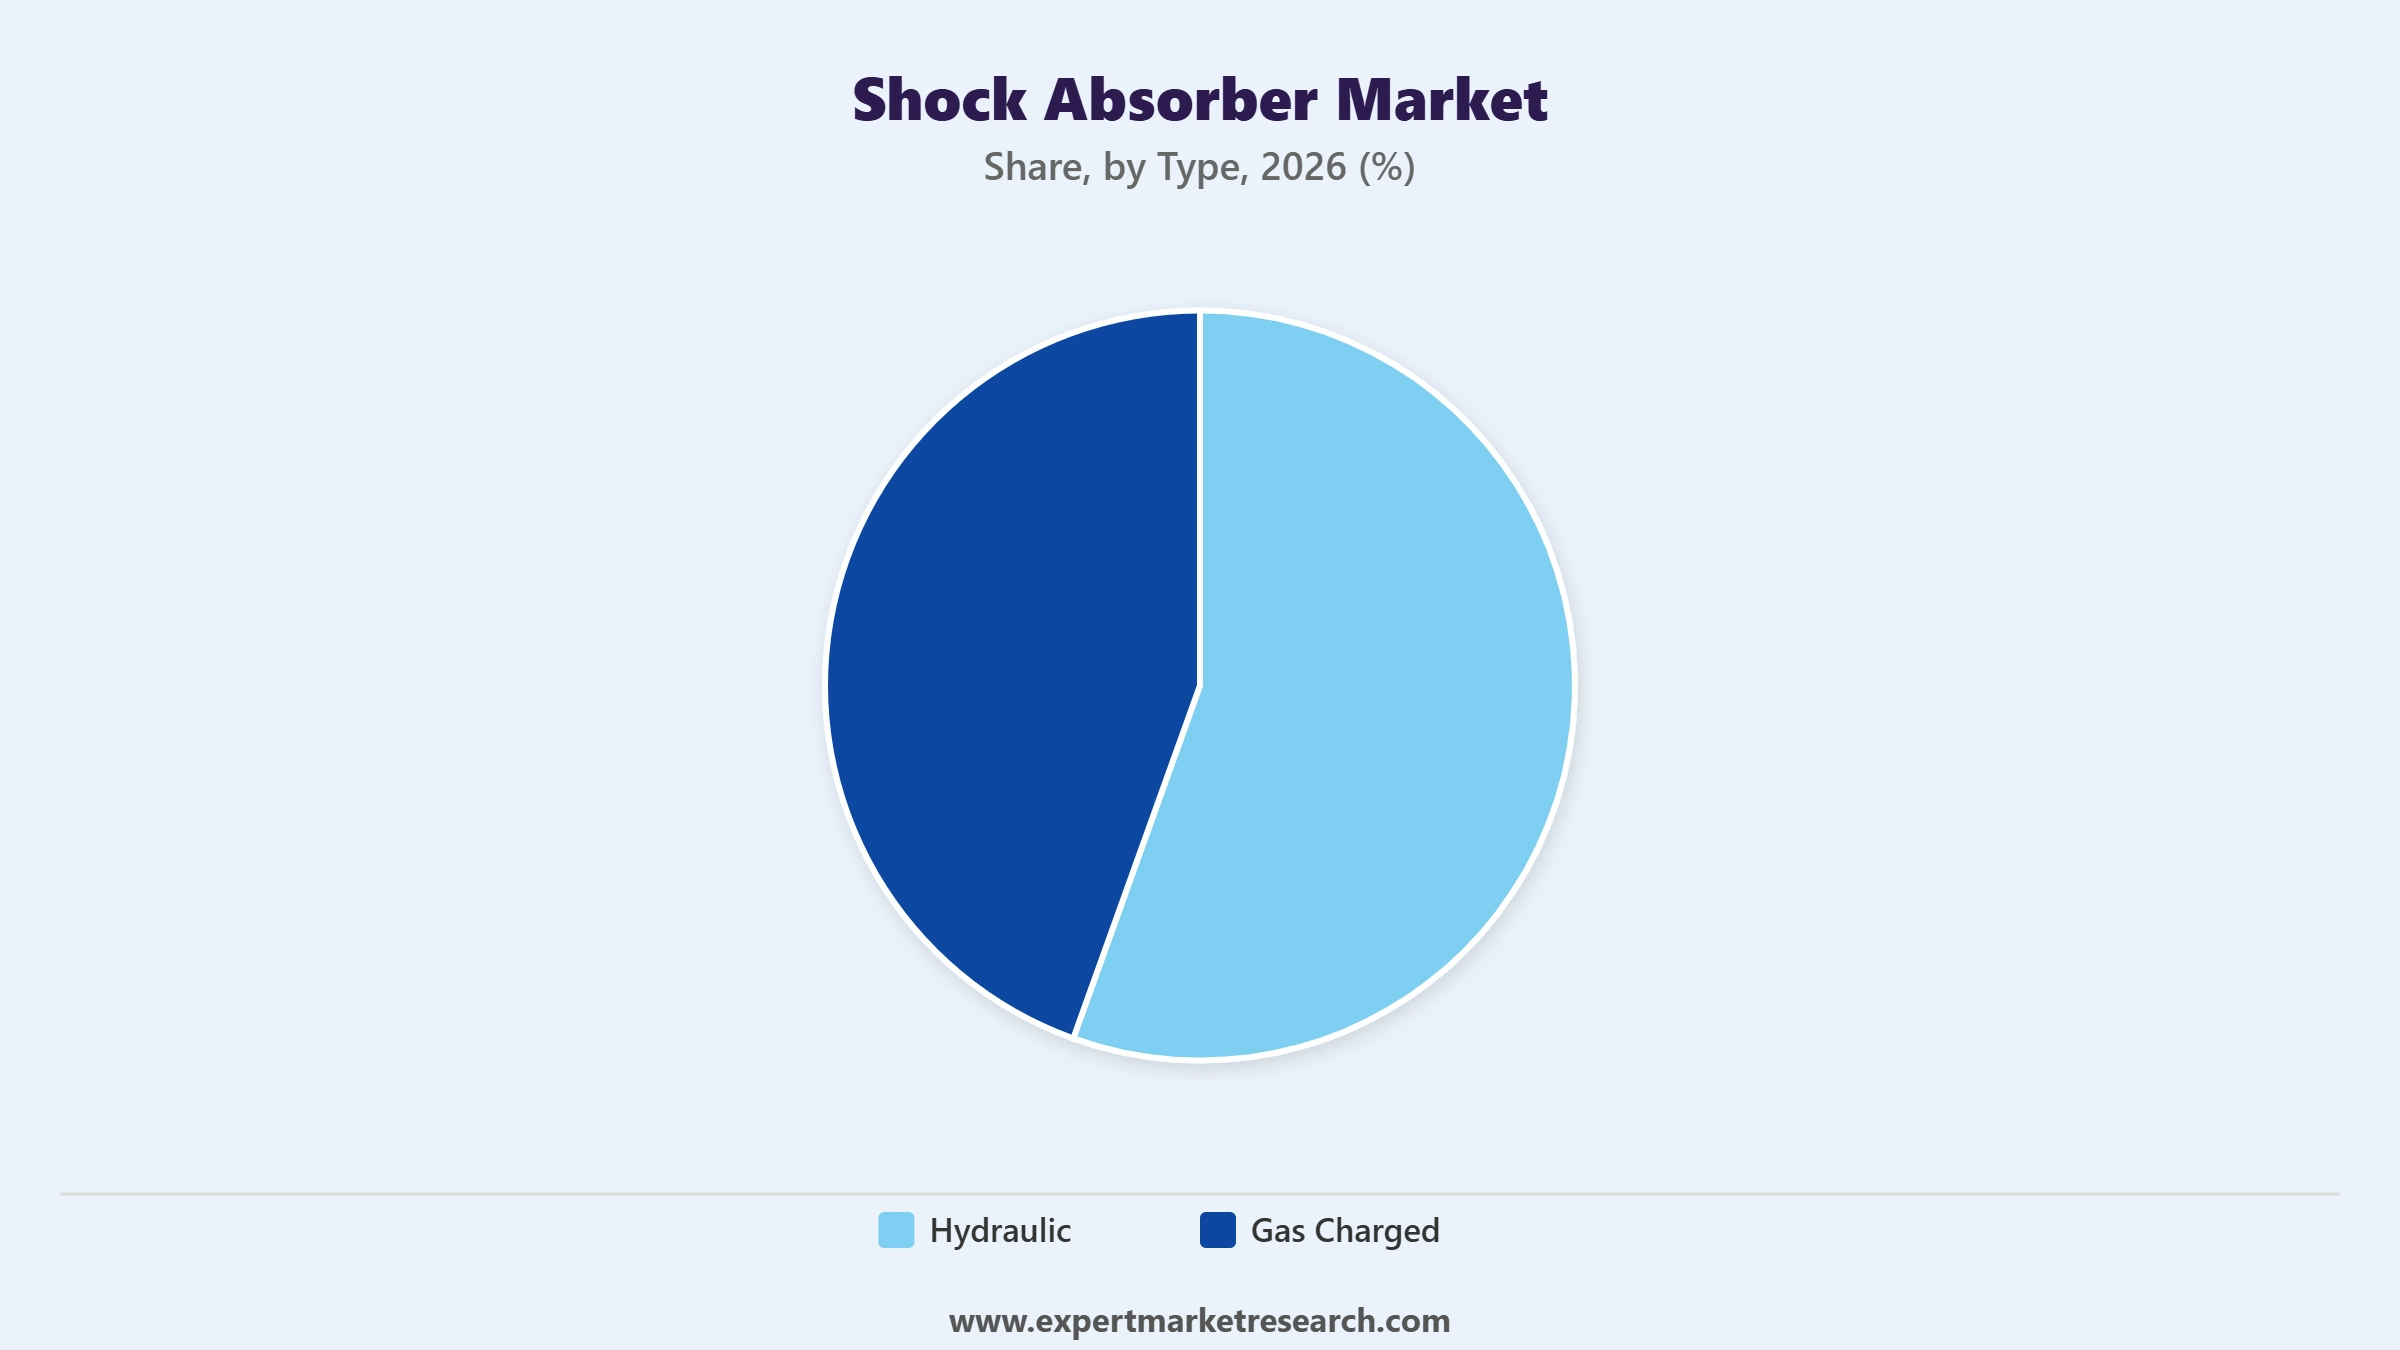
Key Insight: Hydraulic shock absorbers hold a substantial type of share of the shock absorber market as their widespread use, proven reliability, and lower manufacturing costs suit mass market vehicle applications. Gas charged shock absorbers are registering the fastest growth as their reduced fade and improved responsiveness appeal to performance oriented and premium vehicle segments.
Market Breakup by Technology
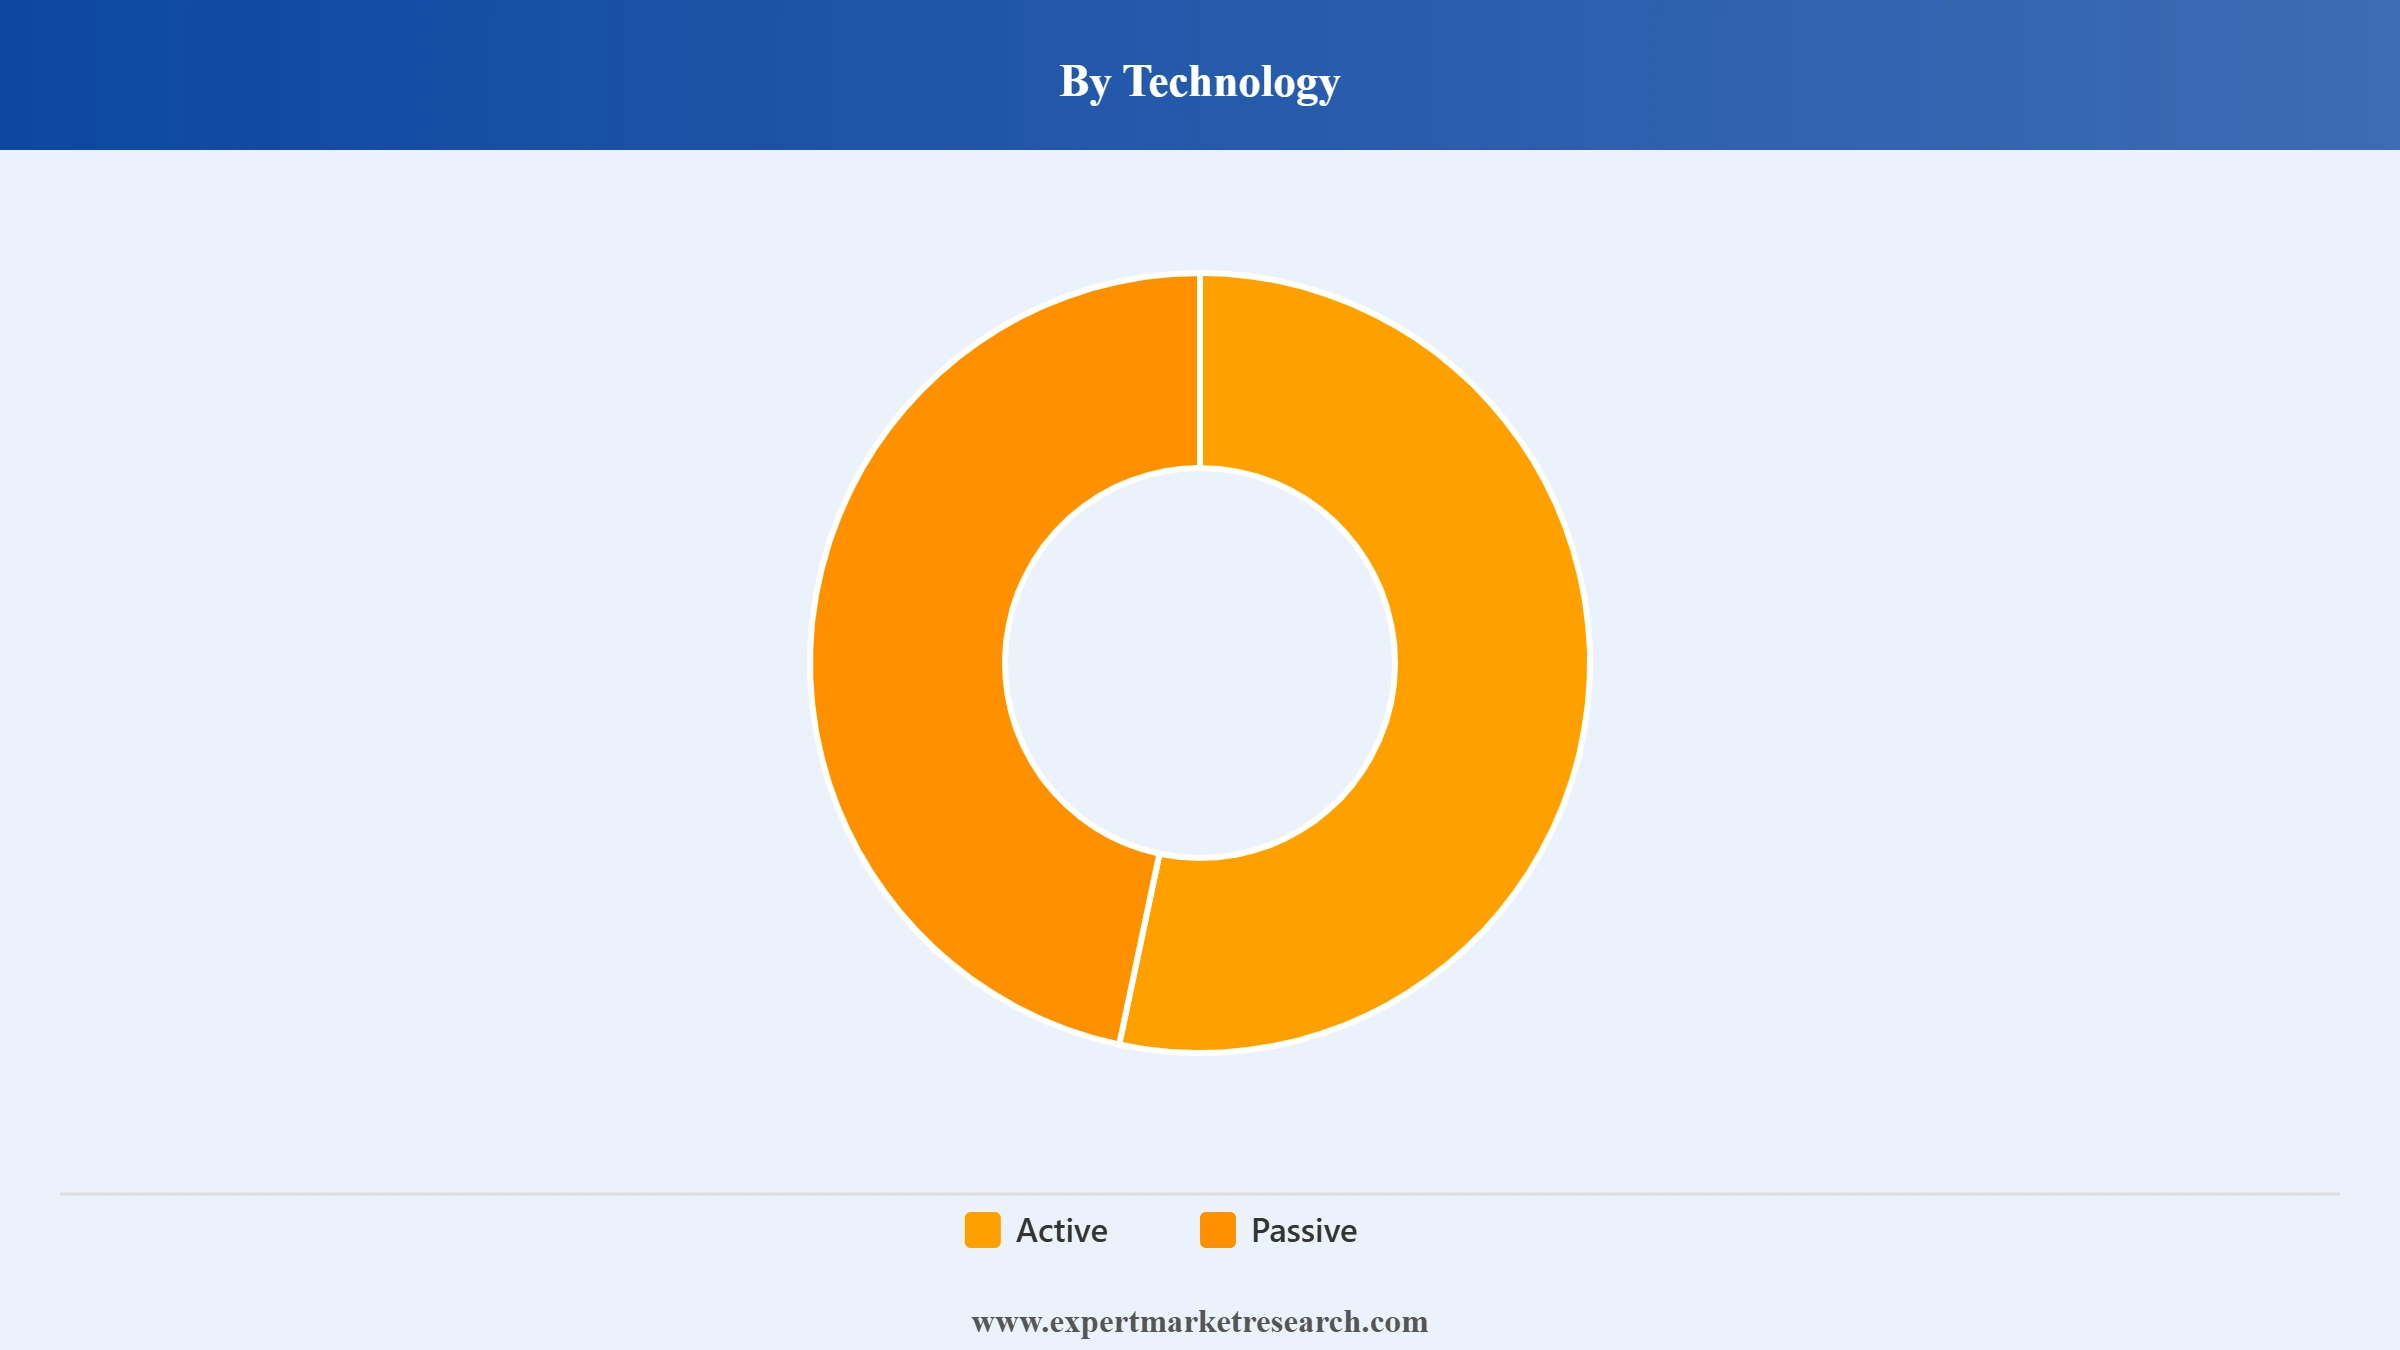
Key Insight: Passive shock absorbers account for the largest technology share in the shock absorber market given their simpler construction, lower cost, and widespread use across conventional mass market vehicles. Active shock absorbers are registering the fastest growth as automakers increasingly integrate sensor based, continuously adjustable damping systems into premium and electric vehicle platforms.
Market Breakup by Vehicle Type
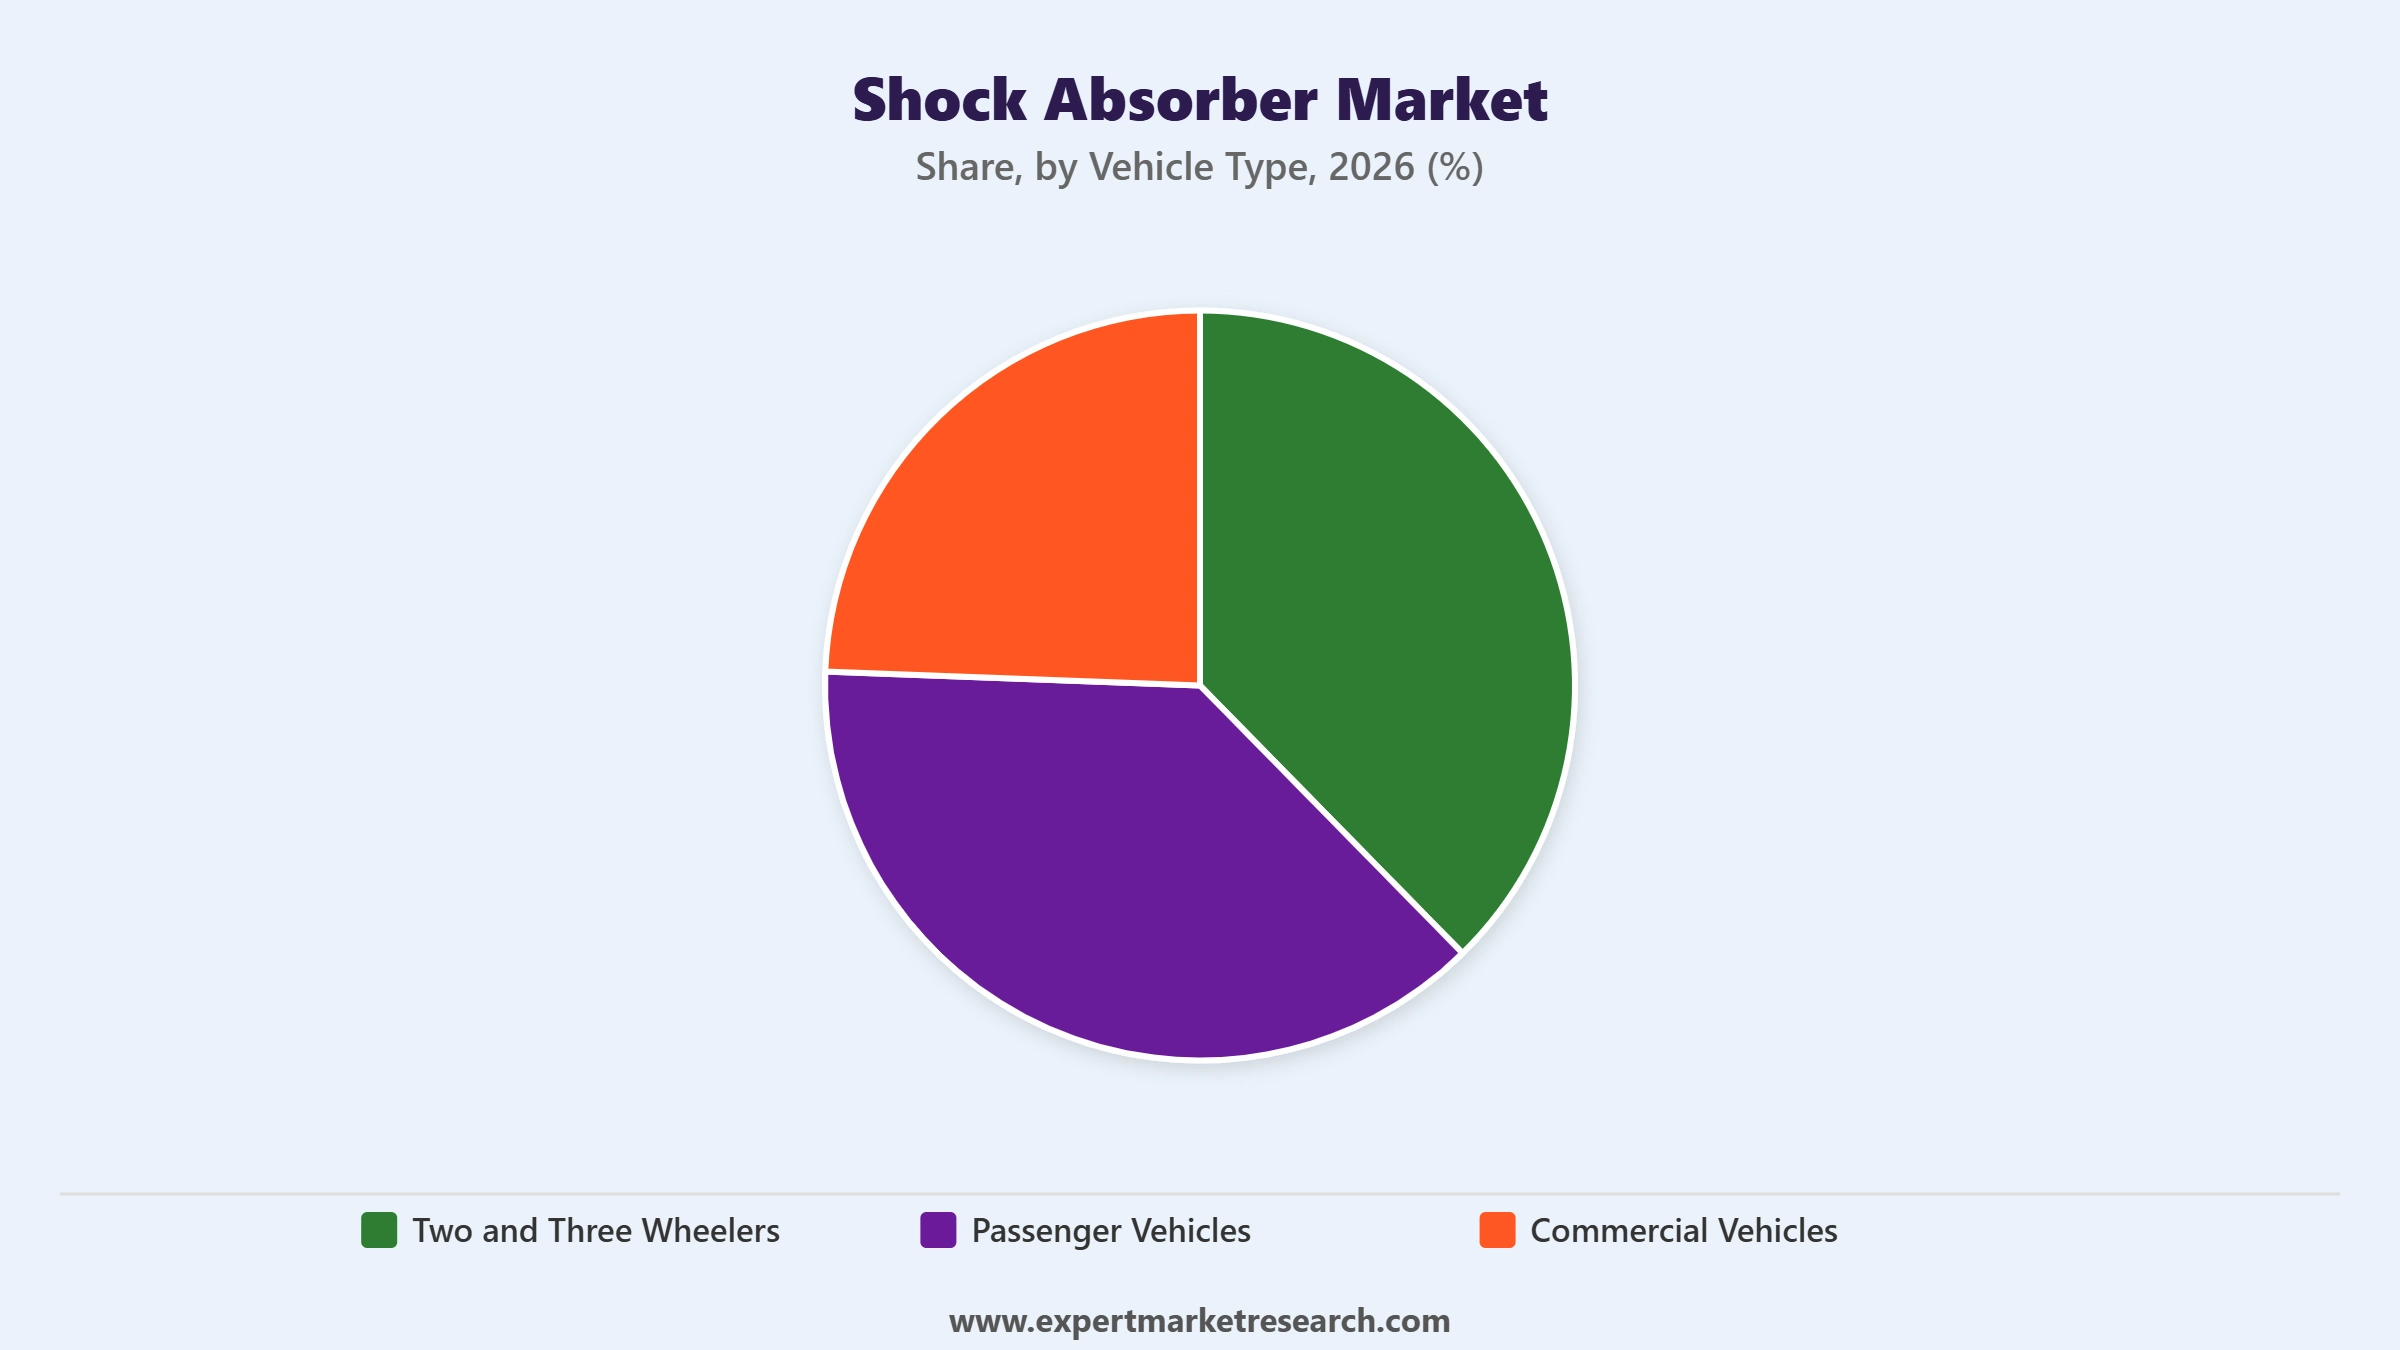
Key Insight: Passenger vehicles hold a substantial vehicle type share across the shock absorber market as rising global vehicle production and consumer demand for ride comfort sustain steady shock absorber demand. Two and three wheelers are registering strong growth across densely populated emerging markets. In October 2025, Endurance Technologies commenced commercial production at a new greenfield alloy wheel plant in Aurangabad, India, initially producing 150,000 two-wheeler wheel sets per month. Commercial vehicles rely on heavy duty shock absorbers engineered for higher load bearing capacity and durability requirements.
Market Breakup by Sales Channel
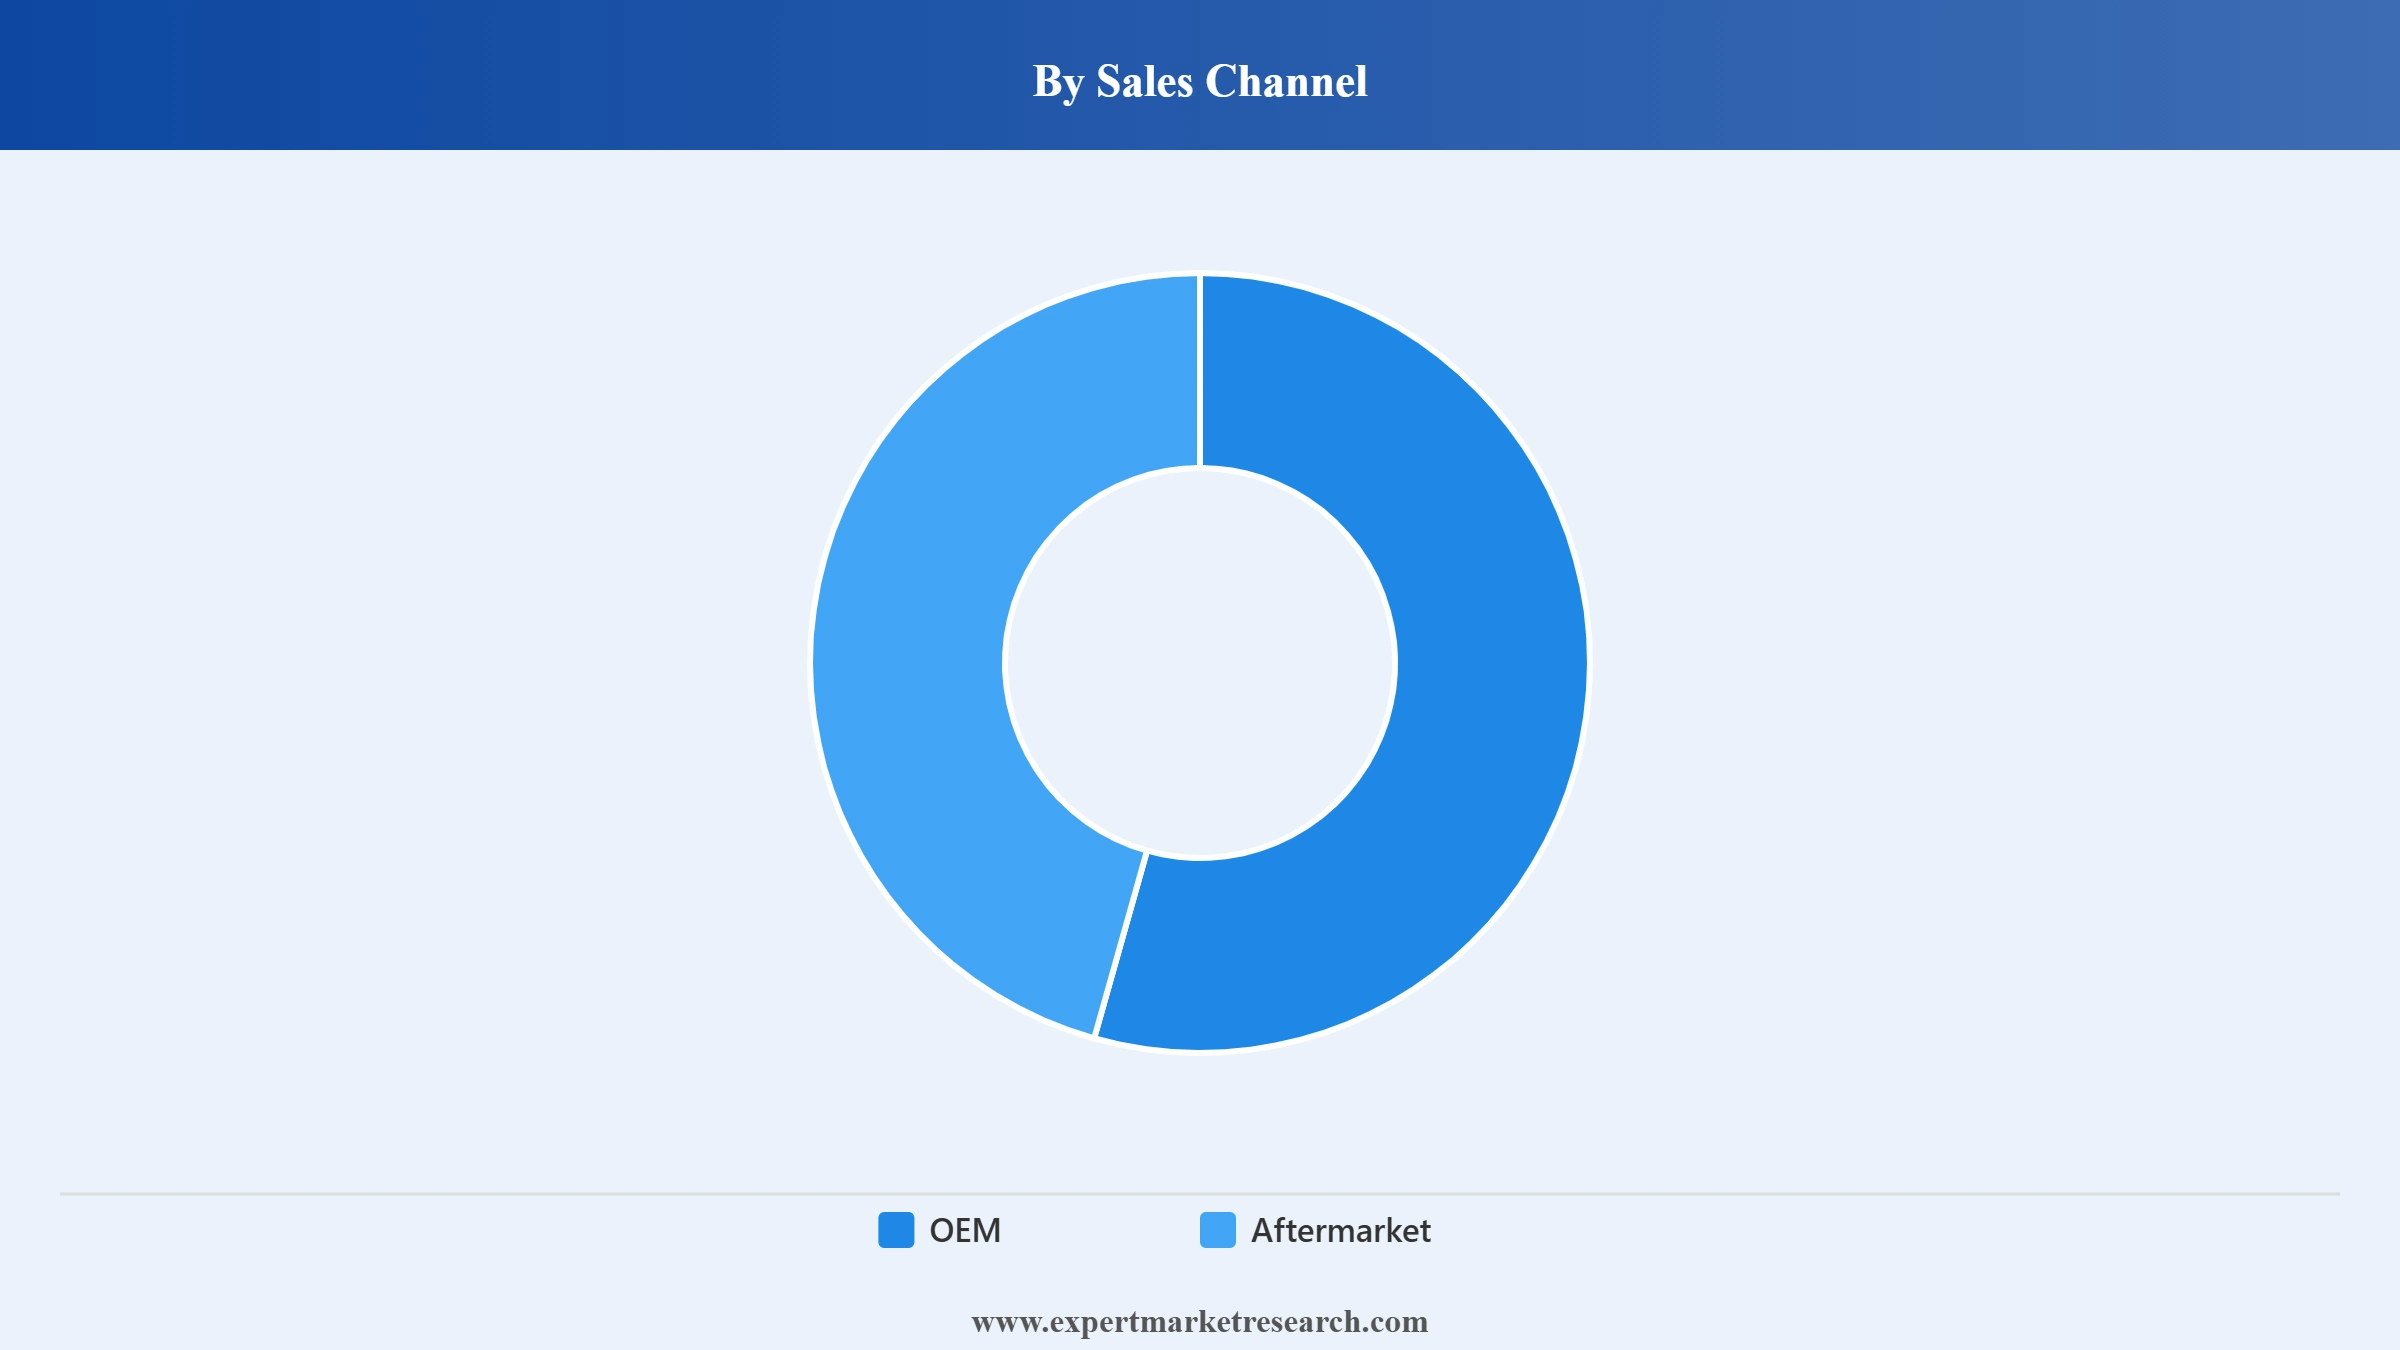
Key Insight: The OEM sales channel accounts for the largest share of the shock absorber market as automakers integrate shock absorbers directly into new vehicle production across every category. In January 2025, Dunlop Systems and Components launched a new lightweight air suspension platform targeting European and Asian automakers, aimed at electric and hybrid vehicle applications. The aftermarket channel is registering steady growth as expanding global vehicle parc continues to drive sustained replacement demand for worn suspension components.
Market Breakup by Region
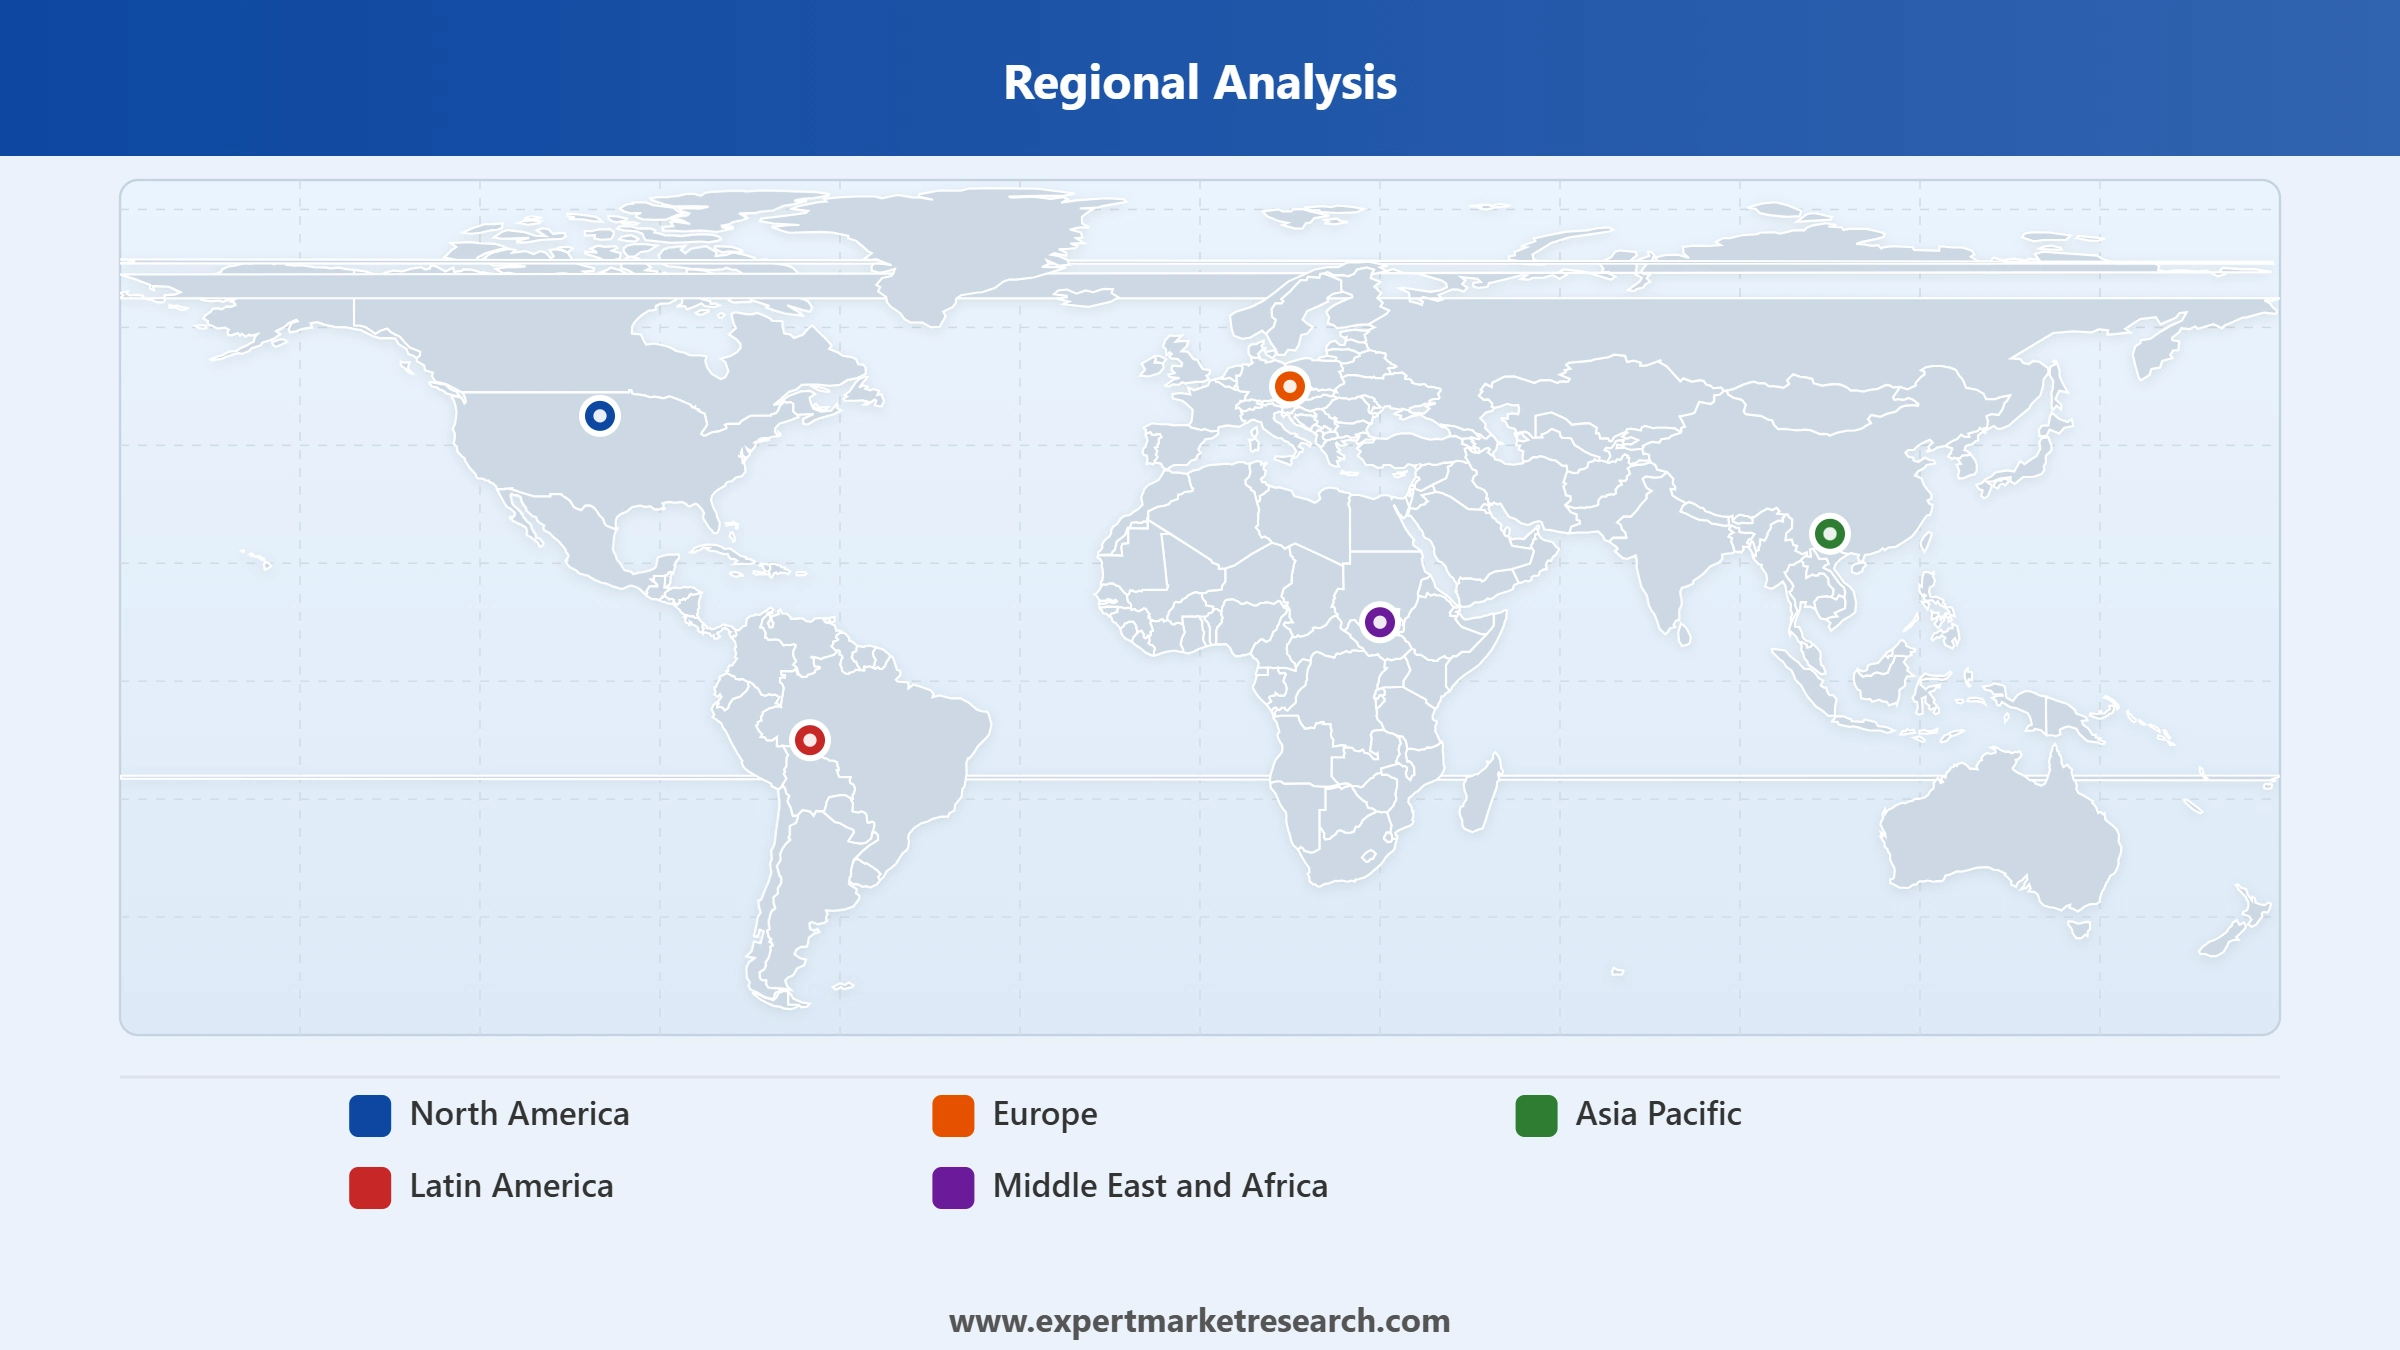
Key Insight: Asia Pacific holds a substantial regional share, supported by large scale vehicle production and rising two-wheeler demand across China, India, and Japan. Europe sustains steady demand from established premium and performance vehicle manufacturing, while North America benefits from strong aftermarket replacement activity. Latin America and the Middle East and Africa round out demand through gradually expanding vehicle fleets and infrastructure development.




Read more about this report - Request a Free Sample
By type, hydraulic shock absorbers dominate the market owing to their widespread use, proven reliability, and lower manufacturing costs across mass market vehicles
Hydraulic shock absorbers dominate the type of segment of the shock absorber market owing to their widespread use, proven reliability, and considerably lower manufacturing costs across mass market vehicles worldwide and across every region and price bracket. Suppliers serving this category continue to prioritise durability improvements accordingly, since hydraulic units must withstand sustained use across varied road conditions and climates over exceptionally long vehicle lifespans, particularly in regions with poor road infrastructure and extreme weather variation across every season.
Read more about this report - Request a Free Sample
Gas charged shock absorbers are registering the fastest type of growth as their reduced fade and improved responsiveness appeal to performance oriented and premium vehicle segments globally across every major automotive market. In March 2025, KYB Corporation expanded its production capacity in Asia by opening a new manufacturing plant in Vietnam, aiming to meet growing regional demand for gas charged suspension components across Southeast Asian markets and neighbouring export destinations throughout the wider Asia Pacific region.
By technology, passive shock absorbers account for the largest share owing to their simpler construction and lower cost across conventional mass market vehicles
Passive shock absorbers account for the largest technology share in the shock absorber market given their simpler construction, lower cost, and widespread use across conventional mass market vehicles worldwide today and for the foreseeable future across every region. Suppliers serving this category continue to prioritise manufacturing efficiency accordingly, since passive systems compete primarily on cost and reliability alongside proven mechanical durability across every vehicle segment and price point available to budget conscious buyers worldwide and across generations.
Read more about this report - Request a Free Sample
Active shock absorbers are registering the fastest technology growth as automakers increasingly integrate sensor based, continuously adjustable damping systems into premium and electric vehicle platforms worldwide and across every price tier available. In March 2025, Bosch announced a strategic partnership with Showa Corporation to co-develop next-generation semi-active suspension systems for electric vehicles, combining sensing electronics with damping expertise for smarter, load responsive ride control across diverse driving conditions and terrains.
By vehicle type, passenger vehicles account for the largest share owing to rising global vehicle production and consumer demand for ride comfort
Passenger vehicles hold a substantial vehicle type share of the shock absorber market as rising global vehicle production and consumer demand for ride comfort sustain steady shock absorber demand worldwide across every income bracket and region. In April 2025, Tenneco's Monroe Ride Solutions business introduced the Monroe Intelligent Suspension CVSA2, a semi-active suspension technology designed for passenger vehicle segments including SUVs, off-road vehicles, and luxury cars nationwide across multiple automaker platforms and vehicle categories worldwide.
Read more about this report - Request a Free Sample
Two and three wheelers are registering strong vehicle type growth across densely populated emerging markets where affordable personal mobility remains in high demand among cost conscious commuters worldwide. According to figures released by Honda in early 2025, the company produces approximately 20 million two wheelers annually, with India, Indonesia, Thailand, and Vietnam together accounting for around 85 percent of global sales volume across these fast-growing emerging economies and neighbouring regional markets.
By sales channel, the OEM segment holds a substantial share owing to automakers integrating shock absorbers directly into new vehicle production
The OEM sales channel accounts for the largest share of the shock absorber market as automakers integrate shock absorbers directly into new vehicle production across every category worldwide today and into the foreseeable future ahead. Suppliers serving this category continue to prioritise long term supply agreements accordingly, since OEM contracts typically span multiple vehicle production cycles and require sustained quality consistency across every plant, region, and vehicle platform served by suppliers worldwide.
Read more about this report - Request a Free Sample
The aftermarket channel is registering steady growth as expanding global vehicle parc drives sustained replacement demand for worn suspension components across ageing vehicle fleets worldwide and across every region. In May 2025, Magneti Marelli Parts and Services launched a new range of air suspension compressors, completing its aftermarket catalogue covering air springs, air dampers, and oil-gas shock absorbers across the European aftermarket and neighbouring international distribution networks serving independent repair shops everywhere.
Asia Pacific leads the market through large scale vehicle production and rising two-wheeler demand
Asia Pacific holds a substantial share of the market, supported by large scale vehicle production and steadily rising two-wheeler demand across China, India, and Japan and neighbouring markets. As of November 2025, India's Production Linked Incentive Scheme for the automobile and auto component industry had disbursed 1,350.83 crore rupees in incentives to 82 approved applicants, supporting expanded domestic manufacturing of suspension and other advanced automotive technology products across the country's rapidly growing industrial manufacturing base.
Europe is registering steady regional demand as established premium and performance vehicle manufacturing sustains consistent shock absorber consumption across the region's leading automotive manufacturing hubs and export centres. In November 2025, Euro NCAP announced its largest protocol revision since 2009, introducing enhanced handling dynamics evaluation criteria from 2026 that are expected to push automakers toward more sophisticated suspension specifications across every new passenger vehicle platform sold throughout the European market.
Read more about this report - Request a Free Sample
Shock absorber companies range from century old German engineering conglomerates to Japanese hydraulics specialists, reflecting a market built on decades of automotive supply relationships and cross border technology transfer. Shock absorber players increasingly compete on integrated suspension system capability and electronic damping technology as much as on conventional hydraulic engineering, with premium suppliers acquiring adjacent suspension brands to broaden their vehicle dynamics portfolios and enter new performance segments.
Established shock absorber market players continue to dominate OEM contracts through decades of engineering trust and long-standing supply chain relationships built across every major vehicle manufacturing region. Meanwhile, acquisitions are actively reshaping the premium performance segment, as braking specialists and Indian component makers expand into suspension through targeted asset purchases and accelerated market entry. This blend of legacy engineering depth and targeted consolidation defines competitive dynamics heading into the next decade.
Founded in 1915 and headquartered in Friedrichshafen, Germany, ZF Friedrichshafen supports the market through its Sachs branded damping systems serving passenger and commercial vehicle manufacturers worldwide. The company continues to expand its active suspension and electronic damping portfolio across premium vehicle segments. ZF draws on more than a century of chassis engineering expertise to serve OEM customers across every major vehicle category.
Founded in 1999 and headquartered in Duisburg and Essen, Germany, thyssenkrupp supports the market through its Bilstein branded suspension systems serving premium and performance vehicle manufacturers. The company continues to expand its integrated air suspension and semi-active damping capabilities through strategic partnerships. thyssenkrupp draws on decades of precision engineering expertise to serve OEM and aftermarket customers globally.
Founded in 1930 and headquartered in Lake Forest, Illinois, United States, Tenneco supports the market through its Monroe branded ride control products serving OEM and aftermarket customers worldwide. The company continues to streamline its business portfolio following the divestiture of select suspension brands. Tenneco draws on nearly a century of ride control expertise to serve customers across passenger and commercial vehicle segments.
Founded in 1919 and headquartered in Tokyo, Japan, KYB Corporation supports the market as one of the world's largest hydraulic shock absorber manufacturers, producing more than 75 million units annually. The company continues to expand its manufacturing footprint across Asia, Europe, and North America. KYB draws on more than a century of hydraulics expertise to serve automotive, motorcycle, and railway customers worldwide.
Other key players in the market include Marelli Holdings Co., Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our global shock absorber market trends 2026 report. Discover regional growth patterns, vehicle type adoption, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 15.35 Billion.
The market is projected to grow at a CAGR of 4.00% between 2026 and 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach USD 22.72 Billion by 2035.
Pursuing strategic acquisitions to expand manufacturing capacity and technology portfolios, forming cross border partnerships to combine complementary suspension technologies, investing in AI driven adaptive damping systems, and redesigning components for electric vehicle platforms ahead of rising adoption.
The implementation of stringent safety regulations for automobiles and the rising emphasis on comfort and ride quality are expected to aid the expansion of the market.
The major regional markets are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa.
The different vehicle types include two and three-wheelers, passenger vehicles, and commercial vehicles.
The leading types in the market are hydraulic and gas charged.
The significant modes of technology of shock absorber in the market are active, and passive.
The key players in the market include ZF Friedrichshafen AG, thyssenkrupp AG, Tenneco Inc., KYB Corporation, Marelli Holdings Co., Ltd., among others.
The market is broken down into North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa.
Companies face rising costs of electronic components and sensors, a shortage of engineers skilled in active suspension systems, high research and development costs for adaptive damping technology, and the ongoing challenge of redesigning suspension systems for heavier electric vehicle platforms.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Type |
|
| Breakup by Technology |
|
| Breakup by Vehicle Type |
|
| Breakup by Sales Channel |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




