

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
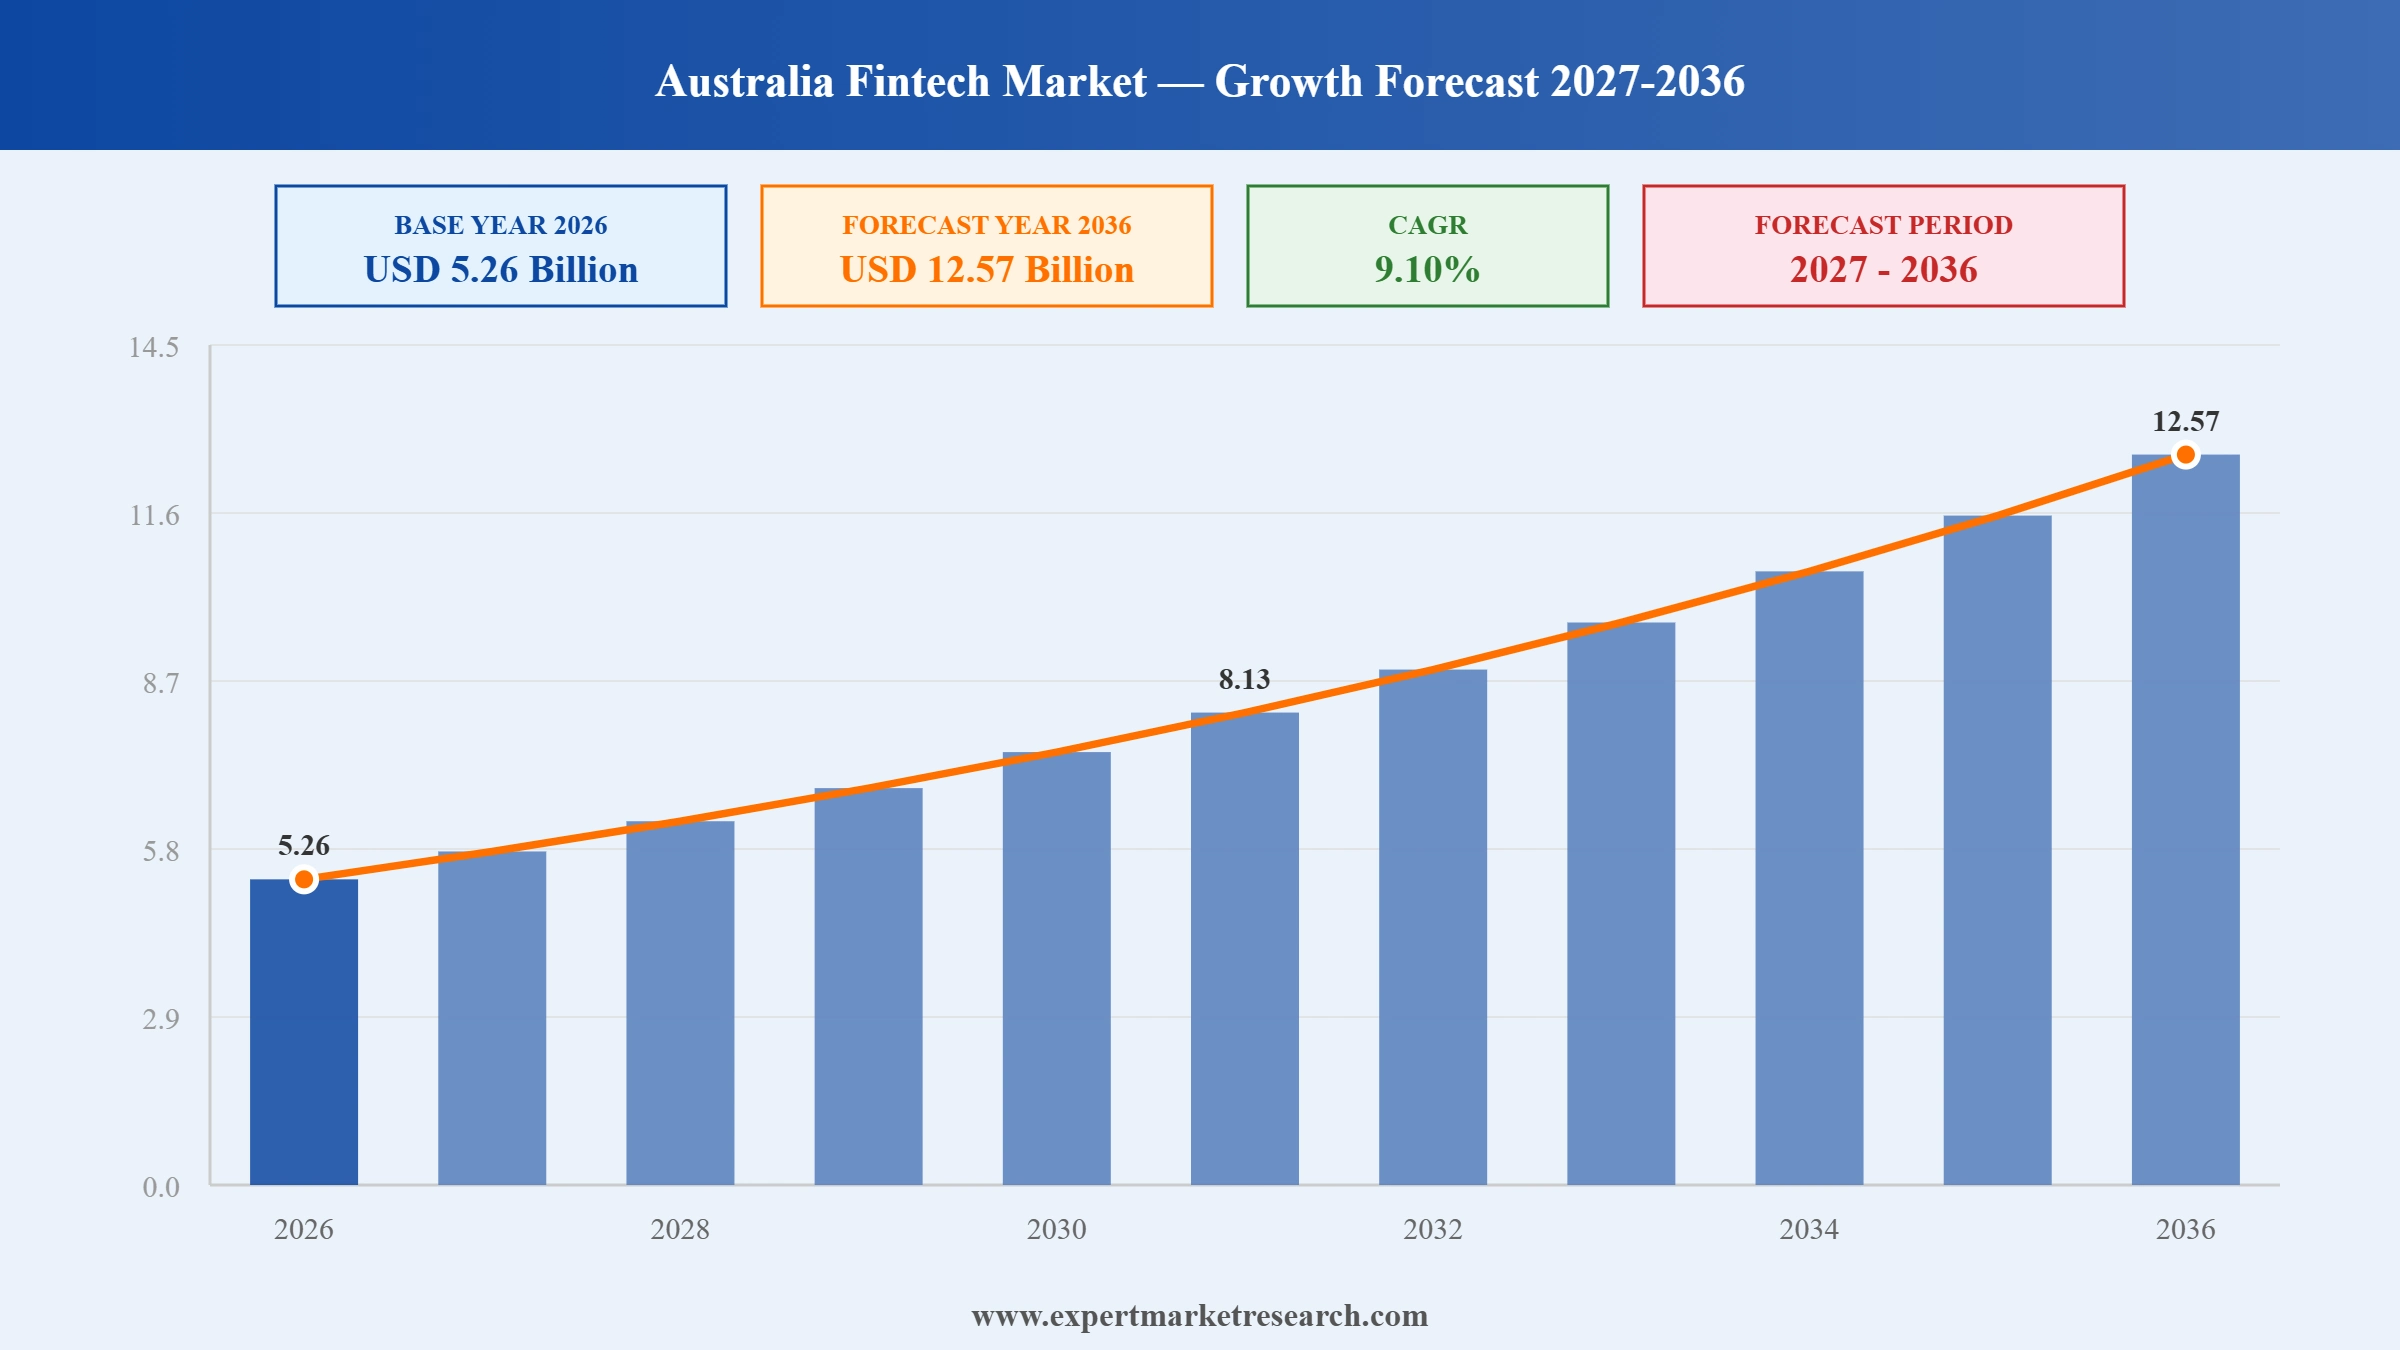
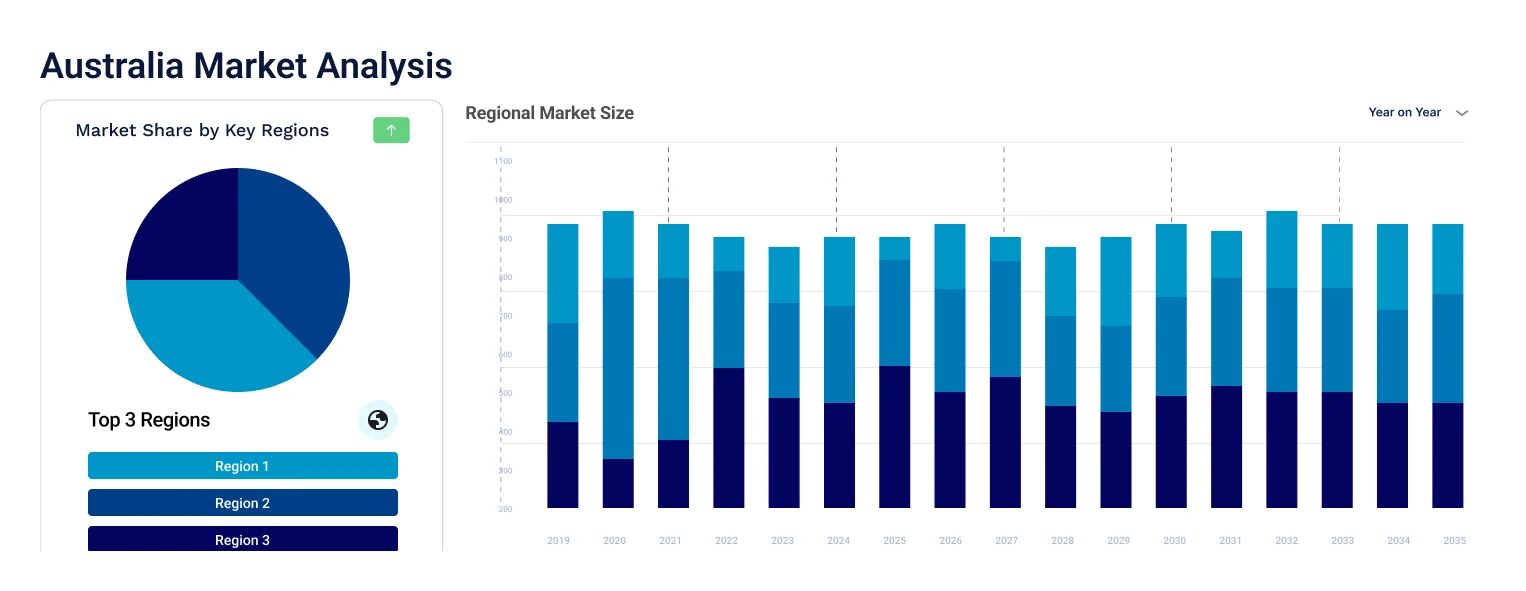
The Australia fintech market attained a value of USD 4.82 Billion in 2025 and is projected to grow at a CAGR of 9.10% through 2035. The market is further expected to reach USD 11.52 Billion by 2035. Rising digital payment adoption, expanding open banking initiatives, and growing investment in financial technology solutions are driving overall growth in the Australia fintech market, with cloud native platforms and embedded finance reshaping how consumers and businesses access banking, lending, and payment services.
The Australia fintech market encompasses digital payments, alternative lending, digital banking, wealth management, and insurtech solutions delivered through both on premises and cloud-based deployment models. Demand continues to be shaped by high smartphone penetration, the Consumer Data Right framework, and a maturing startup ecosystem, with New South Wales accounting for the largest regional share given its concentration of licensed banking institutions and venture capital activity supporting the Australia fintech market.
Established Australia fintech companies are increasingly securing large funding rounds to scale payment infrastructure and expand into new international markets, reflecting strong investor confidence in the sector's growth trajectory. In December 2025, Airwallex closed a 330-million-dollar Series G funding round at an 8-billion-dollar valuation, with participation from T. Rowe Price and Robinhood Ventures, as overall funding into Australia fintech companies more than doubled during the 2026 financial year.
Established Australia fintech companies are increasingly directing growth capital toward geographic diversification and product broadening rather than concentrating solely on domestic payment rails, reflecting a strategic shift toward building durable, multi market revenue bases as local competition intensifies. Companies are pursuing parallel investment across cross border payments, merchant lending, and property technology rather than remaining narrowly focused on a single vertical, while strengthening partnerships between banks, retailers, and technology platforms to accelerate customer acquisition across both consumer and small business segments. In May 2026, Airwallex secured a new funding round at an approximately 11-billion-dollar valuation, led by Addition, underscoring the pace of this expansion.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
PEXA launched PEXA Clear, one of the first Anti Money Laundering and Counter Terrorism Financing solutions built specifically for the property industry, timed to coincide with new AUSTRAC regulations affecting real estate and legal practitioners. Companies across the Australia fintech market can leverage purpose-built compliance tools to help regulated customers meet new obligations without disrupting existing workflows or operations across the sector.
Zeller launched a national hospitality campaign and grant programme offering 5,000 dollar grants to new venue operators, drawing on transaction data showing Australians dining out more frequently while spending less per visit. Companies across the Australia fintech market can leverage proprietary transaction data to design targeted merchant support programmes that build brand loyalty within specific industry verticals and segments across markets.
Zeller launched Terminal 1x, an all-in-one point of sale and payment terminal priced at 199 dollars with no ongoing software fees, aiming to undercut incumbent providers and save merchants up to 2,000 dollars annually on payment hardware costs nationwide. Companies across the Australia fintech market can leverage low cost, integrated hardware to win small business customers away from established payment providers and platforms.
Athena Home Loans launched a new bridging loan product and scenario modelling tool exclusively for Mortgage Choice and LMG brokers, expanding its non-bank lending portfolio beyond standard refinancing and home loan products. Companies can leverage broker exclusive product launches to deepen distribution partnerships while diversifying revenue beyond core lending categories and segments across markets.
Established Australia fintech companies across the Australia fintech market operating as challenger banks are increasingly launching new deposit products to diversify funding sources beyond wholesale markets, rather than relying solely on term deposits, as loan books continue expanding steadily. This is helping banks lower blended funding costs while offering savers more flexible, at call product options. In February 2026, Judo Bank launched its Direct Online Savings Account, contributing to a call savings balances exceeding 1.1 billion dollars across its deposit franchise nationally.
Established buy now pay later providers across the Australia fintech market are increasingly restructuring compliance and product design processes to operate under formal credit licensing requirements, rather than the lighter touch rules that previously governed instalment products broadly. This is helping providers align distribution and complaints handling with mainstream credit standards demanded by regulators. In June 2025, BNPL credit activities in Australia became subject to a formal Australian credit licence requirement, reshaping how Afterpay and Zip design and distribute their products nationally.
Established Australia fintech companies across the Australia fintech market are increasingly closing large, investor backed funding rounds to fund international expansion, rather than scaling through organic revenue alone, as competition for global payments market share intensifies worldwide and steadily. This is helping companies accelerate headcount growth and product development across new geographies simultaneously. Airwallex has pledged to invest more than 1.5 billion dollars into its United States operations between 2026 and 2029, planning to more than double its local headcount nationwide.
Established property technology platforms across the Australia fintech market are increasingly launching purpose-built compliance solutions ahead of new anti-money laundering deadlines, rather than retrofitting existing workflows, to help regulated customers prepare in advance broadly. This is helping platforms deepen relationships with conveyancers and legal practitioners facing new obligations. PEXA has expanded its United Kingdom operations since 2022, partnering with NatWest to deliver digital remortgage transactions, extending its property technology platform beyond its Australian home market and broader customer base.
Established payment terminal providers are increasingly launching low cost, integrated hardware to directly challenge incumbent point of sale providers, rather than competing solely on software features, as small business merchants seek to reduce fixed costs broadly. This is helping challenger providers win merchant accounts from established payment processors. In October 2025, Zeller Terminal 2 won the Australian Good Design Award along with WeMoney's Merchant Terminal of the Year and Merchant Payment Provider of the Year awards.
Expert Market Research's report titled “Australia Fintech Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Deployment Mode
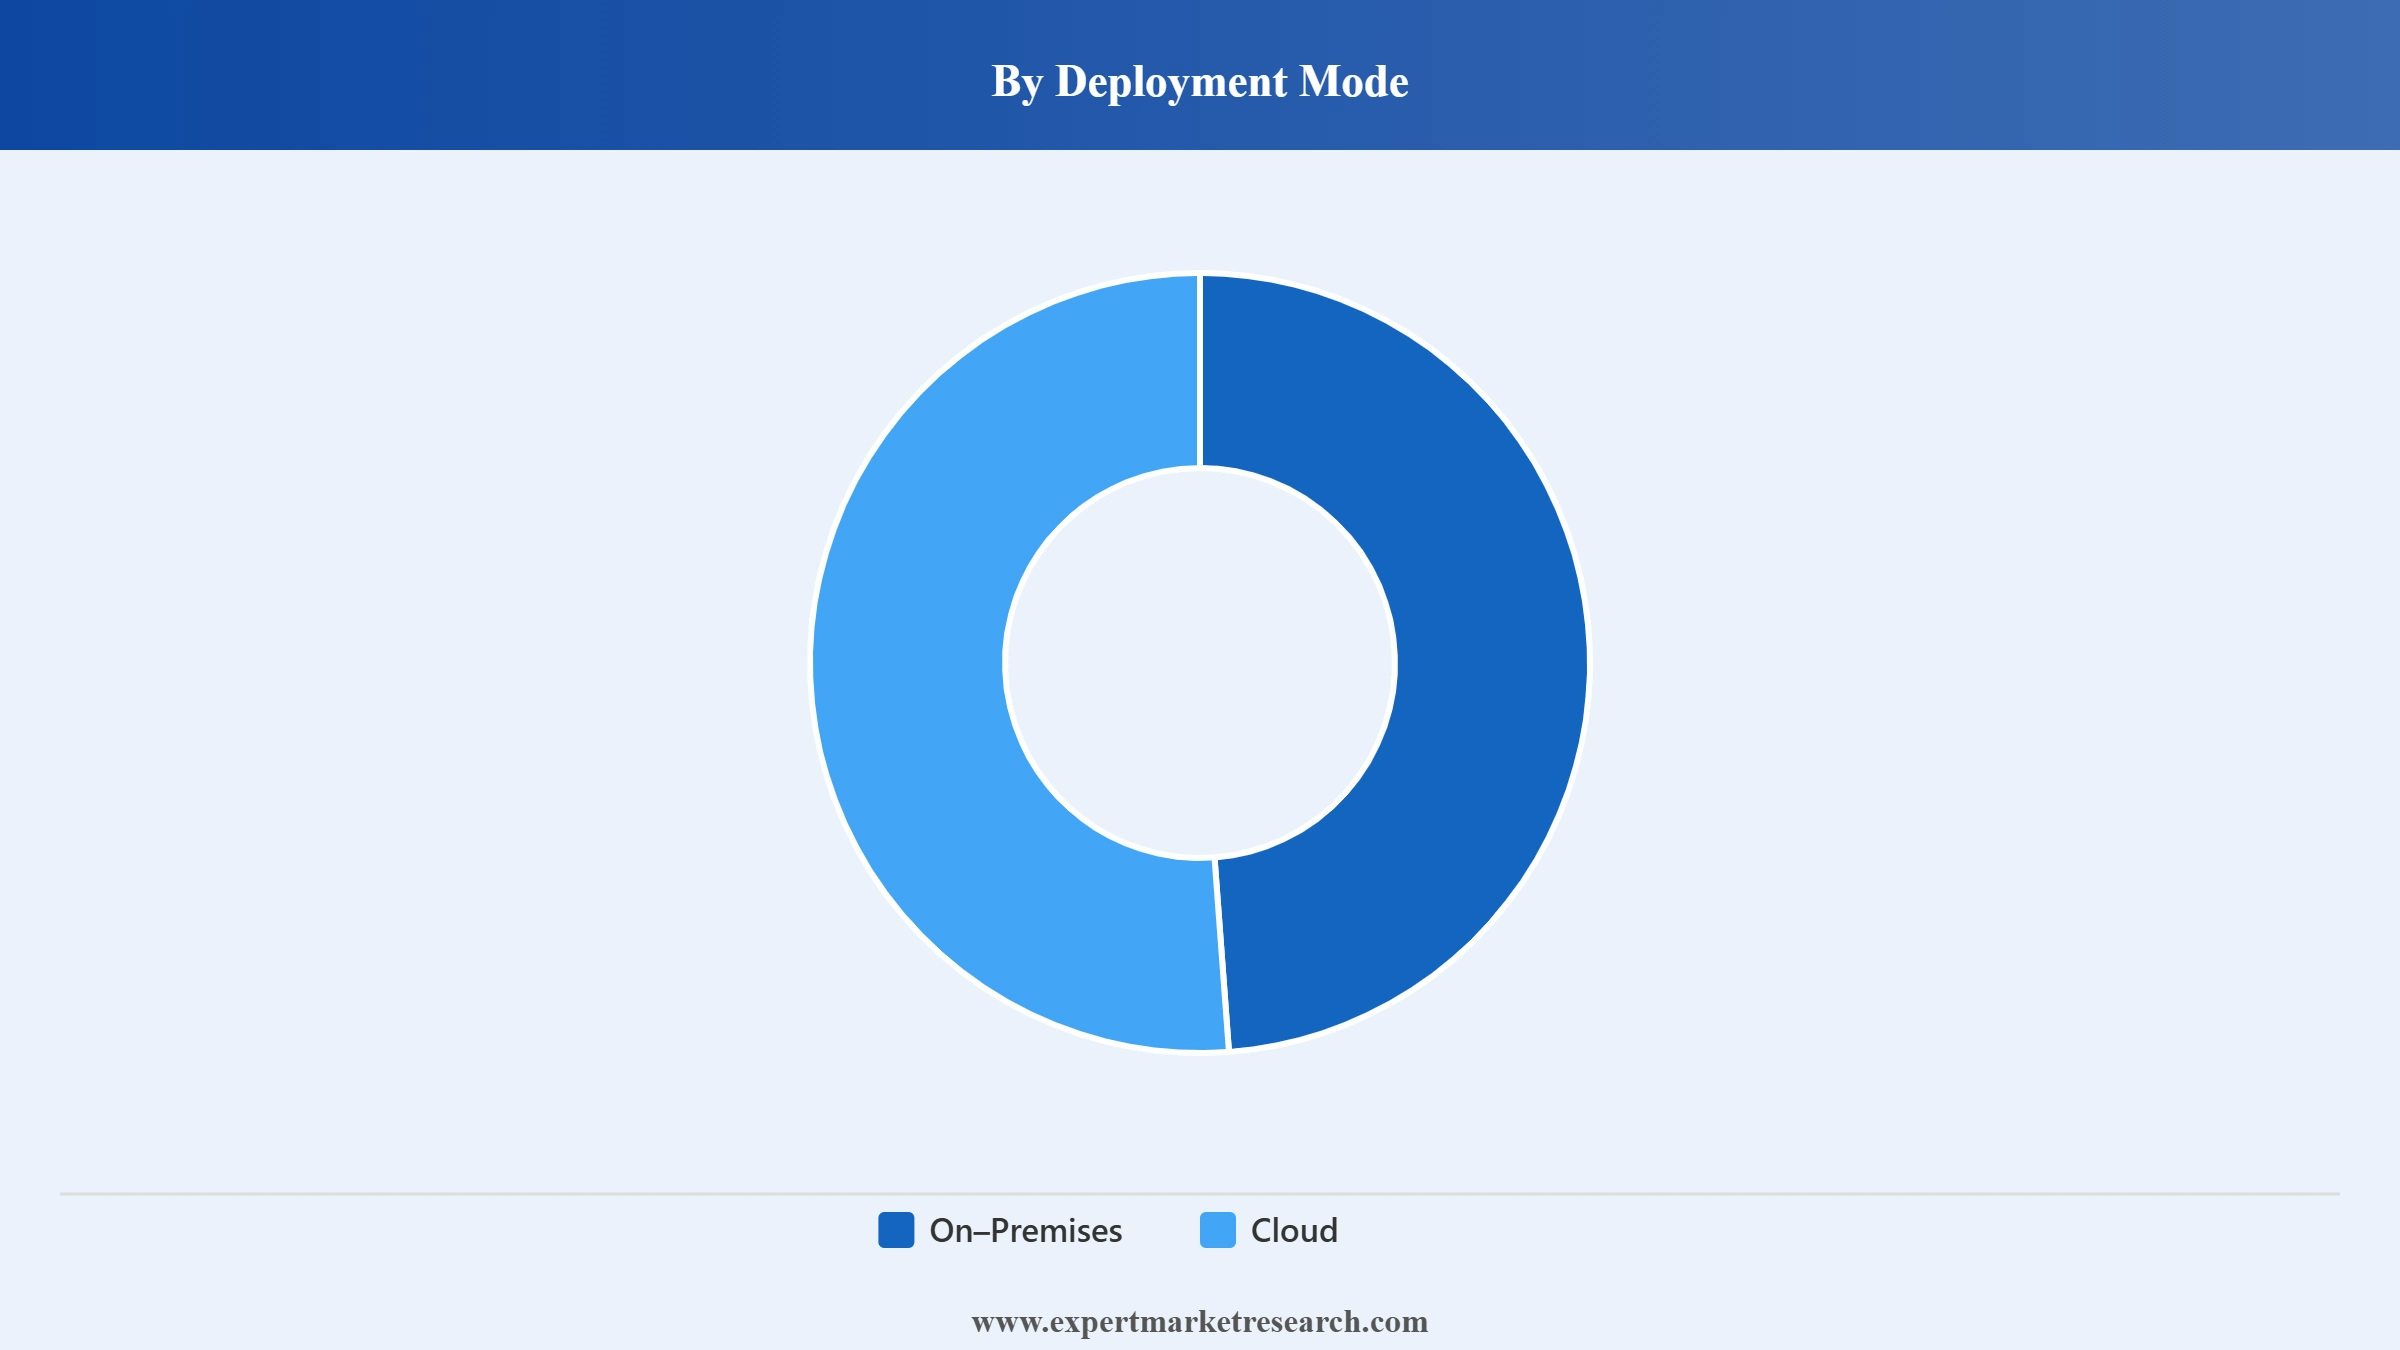
Key Insight: On-Premises: Legacy financial institutions and select regulated entities continue to rely on on-premises deployment for core systems requiring direct infrastructure control and data residency assurance. Cloud: Cloud dominates deployment mode given its scalability, lower upfront costs, and faster rollout of new products, a pattern confirmed by the wider Australia fintech market where cloud native platforms are increasingly the default choice for new entrants and incumbents alike.
Market Breakup by Technology
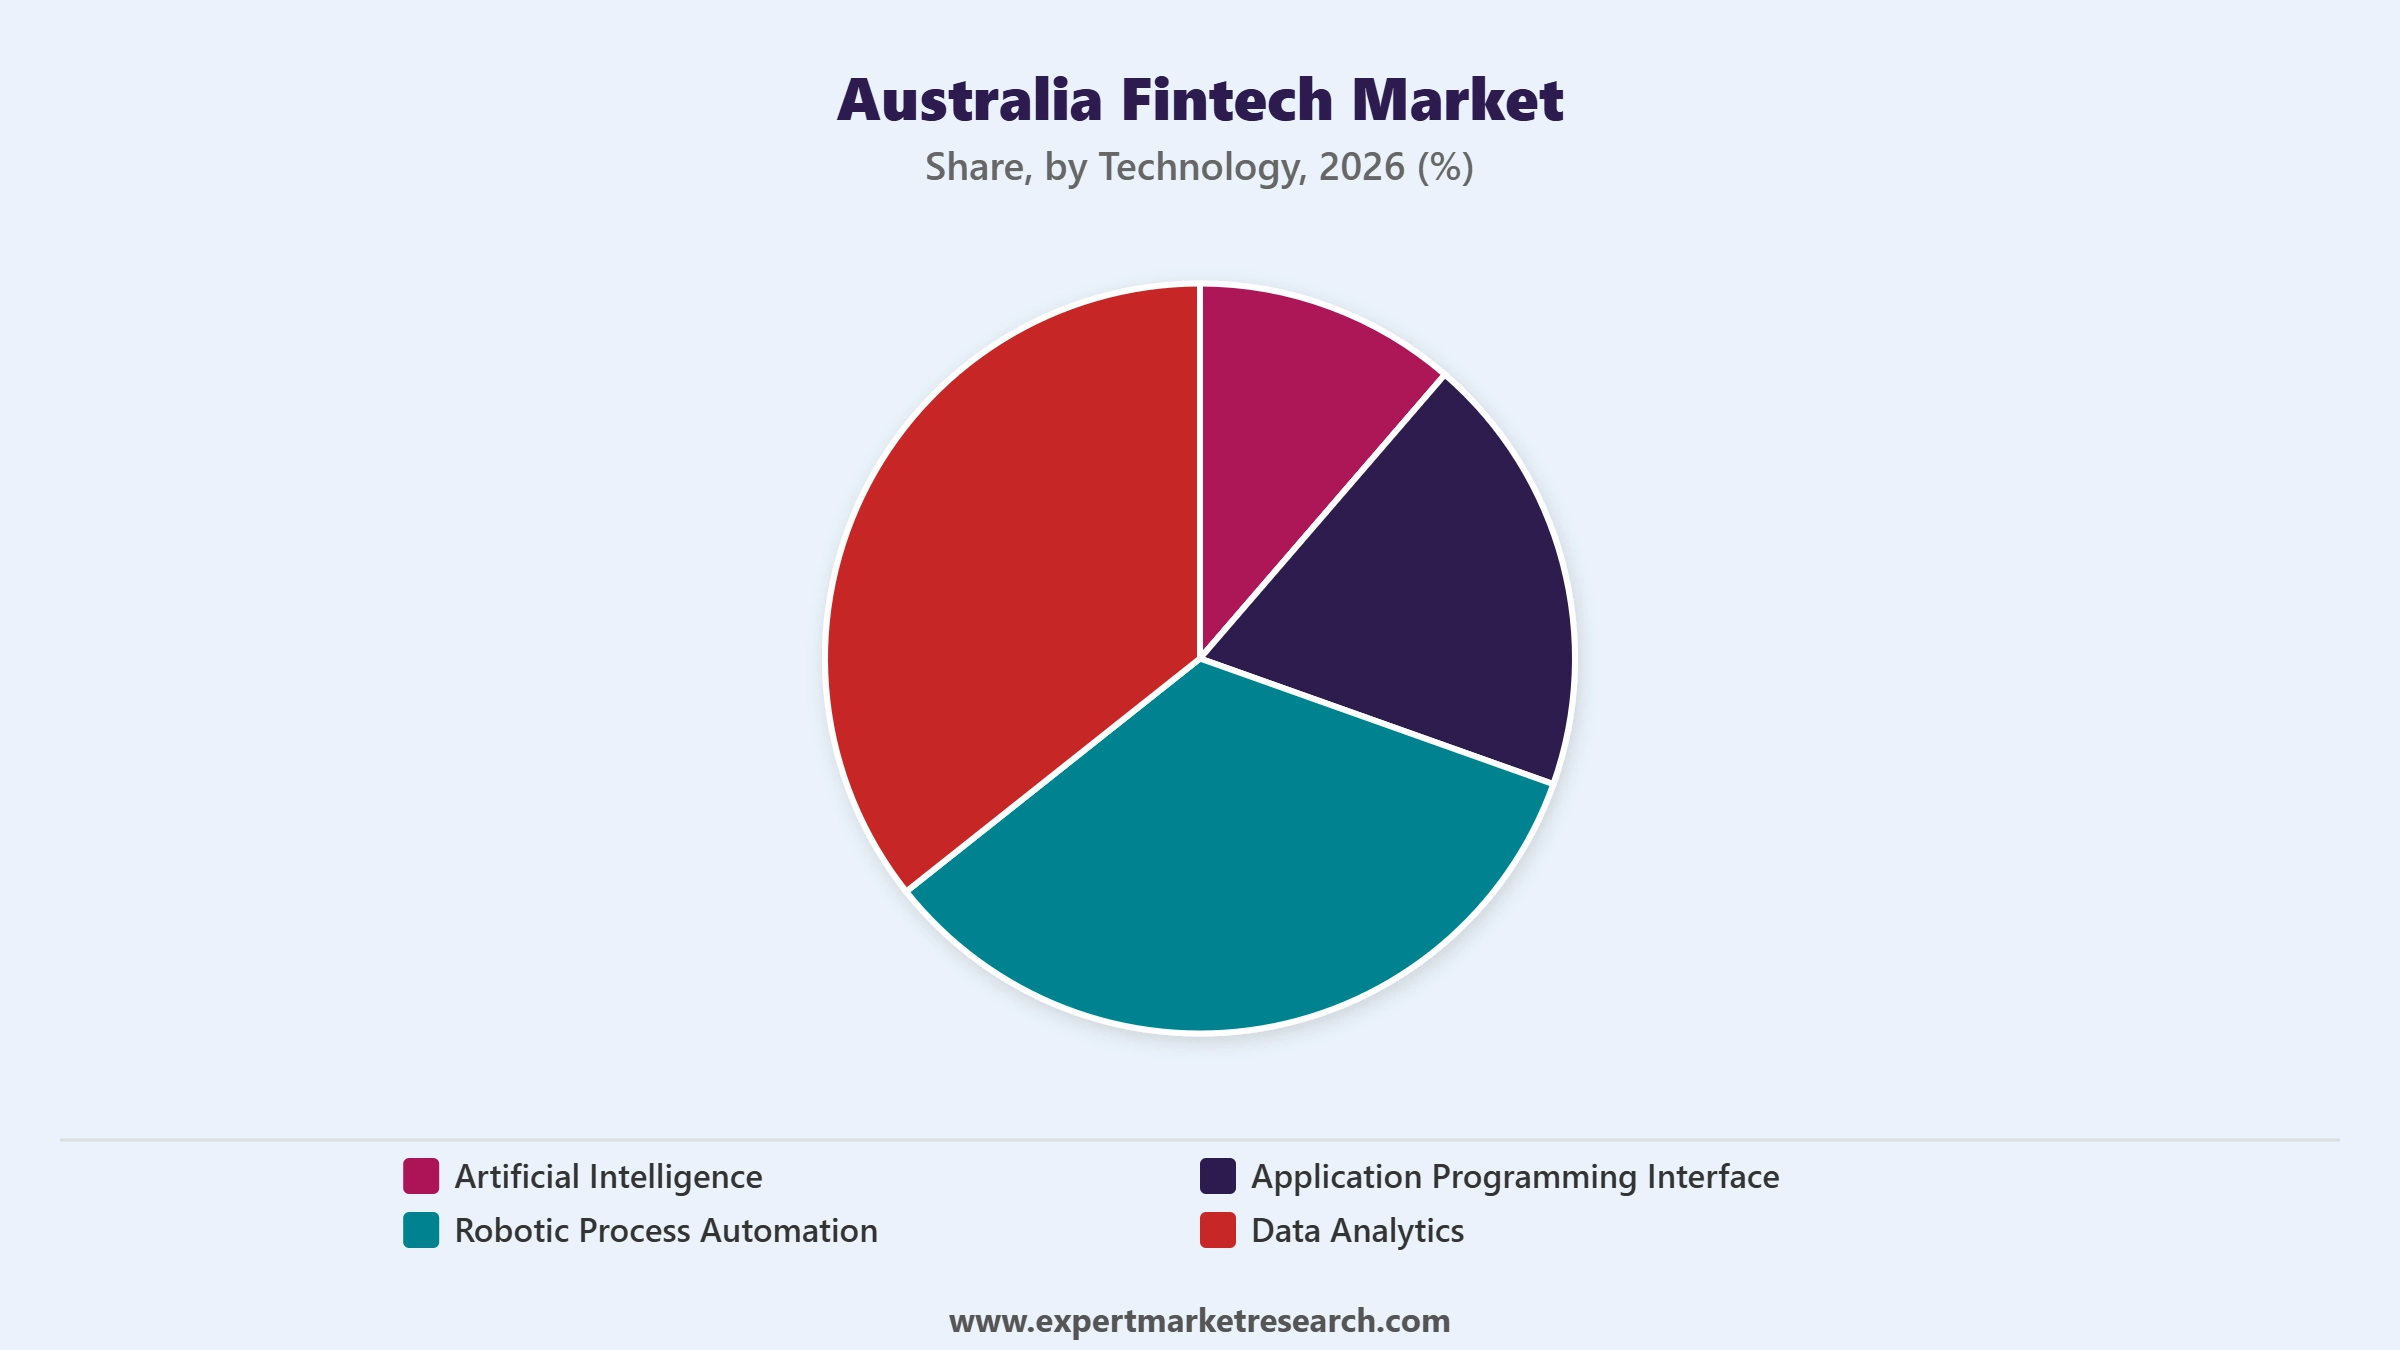
Key Insight: Artificial Intelligence: AI powered underwriting, fraud detection, and personalised financial advice are becoming standard features across lending and wealth management platforms. Application Programming Interface (API): Open banking APIs under the Consumer Data Right enable secure data sharing between banks and third-party providers, illustrated by AMP's February 2025 launch of a new online bank built on Starling Bank's API driven Engine platform for solopreneurs and micro enterprises. Robotic Process Automation: RPA streamlines back-office reconciliation and compliance reporting tasks for banks and lenders. Data Analytics: Data analytics underpins credit risk scoring and customer segmentation across digital lending platforms. Others: Emerging technologies including blockchain and biometric authentication continue to see early-stage adoption.
Market Breakup by Application
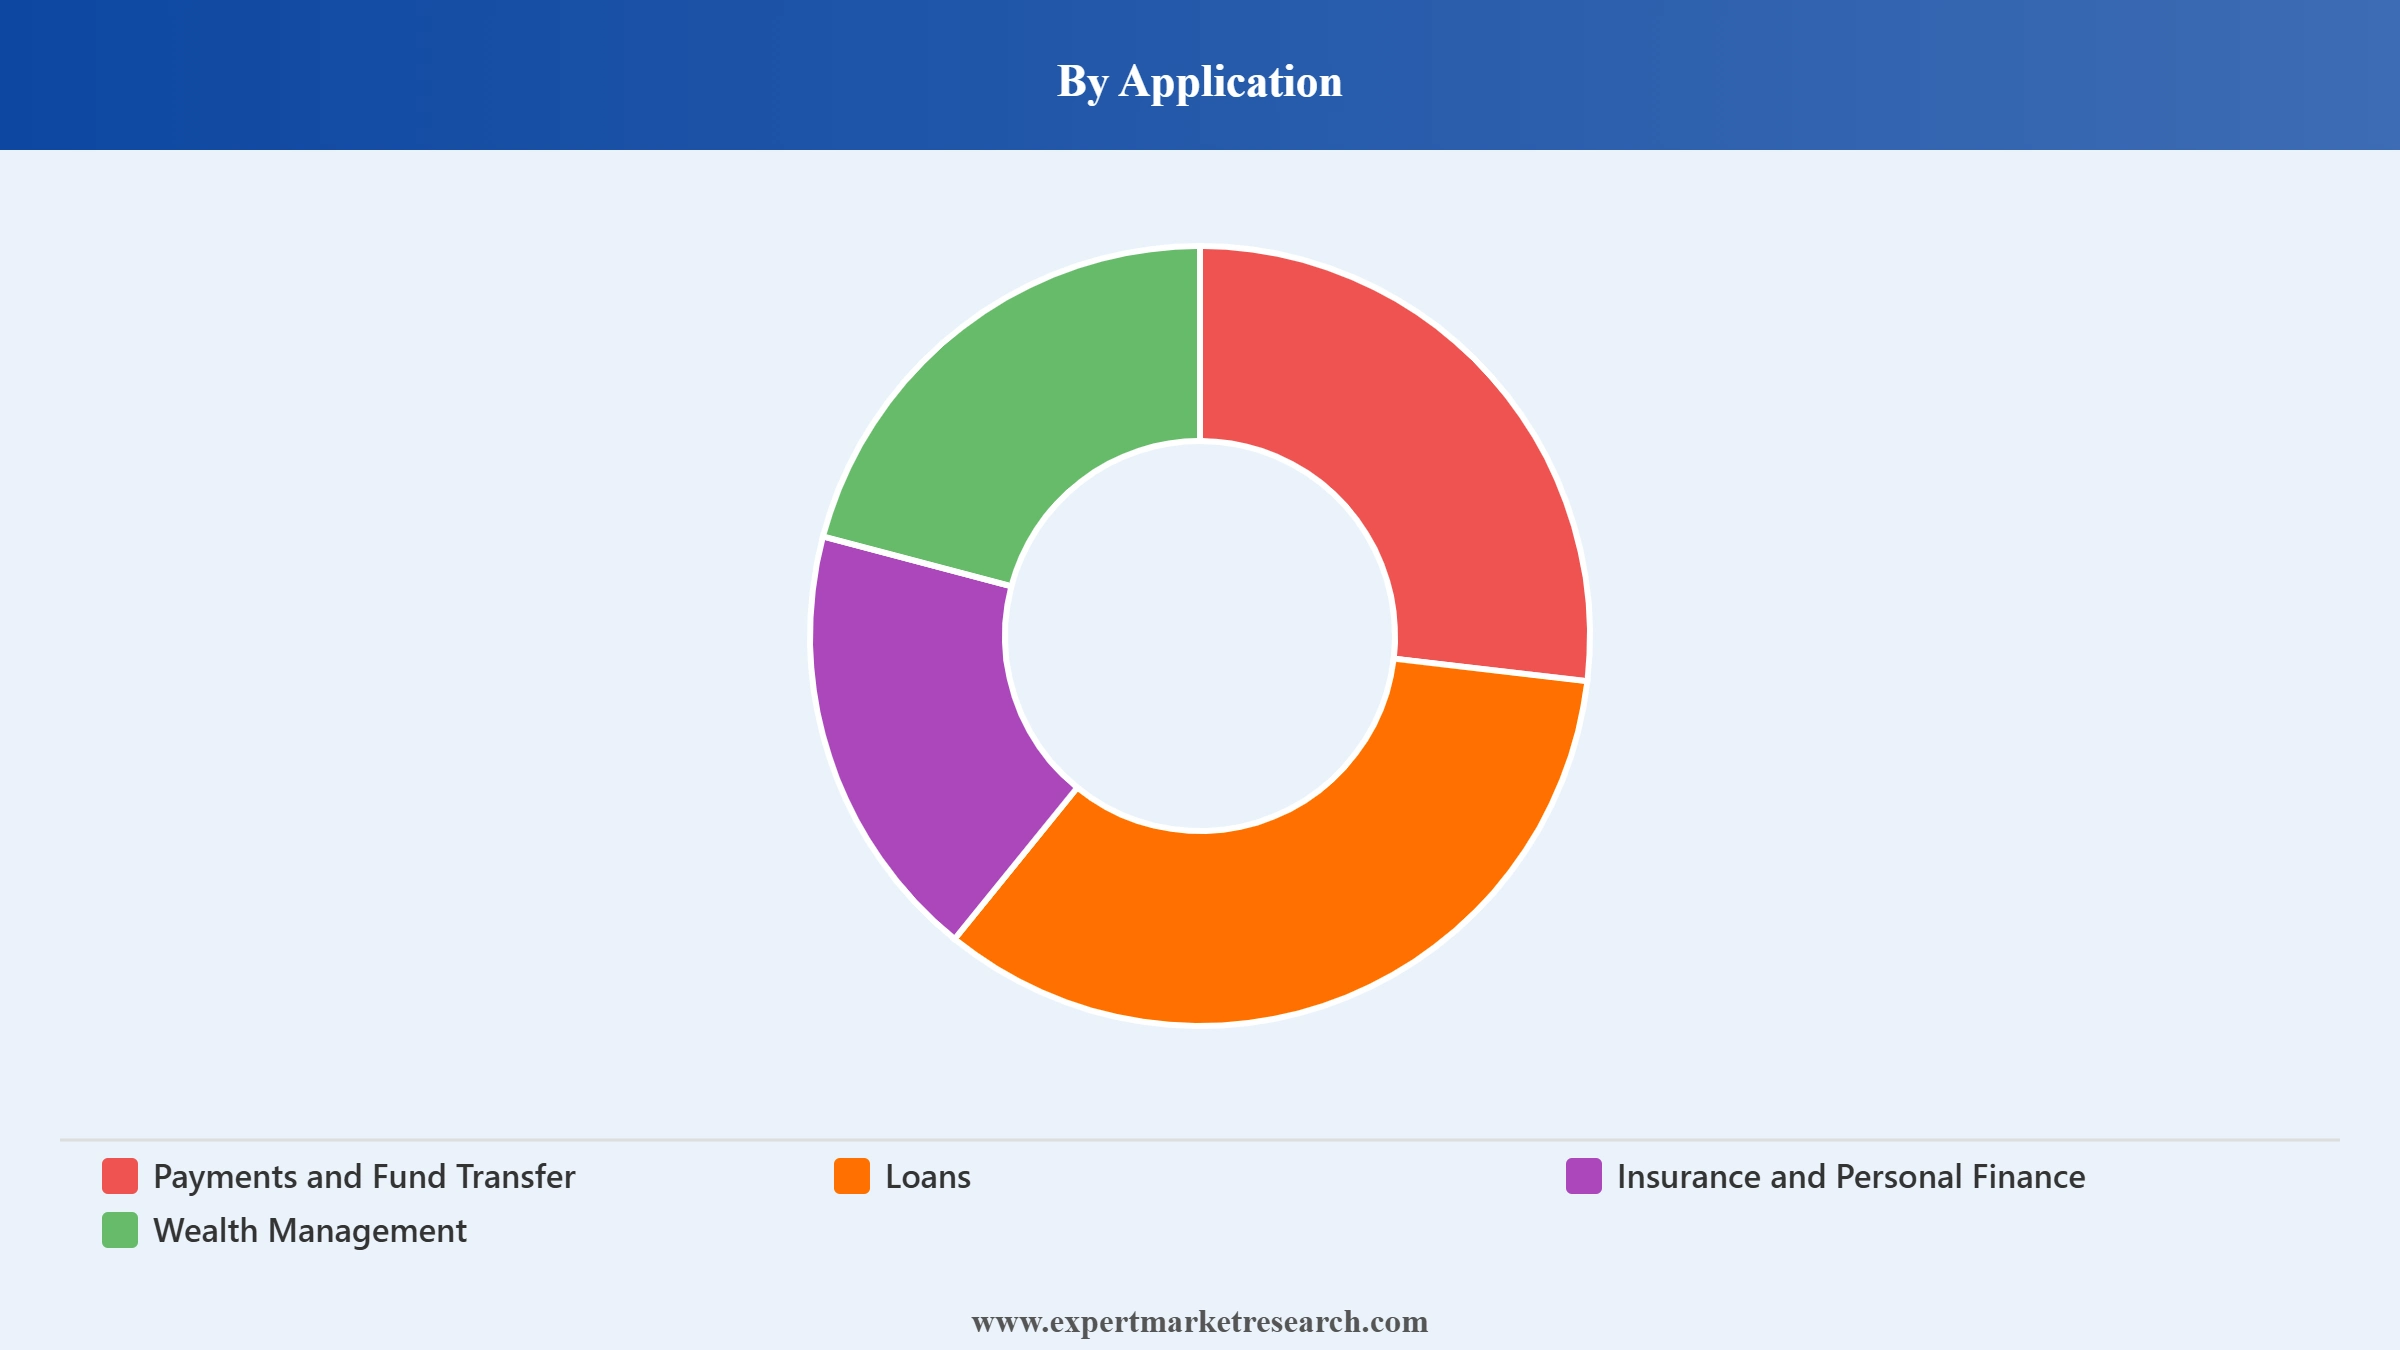
Key Insight: Payments and Fund Transfer: Payments and fund transfer hold the largest application share in the Australia fintech market, driven by rising adoption of real time payment rails and digital wallets across everyday consumer and business transactions. Loans: Digital and alternative lending platforms continue to expand SME and consumer credit access outside traditional bank channels. Insurance and Personal Finance: Insurtech and budgeting tools are gaining traction among younger, digitally native consumers. Wealth Management: Robo-advisory platforms are growing quickly as retail investors seek low-cost portfolio management, illustrated by Singapore based Syfe's April 2025 acquisition of Australian trading platform Selfwealth for 65 million Australian dollars. Others: Regtech and other specialised applications continue to serve niche compliance and risk functions.
Market Breakup by Region
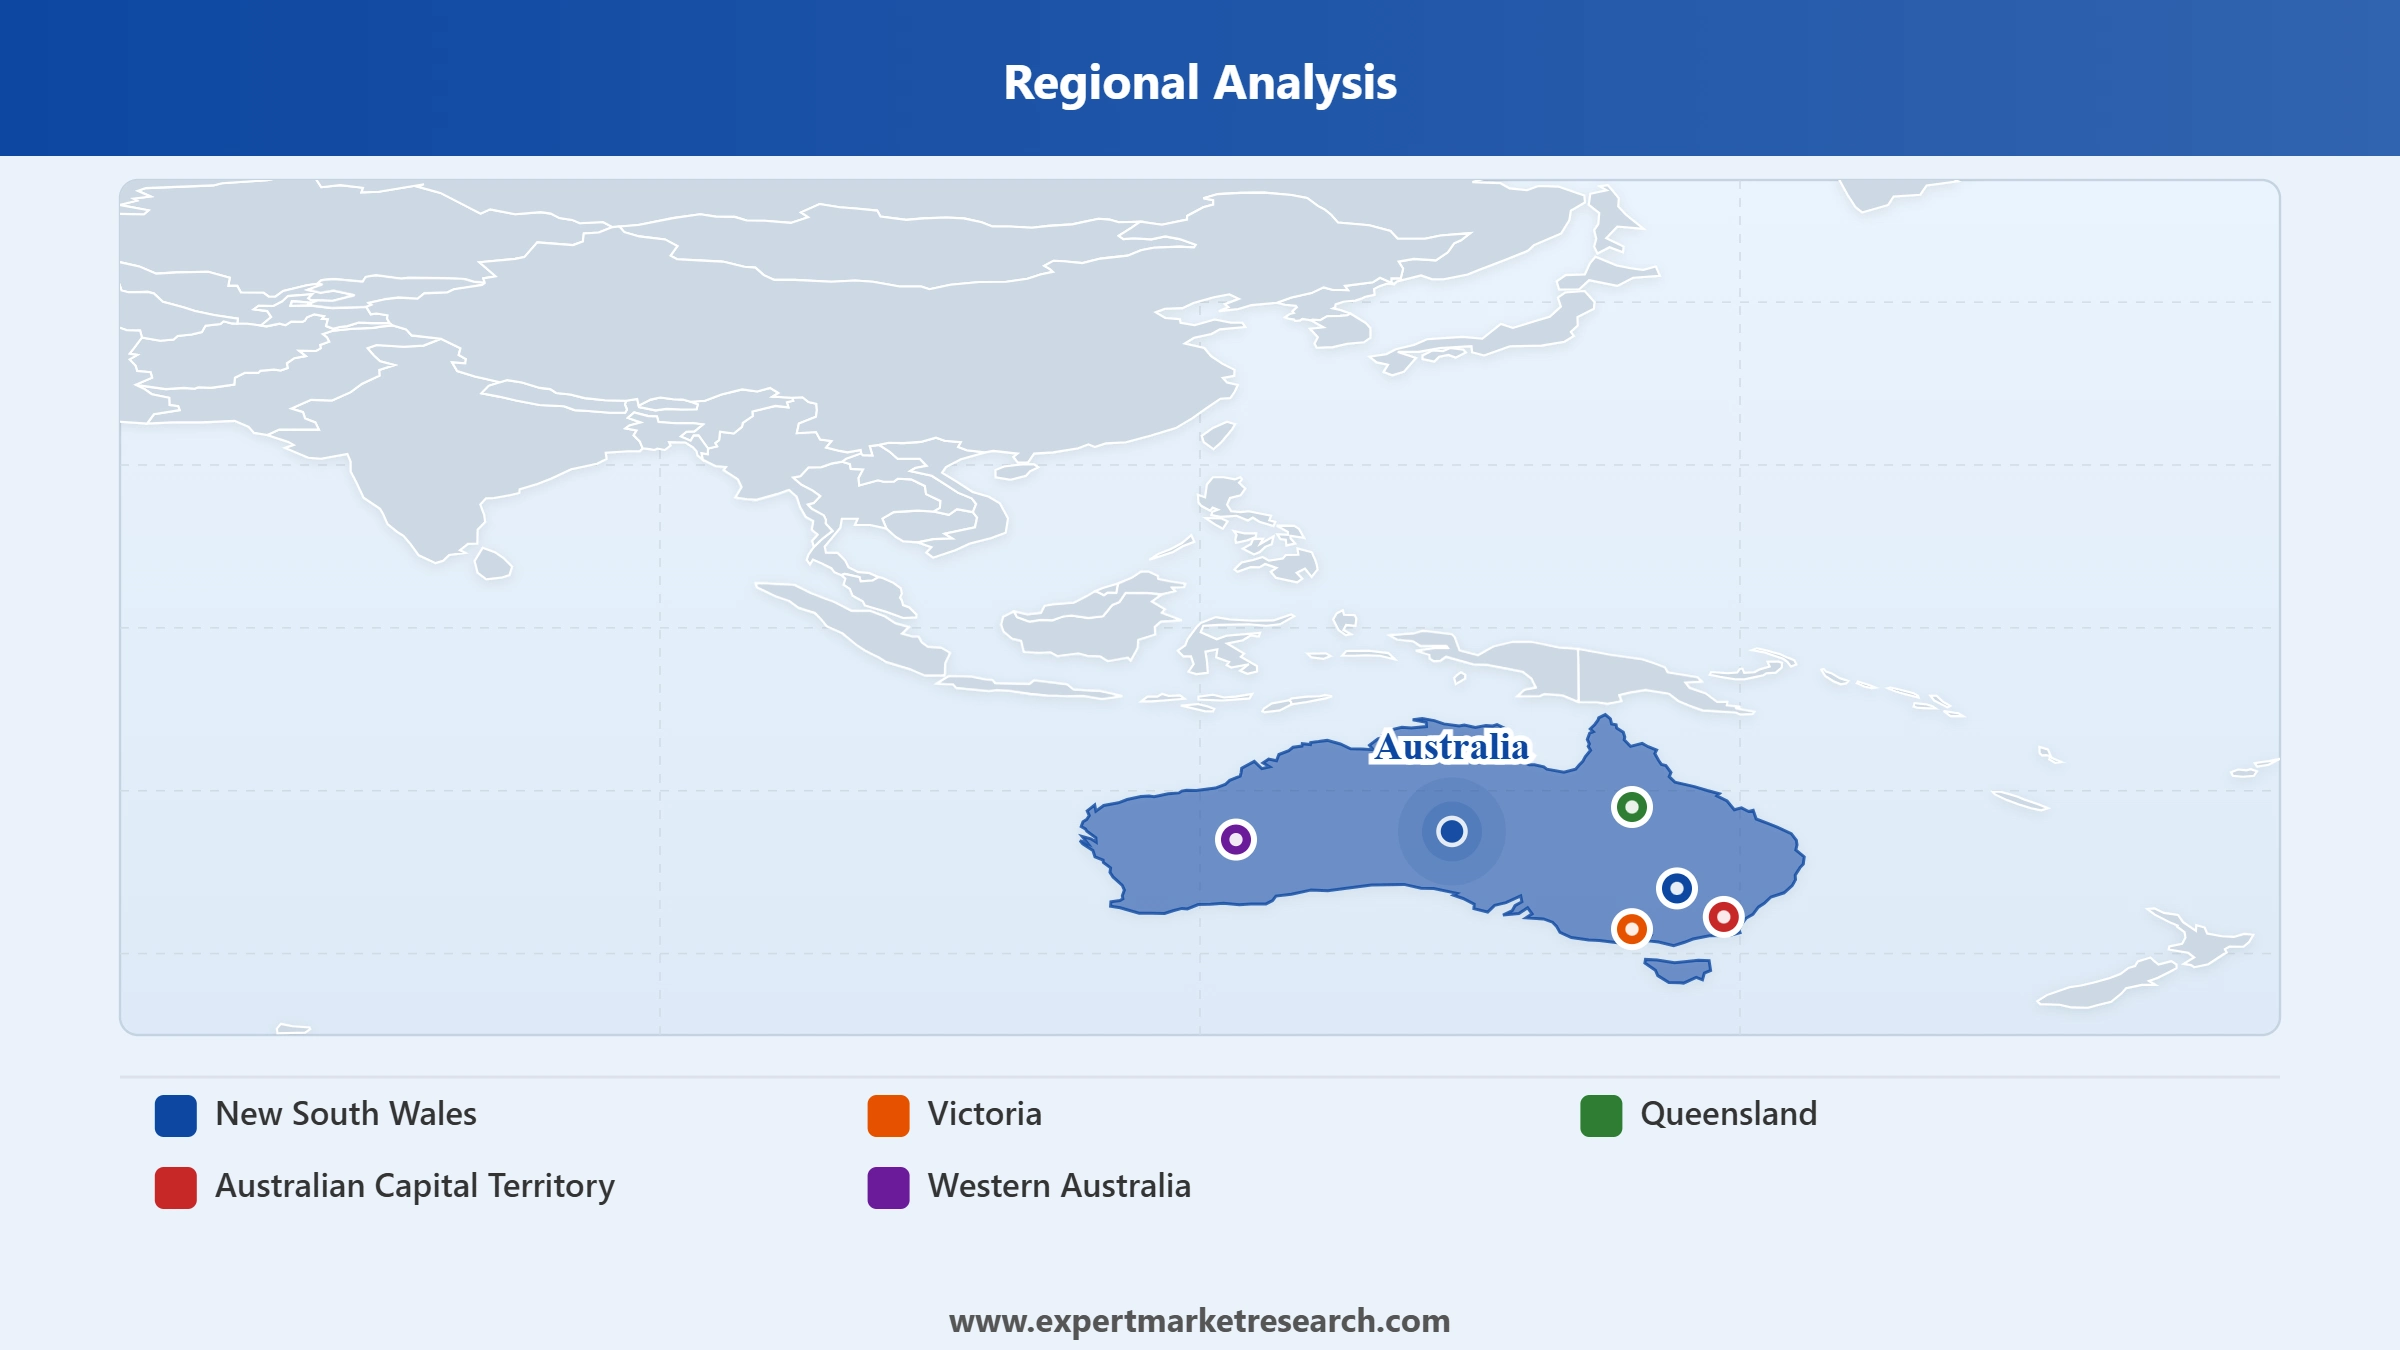
Key Insight: New South Wales: New South Wales leads the Australia fintech market, anchored by Sydney's concentration of licensed banking institutions, venture capital firms, and fintech headquarters. Victoria: Victoria is registering the fastest growth, supported by Melbourne's dense payments and merchant services startup cluster. Queensland: Queensland continues to build a growing fintech presence linked to its broader technology sector expansion. Australian Capital Territory: The Australian Capital Territory benefits from proximity to financial regulators and government digital initiatives. Western Australia: Western Australia and other states and territories contribute smaller but steadily growing shares supported by regional financial inclusion programmes.
By deployment mode, cloud dominates the market through scalability and lower upfront infrastructure costs
Cloud accounts for the largest deployment mode share of the Australia fintech market, offering scalability, cost efficiency, and rapid deployment that allow fintech companies to adjust resources based on demand without upfront hardware expenses across regions and markets. In January 2026, Airwallex acquired South Korean payment processor Paynuri, securing licensed payment gateway and foreign exchange registrations to operate its cloud-based platform directly in South Korea and beyond, extending its licensed footprint further across Asia.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
On-premises deployment continues to serve regulated institutions requiring direct infrastructure control, though its share is gradually narrowing as more Australia fintech companies migrate core systems to cloud environments internationally across sectors and industries alike. Established challenger banks and payment providers continue to favour cloud native infrastructure for new deposit and lending product launches across the sector and broader market, reflecting shifting technology preferences among institutions and their customers.
By technology, artificial intelligence dominates the market through expanding adoption in underwriting and fraud detection
Artificial intelligence accounts for the largest technology share of the Australia fintech market, as banks and lenders increasingly deploy machine learning models for credit risk assessment, fraud detection, and personalised financial advice. In April 2026, Commonwealth Bank deployed an agentic AI system to detect emerging fraud and scam patterns across transaction data, contributing to a fraud loss reduction of more than 20 percent year on year across its network and customer base.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Application Programming Interface technology is growing quickly as open banking under the Consumer Data Right expands the range of data that banks must securely share with accredited third-party providers nationwide across the broader sector. In July 2026, product data sharing obligations under the Consumer Data Right commenced for non-bank lenders and buy now pay later providers, extending open banking style API access across a broader range of Australia fintech companies and platforms nationally and beyond.
By application, payments and fund transfer dominates the market through rising real time payment rail adoption
Payments and fund transfer accounts for the largest application share of the Australia fintech market, driven by rising adoption of the New Payments Platform and digital wallets across everyday consumer and business transactions across segments and markets. In April 2026, Zip Co launched ZMobile, a capital light mobile phone offering developed in partnership with TPG Telecom, extending its payments platform into telecommunications services and adjacent categories nationally and further afield.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Loans are growing quickly as digital and alternative lending platforms expand SME and consumer credit access outside traditional bank channels, offering faster approval times and more flexible product structures than conventional bank lending across segments and channels. In January 2026, Plenti surpassed a 3-billion-dollar loan portfolio milestone, with its NAB powered by Plenti car loan product driving accelerated quarterly origination growth and record originations nationally and further.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
New South Wales dominates the market through its concentration of licensed banking institutions and venture capital activity
New South Wales leads the Australia fintech market, holding a significant share of over 45 percent in 2025, anchored by Sydney's concentration of licensed banking institutions, venture capital firms, and fintech headquarters across sectors. In May 2026, the NSW Government co-hosted the Citi A50 Forum in Sydney, promoting the city's role as a regional financial hub and seeking to unlock global capital into critical sectors across the state and region and economy.
Victoria is registering the fastest growth as Melbourne's dense payments and merchant services startup cluster continues to attract new fintech headquarters and funding activity internationally across sectors and industries alike. In April 2026, Zeller launched its operations in the United Kingdom, establishing an office in Holborn, London, extending the Melbourne headquartered company's payments platform beyond its Australian home market and broader customer base overseas and further.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The Australia fintech companies are becoming increasingly competitive as major Australia fintech companies invest in embedded finance, artificial intelligence, and cross border payment capabilities to differentiate their portfolios across payments, lending, and banking categories. Companies are prioritising cloud native architecture, open banking integration, and low-cost merchant hardware to appeal to small business customers and financial institutions seeking modern, flexible technology partners. Established Australia fintech companies are also deepening partnerships with major retailers, telecommunications providers, and banks to embed their services within everyday consumer and business touchpoints, while investing heavily in fraud detection and compliance capabilities to strengthen customer trust.
Major Australia fintech market players are also focusing on large scale funding rounds and international expansion to capture growing demand across payments, lending, and property technology categories. Strategic emphasis on regulatory compliance and licensing is allowing established companies to capture market share as new credit and anti-money laundering requirements reshape competitive dynamics across the sector. The market players continue to pursue acquisitions and overseas market entry, particularly across Asia Pacific and Europe, to diversify revenue beyond domestic operations, while smaller challenger brands compete on pricing, hardware design, and customer service to win merchant accounts from established incumbents.
Founded in 2015 and headquartered in Melbourne, Australia, with dual global headquarters in Singapore and San Francisco, Airwallex is a multinational financial technology company providing global payments and banking infrastructure for businesses, and a leading name in the market. Its platform enables multi-currency accounts, international transfers, corporate cards, and embedded finance, serving more than 200,000 businesses across over 180 countries including Brex, Rippling, and Canva.
Founded in January 2020 and headquartered in Melbourne, Australia, Zeller is a financial services and digital payments company within the market, providing point of sale terminals, transaction accounts, and expense management tools for small and medium sized enterprises. The company's product range includes EFTPOS terminals, virtual terminals, invoicing, and corporate cards, serving thousands of Australian merchants across hospitality and retail sectors.
Founded in October 2016 and headquartered in Melbourne, Australia, Judo Bank is an authorised deposit taking institution and neobank focused on small and medium sized enterprise lending within the market, alongside personal term deposit products. The bank's loan book reached 14.7 billion dollars by June 2026, and it became the first commercial bank in three decades to list on the Australian Securities Exchange.
Founded in 2015 and headquartered in Melbourne, Australia, PEXA operates a digital property exchange platform that facilitates electronic settlement, lodgement, and fund transfer for real estate transactions, a notable presence within the market. The company holds a near monopoly position in Australian eConveyancing and has expanded into the United Kingdom, partnering with major lenders including NatWest on remortgage and property purchase workflows.
Other key players in the market include PTRN Pty Ltd., Zip Co. Limited, Athena Mortgage Pty Ltd., mx51 Group Pty Ltd., Afterpay Australia Pty Ltd., and Wise Australia Pty Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our Australia fintech market trends 2026 report. Discover regional growth patterns, deployment mode and application economics, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market is projected to grow at a CAGR of 9.10% between 2026 and 2035.
The market is categorised according to deployment mode, which includes on-premises and cloud.
The key players in the market include Airwallex Pty Ltd., Zeller Holdings Pty Ltd., PTRN Pty Ltd., Judo Bank Pty Ltd., Zip Co. Limited, Athena Mortgage Pty Ltd., Property Exchange Australia Ltd. (PEXA), mx51 Group Pty Ltd., Afterpay Australia Pty Ltd., and Wise Australia Pty Ltd., among others.
Based on the technology, the market is divided into artificial intelligence, application programming interface (API), robotic process automation, data analytics, and others.
The market is broken down into New South Wales, Victoria, Queensland, Australian Capital Territory, Western Australia, and others.
In 2025, the market reached an approximate value of USD 4.82 Billion.
The market is projected to witness healthy expansion and attain approximately USD 11.52 Billion by 2035.
New South Wales dominates the market, holding a significant share supported by its concentration of licensed banking institutions and venture capital activity.
Payments and fund transfer hold the largest application share, driven by rising adoption of real time payment rails and digital wallets.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Deployment Mode |
|
| Breakup by Technology |
|
| Breakup by Application |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




