

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
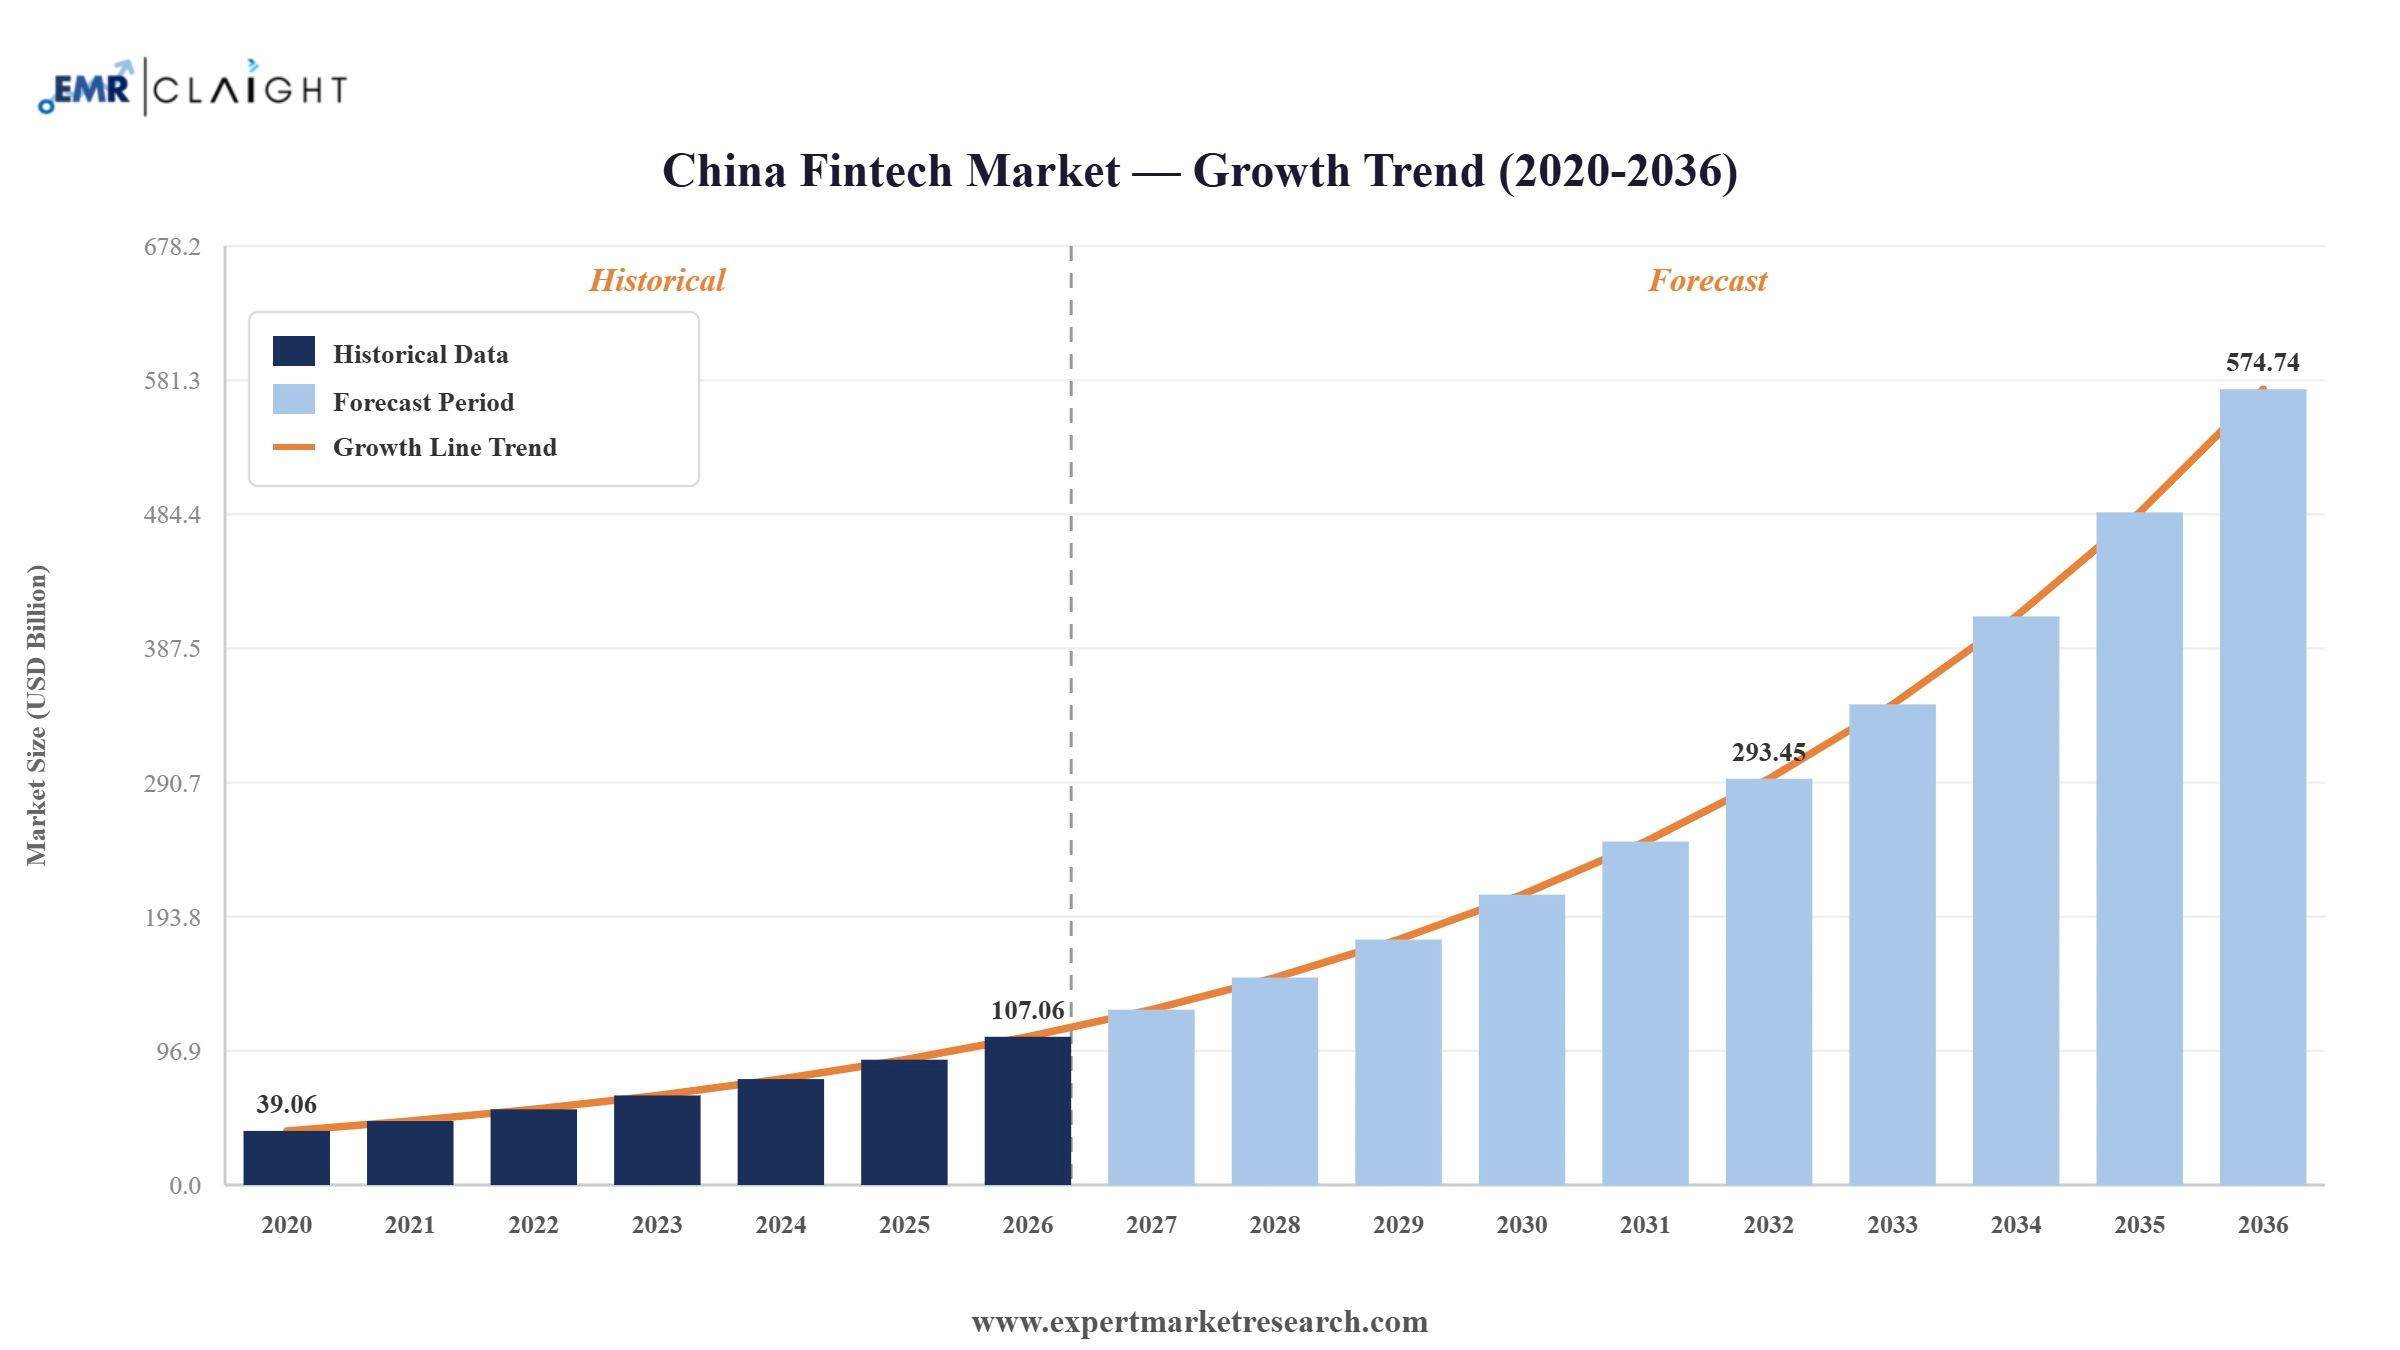
The China fintech market was valued at USD 90.50 Billion in 2025 and is projected to grow at a CAGR of 18.30% through 2035. The market is expected to reach USD 485.84 Billion by 2035. Rapid adoption of digital payments, expanding cross border financial technology partnerships, and rising sophistication of artificial intelligence powered risk assessment tools are driving overall growth in the market, with mobile super apps and cloud native banking platforms reshaping how consumers and businesses access financial services nationwide.
The China fintech market encompasses digital payments, alternative lending, digital banking, wealth management, and insurtech solutions delivered through both on premises and cloud-based deployment models. Demand continues to be shaped by high smartphone penetration, favourable regulatory frameworks, and a maturing digital finance ecosystem, with cloud accounting for the largest deployment share given the scalability and lower upfront costs it offers to establish China fintech companies nationwide.
Established China fintech companies are increasingly securing new international regulatory approvals to expand payment infrastructure beyond domestic borders, reflecting strong investor confidence in the sector's growth trajectory. In January 2026, Airwallex announced plans to invest approximately 200 million euros over five years in the Netherlands, including a 60 percent increase to its Amsterdam headcount, as the company shifts strategic focus toward Europe and the Americas.
The China fintech market companies are increasingly directing growth capital toward overseas capital raising and cross border technology partnerships rather than concentrating solely on domestic payment rails, reflecting a strategic shift toward building durable, multi market revenue bases as domestic competition intensifies. Companies are pursuing parallel investment across insurance technology, wealth management, and cross border payment interoperability rather than remaining narrowly focused on a single vertical, while strengthening partnerships between banks, insurers, and global wallet networks to accelerate customer acquisition. In July 2025, ZhongAn completed a placement of 215 million new H shares, with proceeds earmarked for overseas expansion and technology research and development.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Tencent announced a collaboration between its TenPay Global cross border payment platform and PayPal World, enabling United States based PayPal users to complete payments at Weixin Pay merchants in China by scanning QR codes, alongside a 90-day fee waiver for cardholders. Companies across the China fintech market can leverage global wallet interoperability partnerships to capture inbound visitor spending without requiring new app downloads.
Futu Securities renamed its Hong Kong digital banking subsidiary Airstar Bank to Ele Bank, following a further capital injection that increased its ownership stake to a controlling 68.43 percent across the platform and its business. Companies across the China fintech market can leverage controlling stake acquisitions in digital banking subsidiaries to integrate brokerage and banking services under a unified brand identity nationwide and beyond regions.
Lufax shareholders approved four 2026 framework agreements covering services and product purchasing, financial services, Ping An consumer finance collaboration, and account management, securing board authority to implement annual transaction caps for the coming year ahead of schedule nationwide. Companies across the China fintech market can leverage multiyear framework agreements with strategic partners to provide greater visibility over funding and operational arrangements nationwide and beyond.
OneConnect Financial Technology and PAObank were selected for the Hong Kong Monetary Authority's second Generative AI Sandbox to pilot an anti-fraud strategy platform using AI powered facial recognition and deepfake detection, reporting a 99 percent success rate against such threats. Companies can leverage regulatory sandbox participation to validate emerging fraud detection technology before commercial rollout nationwide and beyond.
Established brokerage and fintech groups across the China fintech market are increasingly consolidating ownership stakes in digital banking subsidiaries to integrate services under unified brand identities, rather than operating separately. This is helping groups cross sell banking products to existing brokerage customer bases and strengthen platform loyalty across trading and deposit accounts. In October 2025, the Global FinTech Hub Report 2025 confirmed that China accounts for 11 of the world's top 50 fintech hubs and five of the top 10, reinforcing consolidation around metropolitan centres.
Established consumer finance providers across the China fintech market are increasingly developing proprietary big data foundation models to process fragmented enterprise data, rather than relying solely on third party scoring systems, to improve credit assessment accuracy across portfolios and lending segments nationwide. This is helping providers distil operational intelligence from real world business practices and cause effect logic. In June 2025, Mashang Consumer Finance unveiled version 3.0 of Tianjing, its retail finance foundation big data model first launched in 2023, enhancing its processing capabilities.
Established technology as a service providers across the China fintech market serving the financial sector are increasingly attracting acquisition interest from strategic investors, rather than continuing as independently listed entities, as the sector consolidates around scale and operational efficiency nationwide and beyond. This is helping acquired providers access additional resources for platform investment and market expansion. In December 2025, OneConnect Financial Technology was acquired by Platinum Yuen, marking a strategic ownership change for the technology as a service provider and its operations.
Established consumer finance companies across the China fintech market are increasingly issuing asset backed securities denominated in digital currency, rather than conventional instruments alone, to demonstrate blockchain infrastructure readiness ahead of wider institutional adoption nationwide and beyond regions today. This is helping issuers establish early technical and regulatory precedents in digital currency capital markets. In August 2025, Mashang Consumer Finance issued China's first e-CNY credit asset backed securities by a consumer finance company, utilising blockchain technology for the transaction and settlement.
Established consumer lending platforms are increasingly redesigning pricing and risk models to comply with stricter interest rate caps, rather than continuing prior structures, as authorities move to shrink the loan sector. This is helping regulators reduce systemic risk while pressuring fintech intermediaries reliant on higher rate products. In March 2026, Chinese regulators enforced a sharp reduction in interest rate ceilings across the personal consumer loan sector, requiring lenders to lower the share of loans priced above four times the benchmark rate.
The Expert Market Research's report titled “China Fintech Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Deployment Mode
Key Insight: On-Premises: Legacy financial institutions and select regulated entities continue to rely on on-premises deployment for core systems requiring direct infrastructure control and data residency assurance. Cloud: Cloud dominates deployment mode given its scalability, lower upfront costs, and faster rollout of new products, a pattern confirmed across the China fintech market where cloud native platforms are increasingly the default choice for new entrants and incumbents alike, illustrated by WeBank Technology Services' January 2025 launch ceremony in Hong Kong marking its global expansion into digital infrastructure services.
Market Breakup by Technology
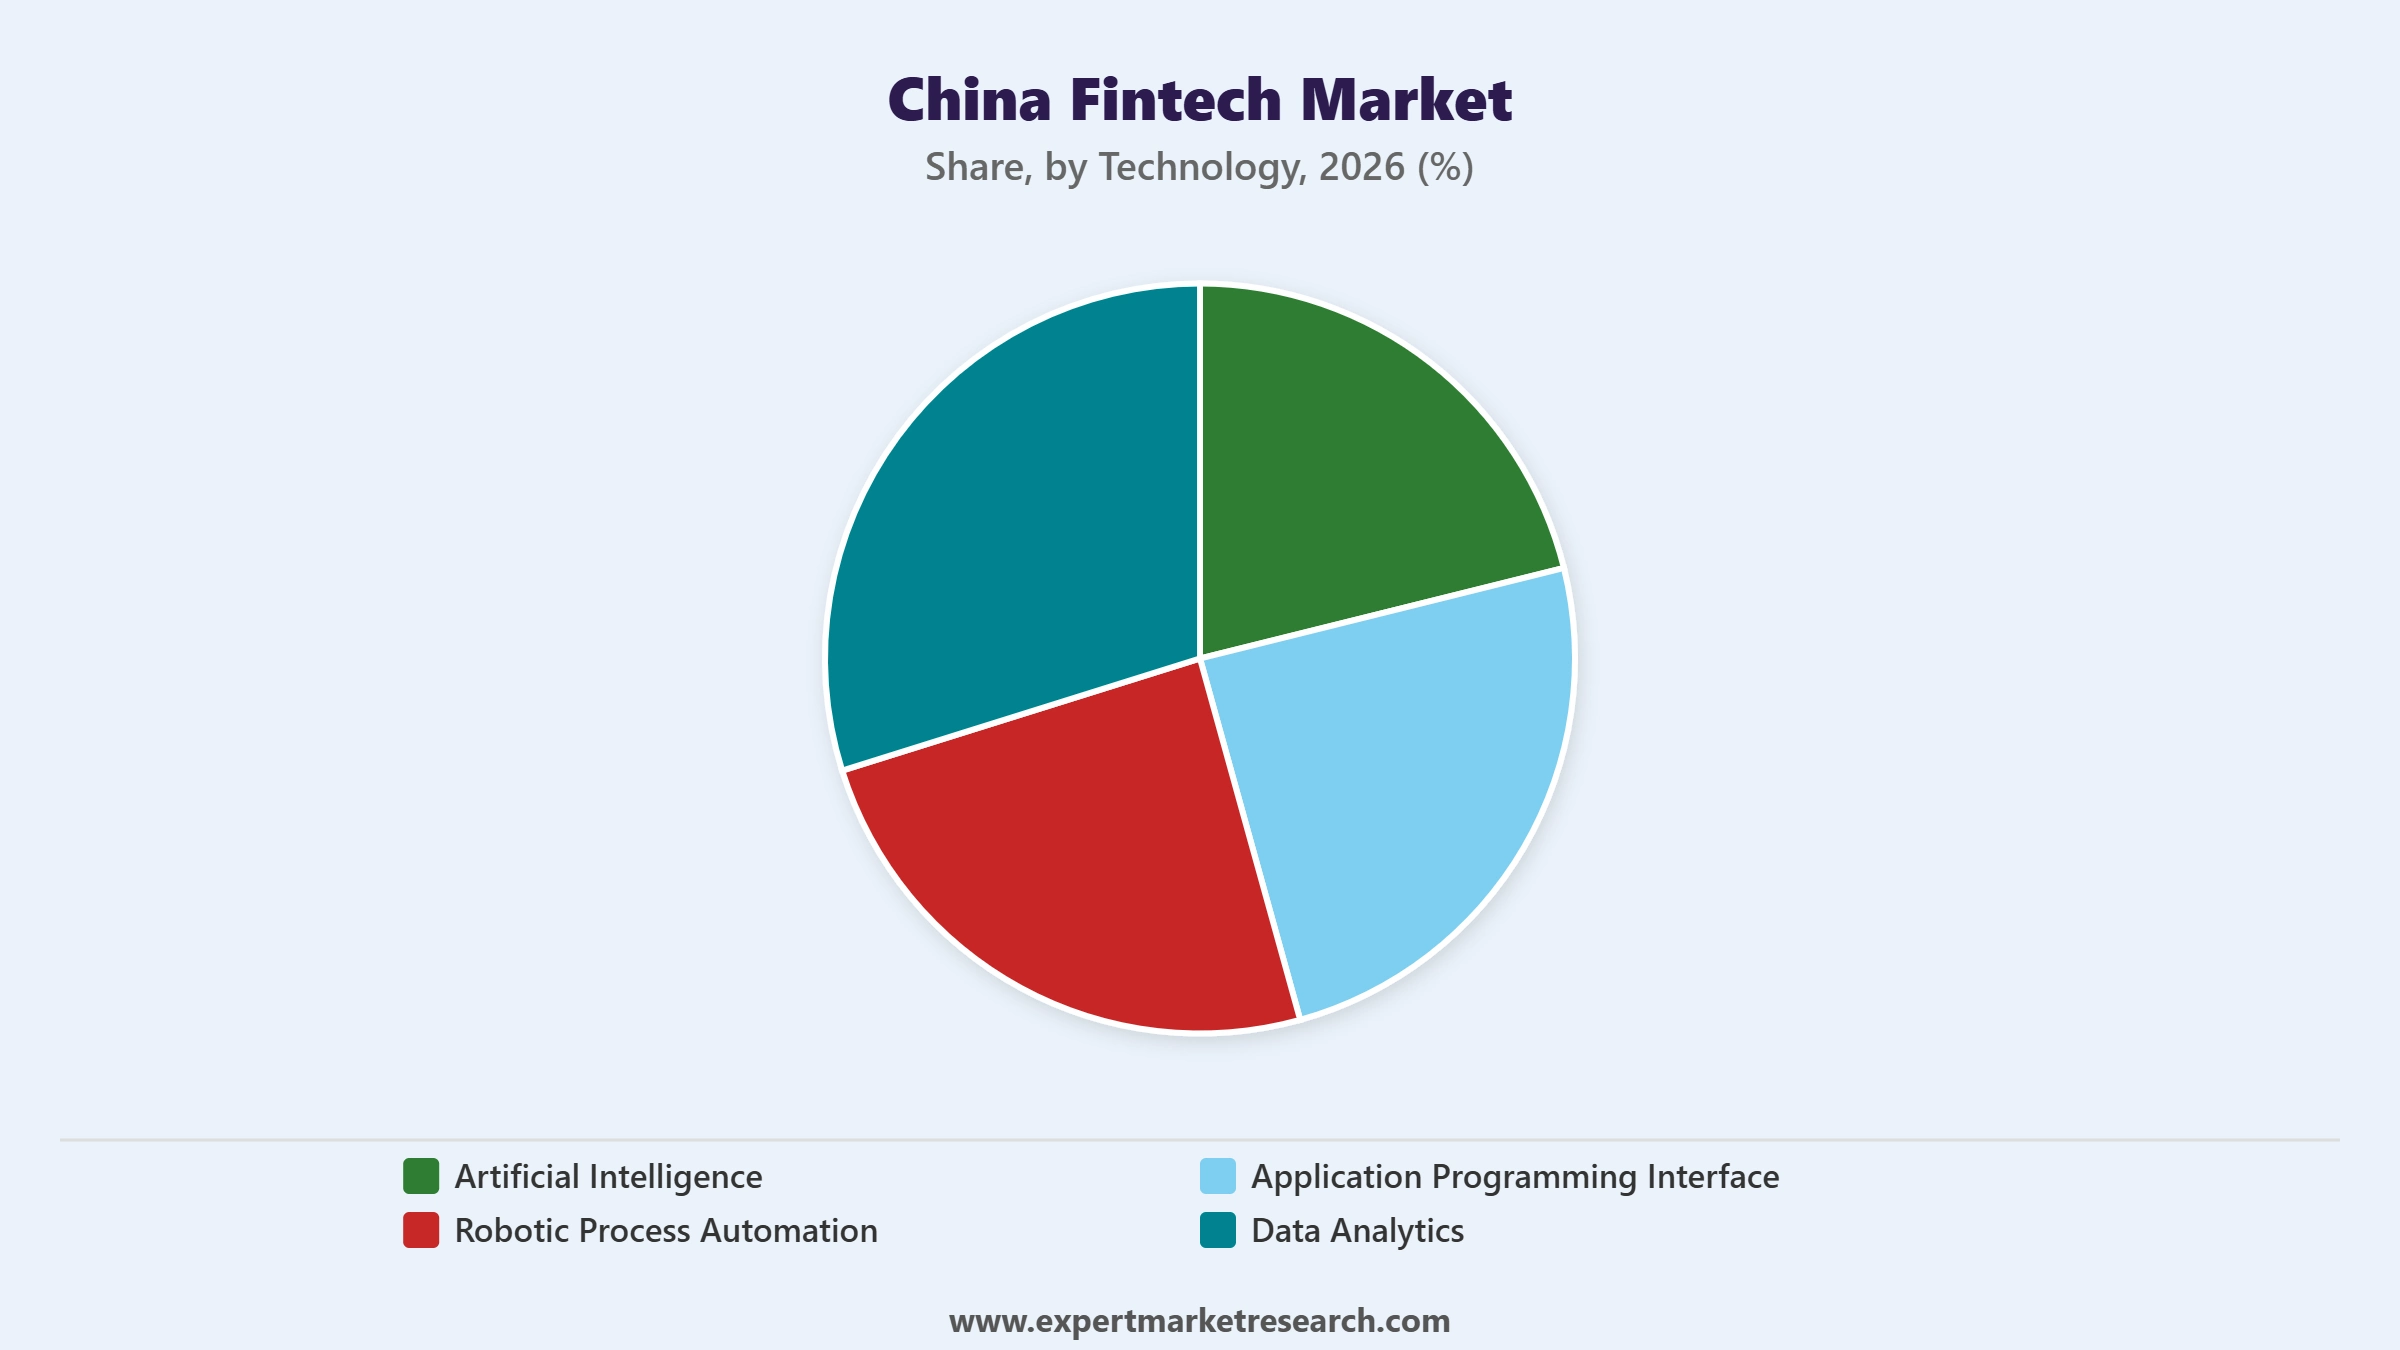
Key Insight: Artificial Intelligence: AI powered fraud detection, underwriting, and personalised financial advice are becoming standard features across lending and wealth management platforms nationwide, illustrated by WeBank's March 2026 recognition with four industry awards for advancing its AI native Bank strategy and inclusive finance capabilities. Application Programming Interface (API): Cross border payment APIs enable secure wallet interoperability between domestic and international financial institutions. Robotic Process Automation: RPA streamlines back-office reconciliation and compliance reporting tasks for banks and lenders. Data Analytics: Data analytics underpins credit risk scoring and customer segmentation across digital lending platforms nationwide. Others: Emerging technologies including blockchain and biometric authentication continue to see early-stage adoption.
Market Breakup by Application
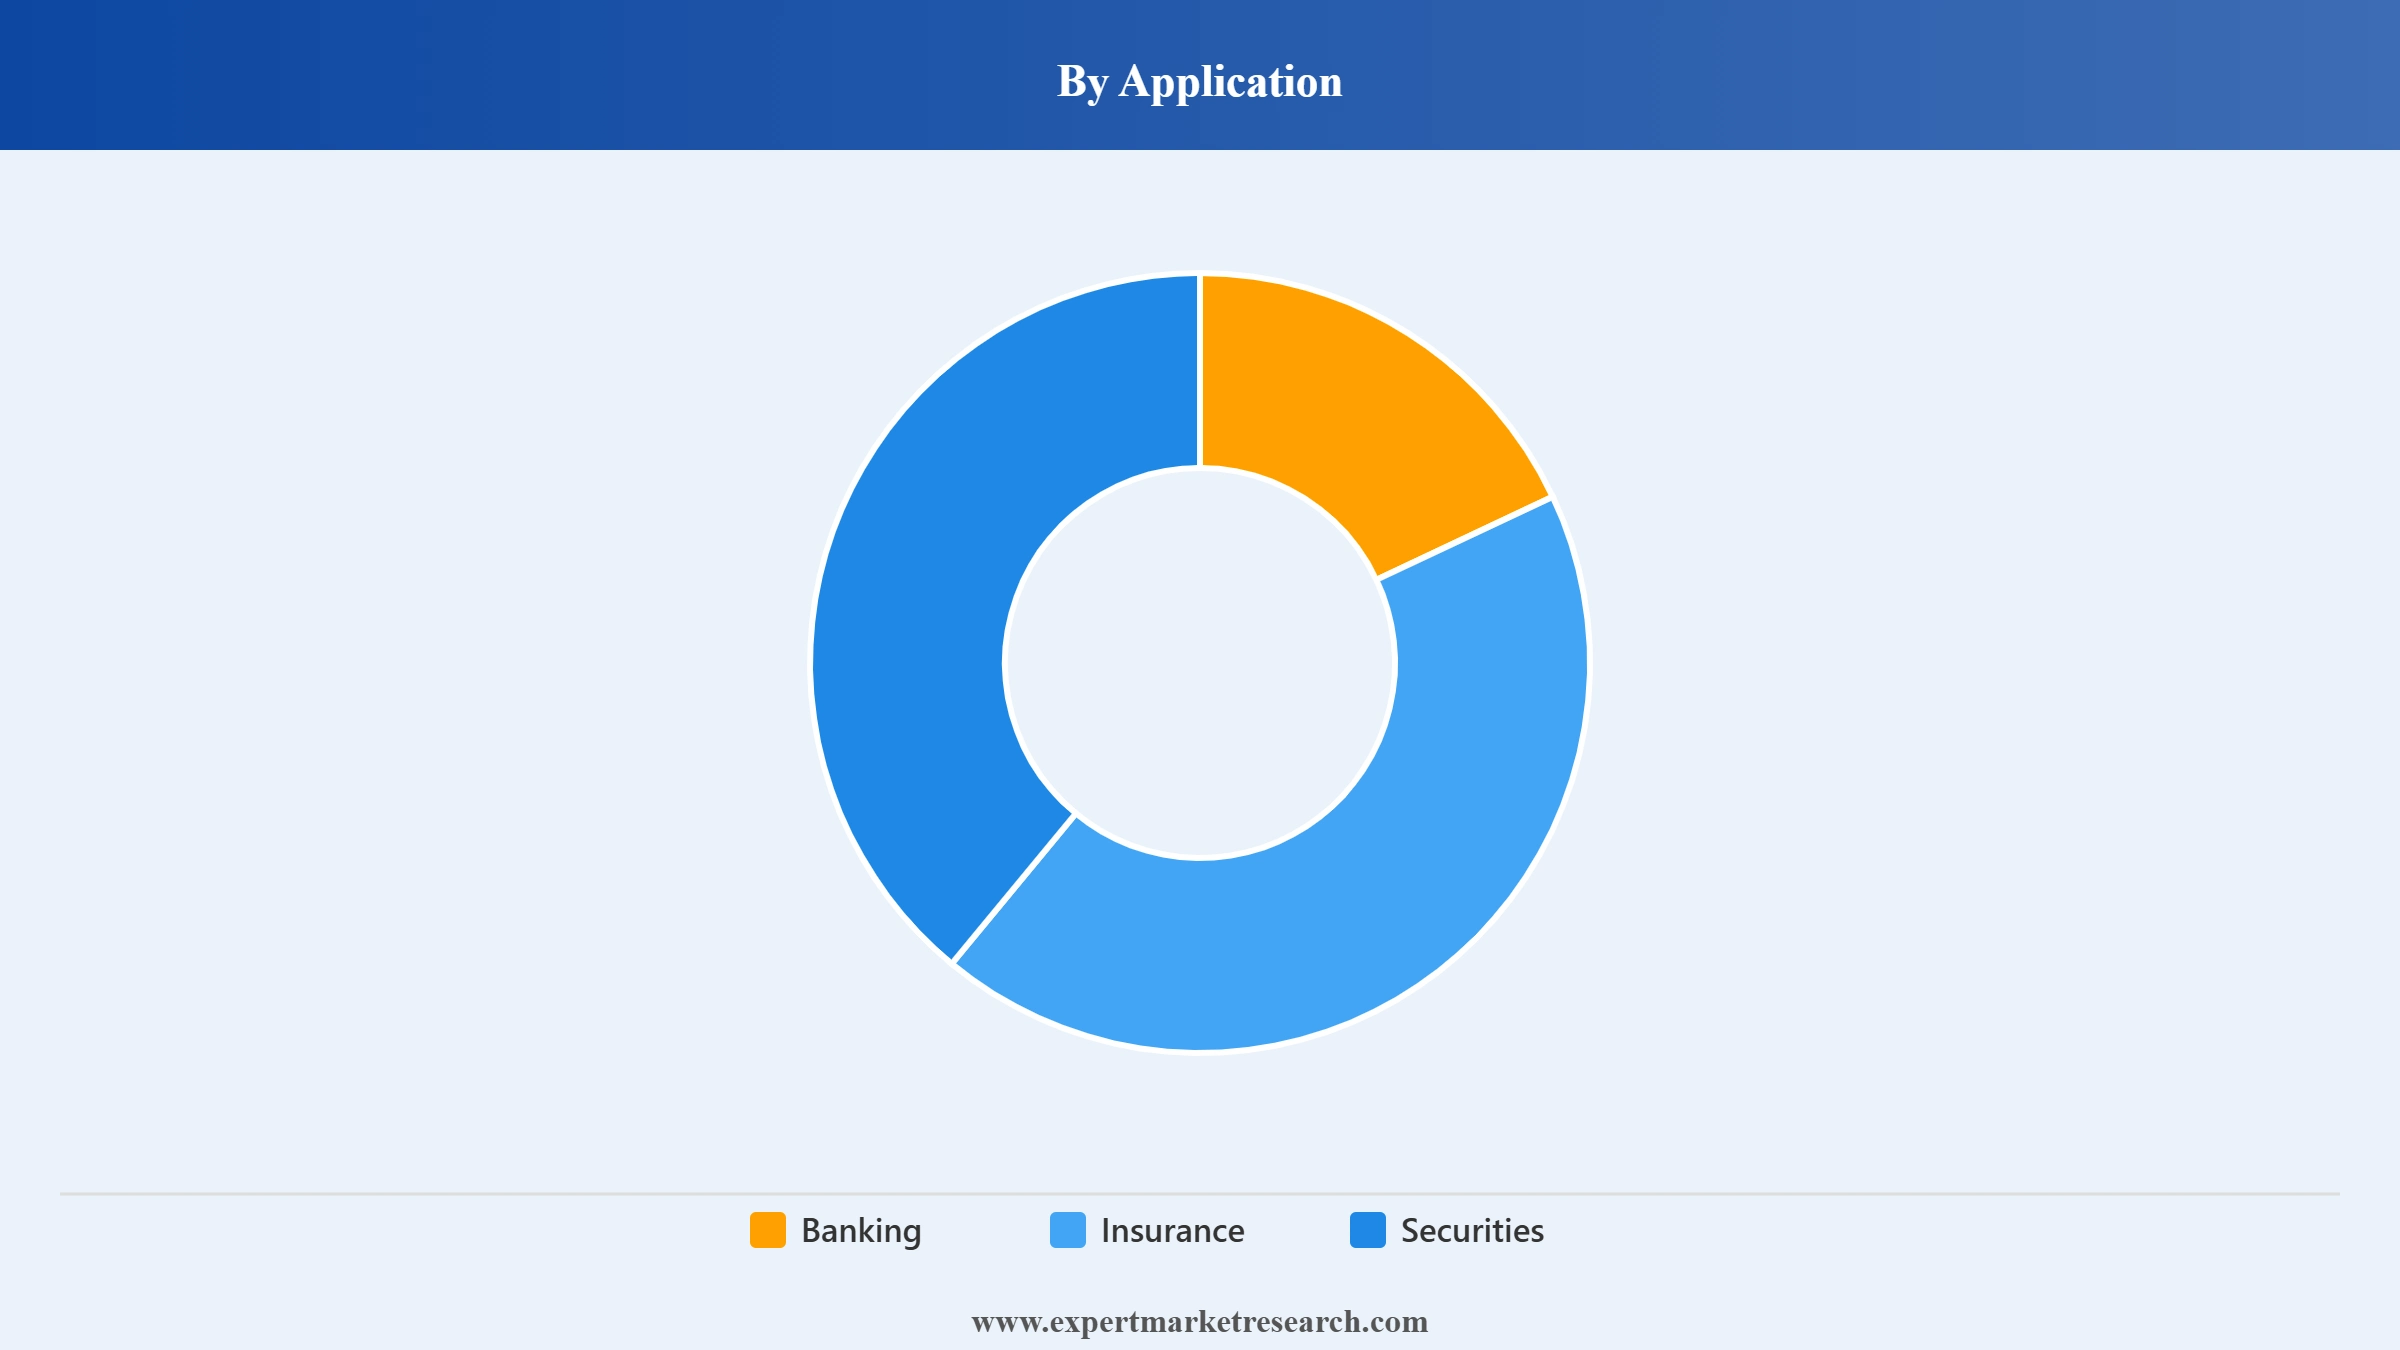
Key Insight: Banking: Banking holds the largest application share in the China fintech market, driven by rising adoption of digital lending platforms and mobile payment infrastructure across consumer and small business segments nationwide. Insurance: Insurtech platforms continue to expand automated underwriting and claims processing capabilities, illustrated by Ping An's March 2026 AI initiative using three decades of proprietary voice and visual data to power real time claims response, including automated accident detection and guidance. Securities: Digital brokerage and wealth management platforms are growing quickly as retail investors seek low-cost portfolio access across mobile trading applications. Others: Regtech and other specialised applications continue to serve niche compliance and risk functions.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
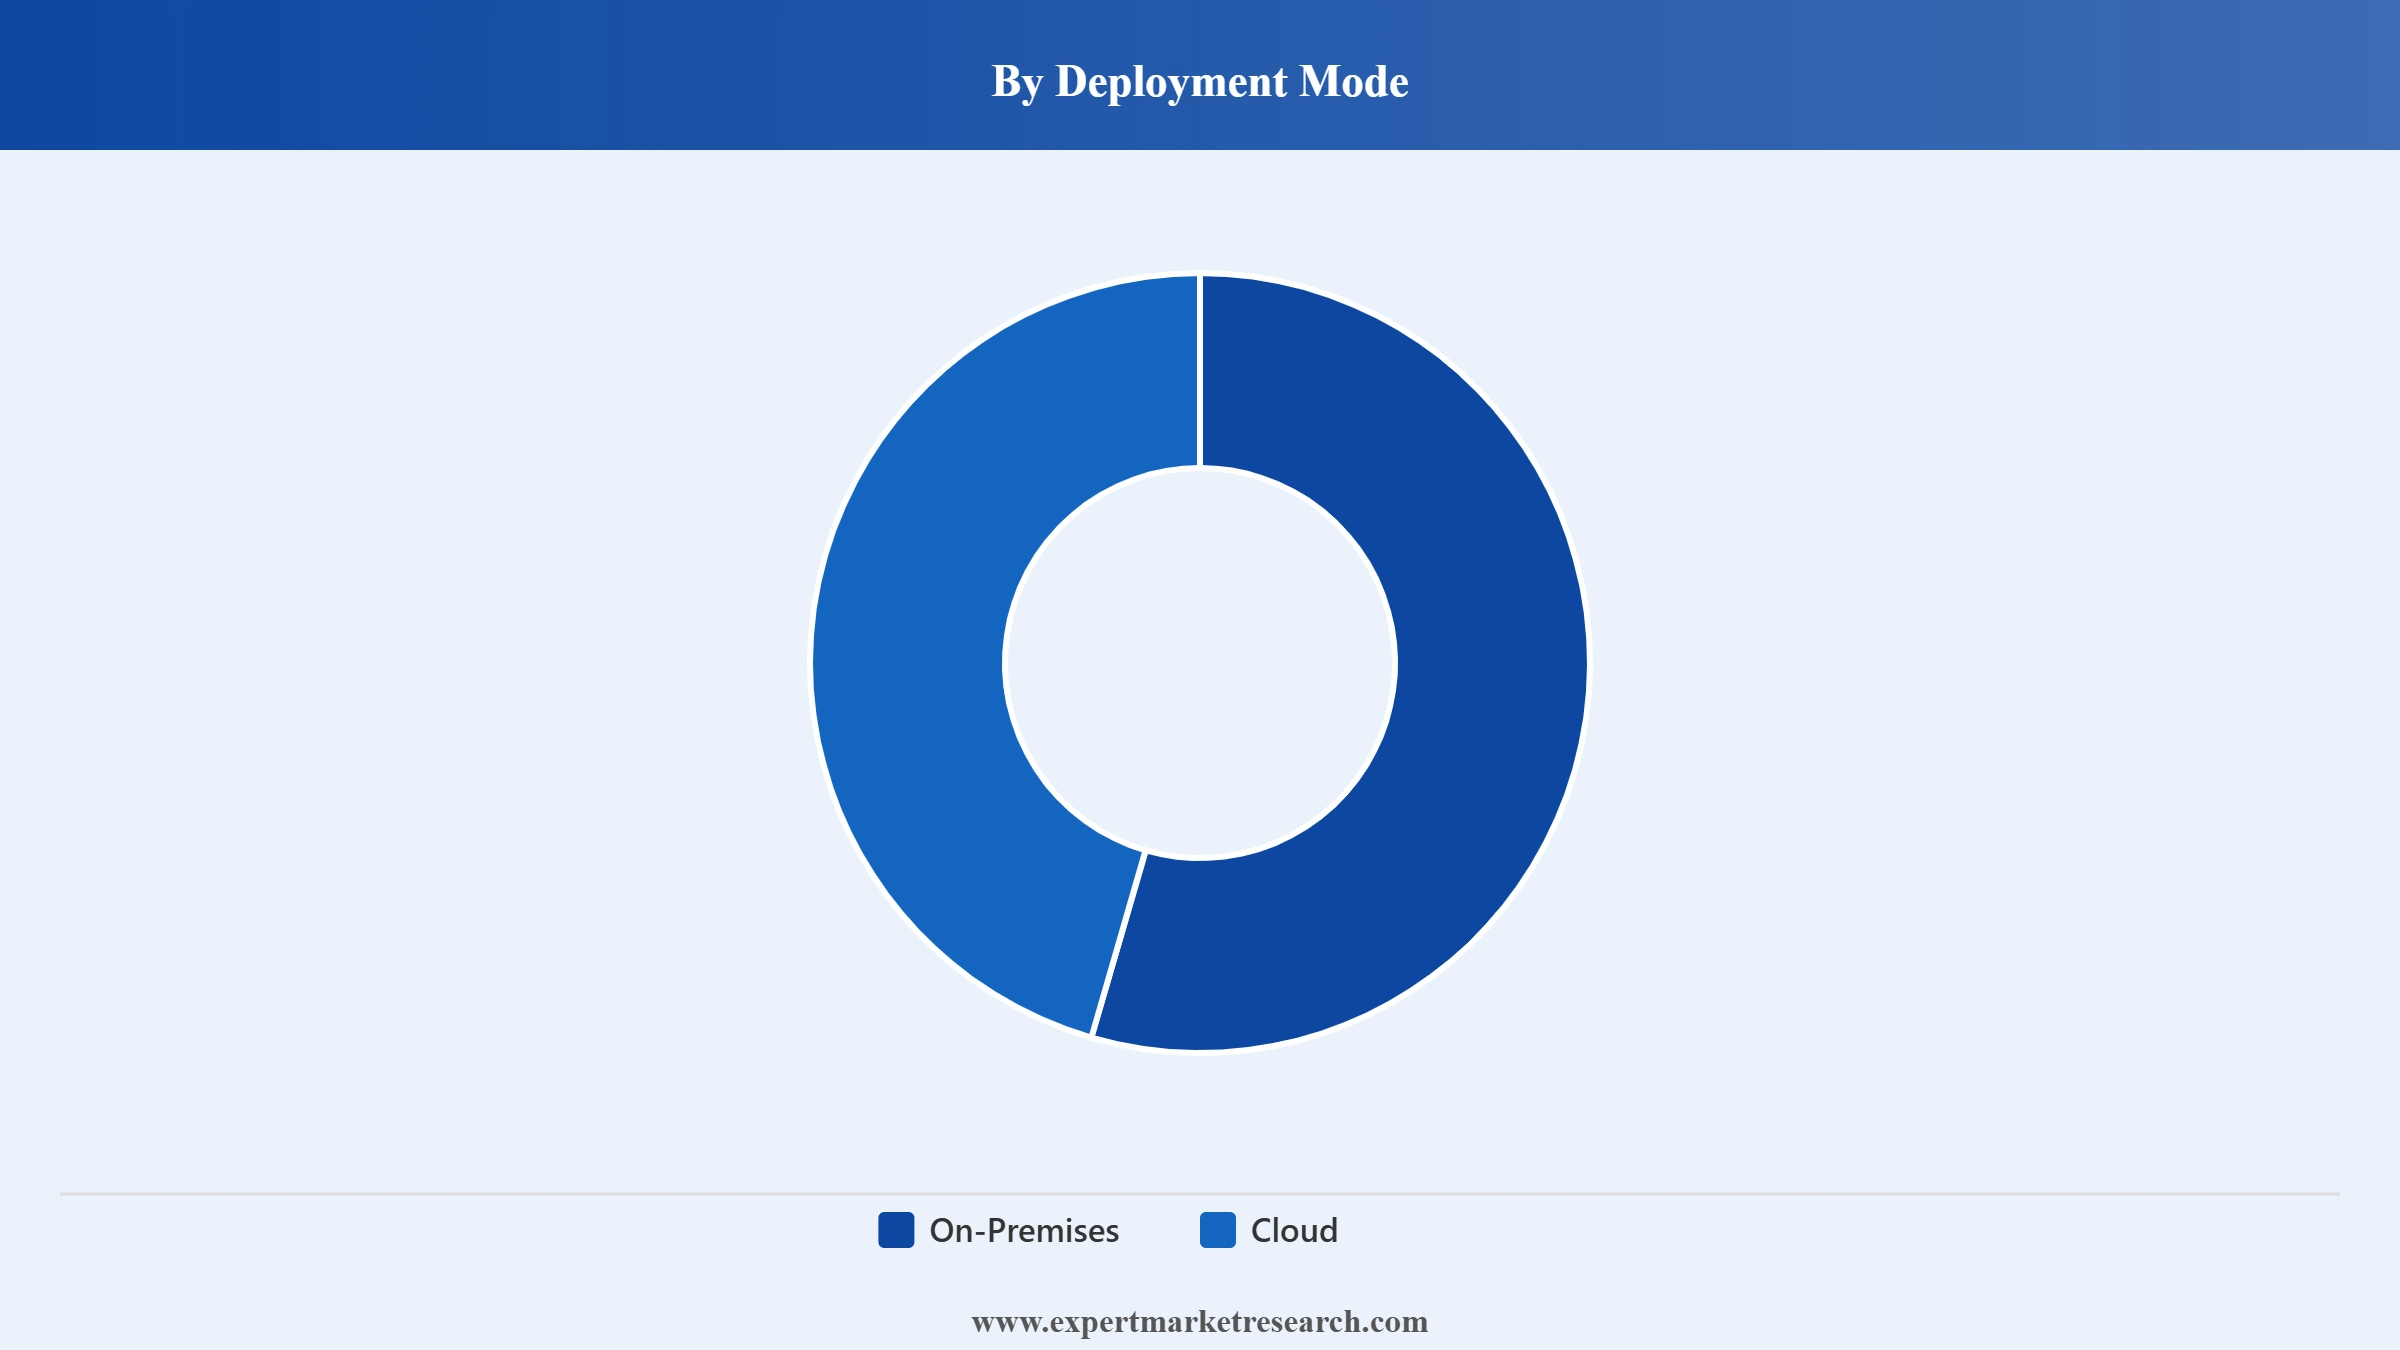
By deployment mode, cloud dominates the market through scalability and lower upfront infrastructure costs
Cloud accounts for the largest deployment mode share of the China fintech market, offering scalability, cost efficiency, and rapid deployment that allow fintech companies to adjust resources based on demand without upfront hardware expenses nationwide and beyond across regions. In February 2026, revised rules for China's cross border RMB payment system took effect, streamlining cloud-based settlement processes for banks and payment institutions operating across international corridors and networks worldwide and domestically, supporting faster transaction clearing and reduced operational overhead.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
On-premises deployment continues to serve regulated institutions requiring direct infrastructure control, though its share across the China fintech market is gradually narrowing as more China fintech companies migrate core systems to cloud environments nationwide and beyond across sectors and institutions. In February 2025, Fusion Bank completed a next generation core banking system upgrade with WeBank Technology Services and Tencent Cloud, replacing legacy infrastructure with a distributed architecture that halved new product development time and significantly reduced non-human IT costs over subsequent years.
By technology, artificial intelligence dominates the market through expanding adoption in underwriting and fraud detection
Artificial intelligence accounts for the largest technology share of the China fintech market, as banks and lenders increasingly deploy machine learning models for credit risk assessment, fraud detection, and personalised financial advice nationwide and beyond in scope. In May 2026, Alipay and parent Ant Group unveiled a full stack AI payments infrastructure featuring an AI Wallet and Token Pay service, introducing an Agentic Commerce Trust Protocol to oversee transactions executed by autonomous AI agents on behalf of users.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Application Programming Interface technology is growing quickly as cross border wallet interoperability expands the range of international payment networks connecting to domestic platforms nationwide and beyond in scope. In July 2025, the Payment and Clearing Association of China commenced trial operations of the Cross-Border Interconnection Payment Gateway, initially focused on enabling inbound payments by international visitors at mainland merchants through API based routing and settlement infrastructure nationally, with further expansion planned across additional corridors and international payment channels in coming months.
By application, banking dominates the market through rising digital lending and mobile payment adoption
Banking accounts for the largest application share of the China fintech market, driven by rising adoption of digital lending platforms and mobile payment infrastructure across consumer and small business segments nationwide and beyond across regions and markets. In June 2025, Bank of China launched its Cross-border E-Commerce Connect payment collection service, becoming the first major Chinese bank to introduce overseas payment collection for cross border e-commerce businesses operating from Singapore, a key regional financial hub for Southeast Asia.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Securities across the China fintech market are growing quickly as digital brokerage platforms expand banking services beyond core trading, reflecting rising demand for integrated financial services from younger, digitally native investors nationwide and beyond across markets. In June 2026, 26 financial institutions joined a new digital yuan cross border settlement platform, with banks operating in Brazil, Qatar, and Thailand among those connecting to streamline cross border securities and trade settlement processes across all participating jurisdictions and their respective financial institutions and regulators.
The China fintech companies are becoming increasingly competitive as major China fintech companies invest in artificial intelligence, cross border payment interoperability, and digital banking capabilities to differentiate their portfolios across payments, lending, and insurance categories. Companies are prioritising cloud native architecture, wallet network integration, and regulatory sandbox participation to appeal to financial institutions and regulators seeking modern, compliant technology partners. Established China fintech companies are also deepening loyalty and cross selling programmes, overseas licensing, and controlling stake acquisitions to strengthen customer retention, while investing in fraud detection and compliance technology to defend market share against rising domestic and international competitors.
Major China fintech market players are also focusing on overseas capital raising and cross border technology partnerships to capture growing demand across banking, insurance, and securities categories. Strategic emphasis on regulatory compliance and controlling stake consolidation is allowing established companies to capture market share as new lending caps and data protection requirements reshape competitive dynamics across the sector. The market players continue to pursue partnerships with global wallet networks and financial regulators, particularly across Europe, Southeast Asia, and Hong Kong, to diversify revenue beyond the domestic market while smaller specialised providers compete on niche compliance and risk management capabilities to retain institutional customers.
Founded in 2015 and headquartered in Melbourne, Australia, with dual global headquarters in Singapore and San Francisco, Airwallex is a multinational financial technology company and notable name in the market, providing global payments and banking infrastructure for businesses. Its platform enables multi-currency accounts, international transfers, corporate cards, and embedded finance, serving more than 150,000 businesses across over 180 countries including Shein, Bolt, TikTok, and Canva.
Founded in 2013 and headquartered in Shanghai, China, ZhongAn is an online only insurance company and established participant in the market, co-founded by Alibaba, Tencent, and Ping An Insurance Group. The company established ZhongAn Technology in 2016 to research blockchain, artificial intelligence, and big data applications, and ZhongAn International in 2017 to pursue overseas fintech and insurtech collaboration.
Founded in 1998 and headquartered in Shenzhen, China, Tencent is a leading name in the market whose financial technology division operates WeChat Pay and the TenPay Global cross border payment platform. The company's broader financial technology portfolio spans wealth management, micro lending, and insurance distribution services delivered through the WeChat ecosystem, serving over a billion monthly active users across its core social and payments platform.
Founded in 2015 and headquartered in Shenzhen, China, OneConnect is a technology as a service provider for China's financial services industry, offering digital banking, blockchain insurance, and financial cloud services to banks and insurers. The company operates the Gamma core banking platform and maintains operational presence across Hong Kong, Singapore, Malaysia, and Indonesia, serving financial institutions throughout the region.
Other key players in the market include Beijing Lerong Duoyuan Information Technology Co., Ltd., Shanghai Dianrong Financial Information Services Co., Ltd., Rong360.com Inc., Lufax Holdings Limited, Mashang Consumer Finance Co., Ltd., ZhongAn Online Property Insurance Co., Ltd., and Futu Securities International (Hong Kong) Limited, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our China fintech market trends 2026 report. Discover deployment mode and application economics, technology adoption trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 90.50 Billion.
The market is projected to grow at a CAGR of 18.30% between 2026 and 2035.
The market is assessed to witness healthy growth in the forecast period to reach around USD 485.84 Billion in 2035.
The major market drivers include increasing utilisation of telemedicine, e-commerce, and e-learning is boosting the requirement for fintech services and rising sophistication of financial software development companies.
The key trends fuelling the growth of the market include increasing adoption of novel technologies by the sector including blockchain, artificial intelligence, cloud computing, augment reality and virtual reality, and machine learning and increasing access to capital.
Based on the applications, the market is divided into banking, insurance, and securities, among others.
Based on the technology, the market is divided into artificial intelligence, application programming interface (API), robotic process automation, and data analytics, among others.
The key players in the market include Airwallex, ZhongAn Technologies International Group Limited, Beijing Lerong Duoyuan Information Technology Co., Ltd., Shanghai Dianrong Financial Information Services Co., Ltd., Tencent Holdings Ltd., Rong360.com Inc., Lufax Holdings Limited, Mashang Consumer Finance Co., Ltd., ZhongAn Online Property Insurance Co., Ltd., Futu Securities International (Hong Kong) Limited, and OneConnect Technology Co.,LTD., among others.
Cloud holds the largest deployment mode share, supported by scalability and lower upfront infrastructure costs.
Banking holds the largest application share, driven by rising adoption of digital lending platforms and mobile payment infrastructure.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Deployment Mode |
|
| Breakup by Technology |
|
| Breakup by Application |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




