

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
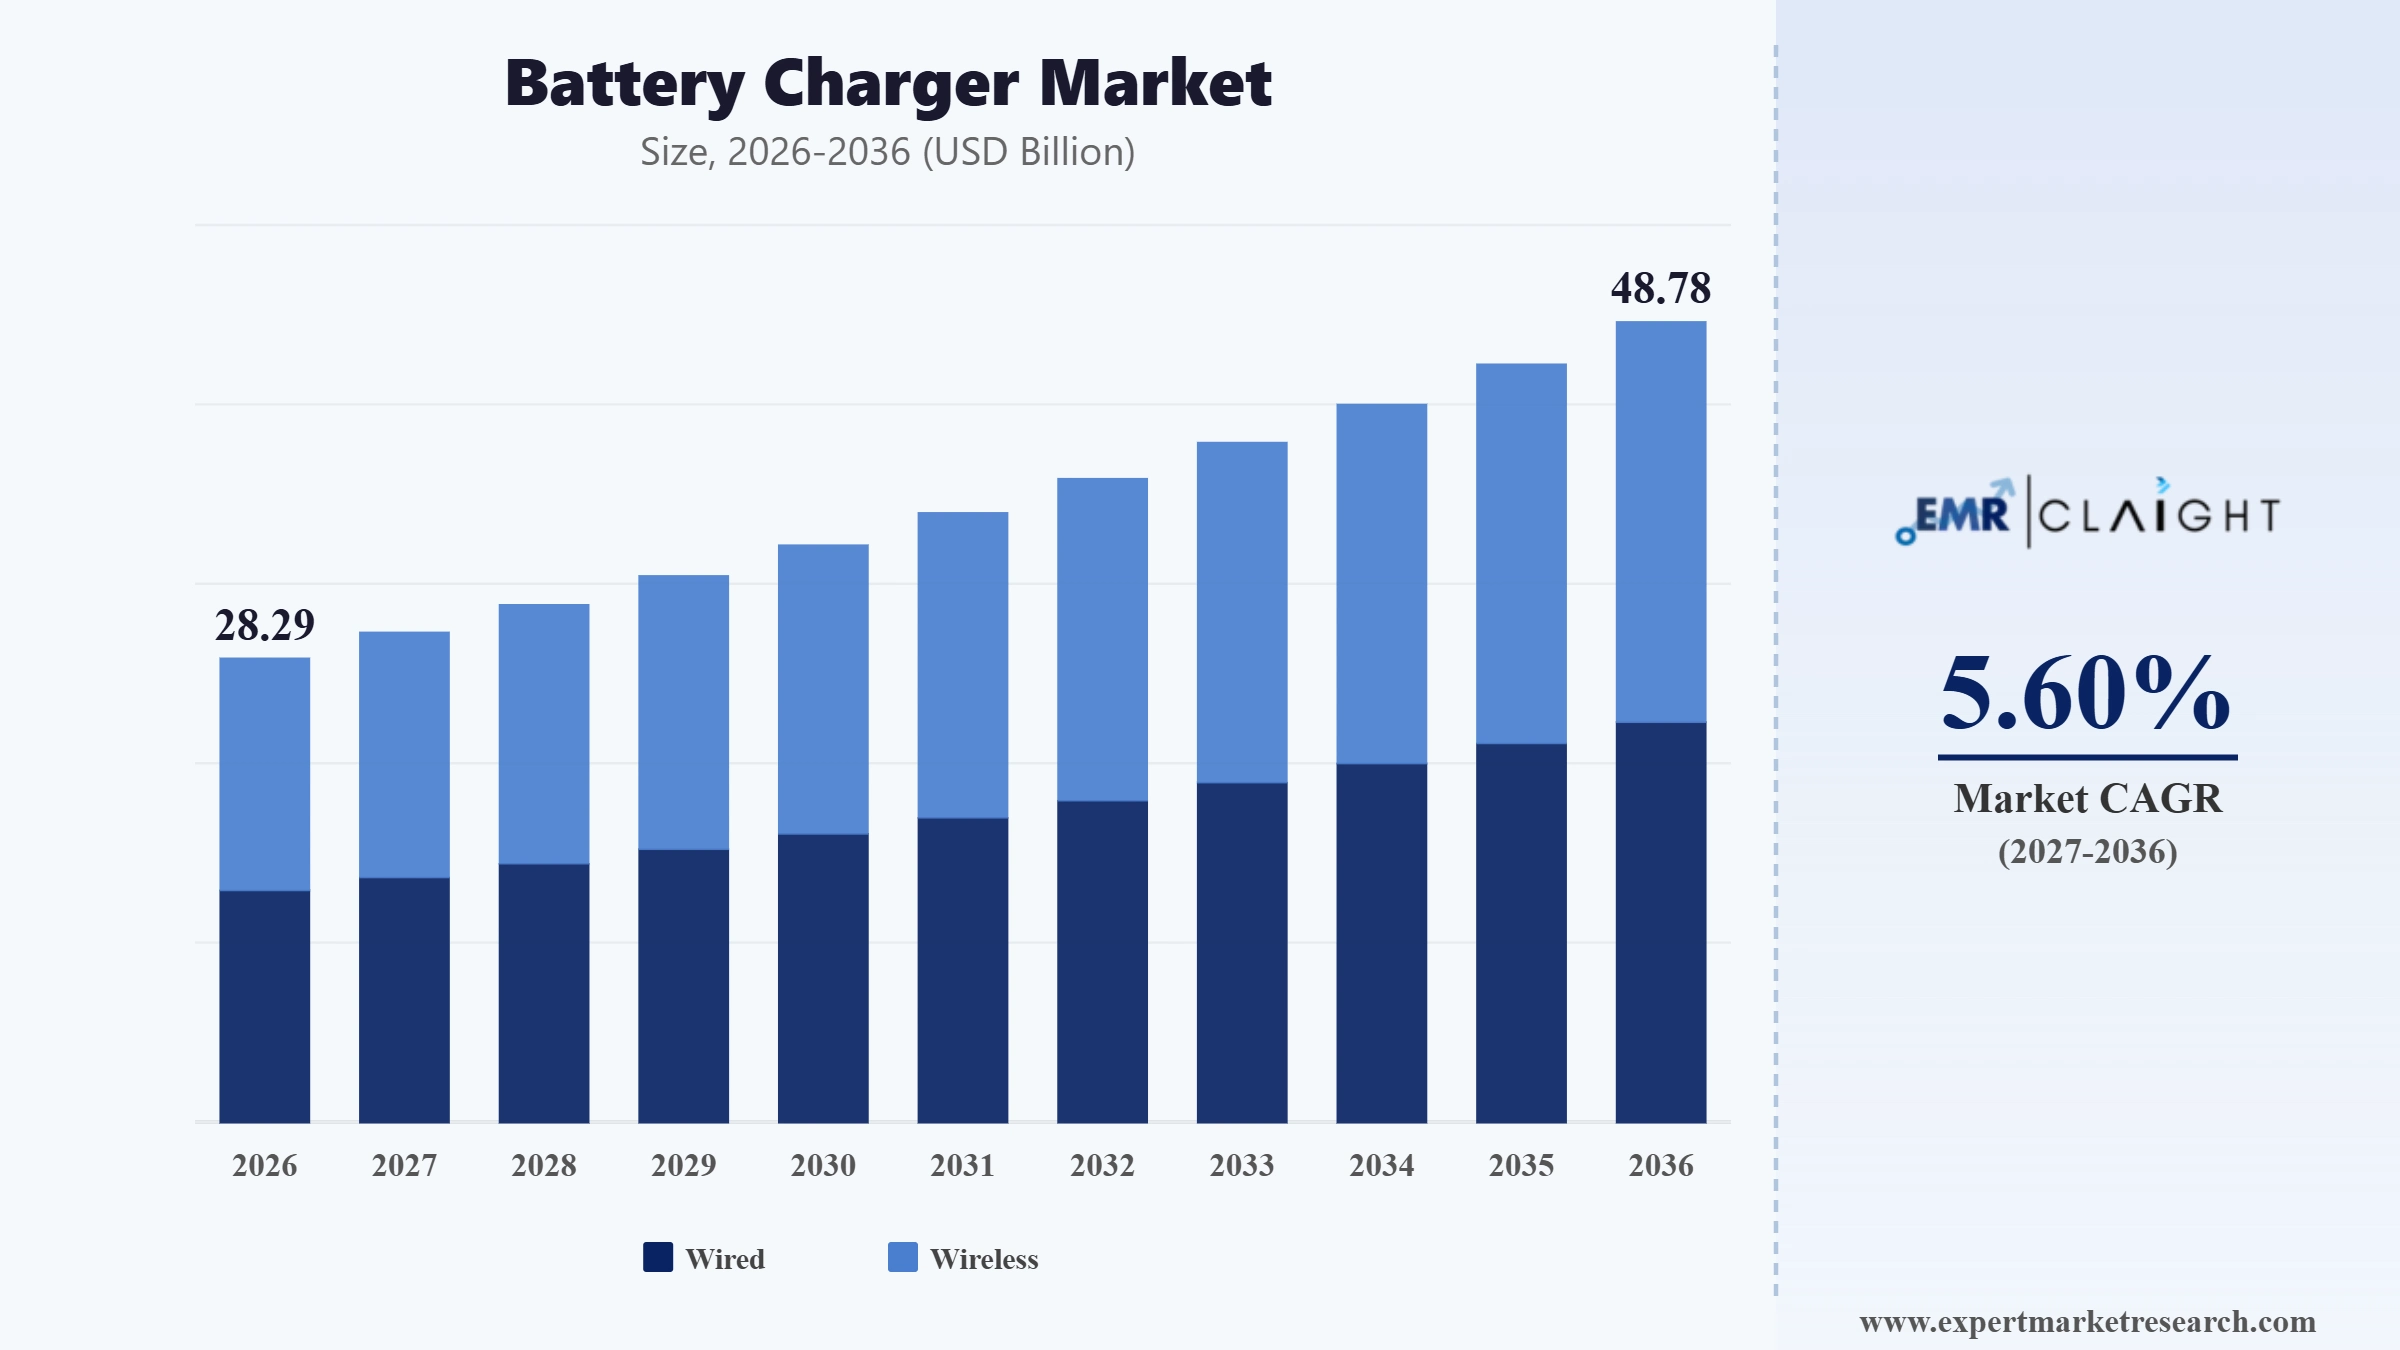
The global battery charger market attained a value of USD 26.79 Billion in 2025 and is projected to grow at a CAGR of 5.60% through 2035, reaching USD 46.20 Billion by 2035, driven by accelerating electric vehicle adoption, rising smart-grid integration, and sustained demand for consumer electronics charging infrastructure worldwide.
Accelerating electric vehicle adoption and rising smart-grid integration continue to anchor steady demand across the global battery charger market. Schneider Electric launched Schneider Charge, a smart Level 2 residential EV charger with built-in SmartAmp load-management technology, in the United States and Canada in August 2026, addressing homeowners' need to avoid costly electrical panel upgrades that can otherwise cost up to USD9,000.
The global battery charger market is witnessing further developments as established power management companies expand commercial and industrial charging infrastructure to serve fleet electrification demand. Eaton and ChargePoint launched breakthrough ultrafast DC vehicle-to-everything chargers in August 2025, delivering up to 600 kilowatts for passenger EVs and megawatt-scale charging for commercial fleets while reducing capital expenditure and footprint by approximately 30 percent.
In addition, established industrial battery manufacturers continue expanding specialised charger product lines to serve backup power and material-handling applications. Exide Technologies expanded its Marathon portfolio with a new TPPL battery range in July 2026, combining advanced technology with lower total cost of ownership for telecom, data center, and industrial uninterruptible power supply operators worldwide.
Read more about this report - Request a Free Sample
| Global Battery Charger Market Report Summary | Description | Value |
| Base Year | USD Billion | 2025 |
| Historical Period | USD Billion | 2019-2025 |
| Forecast Period | USD Billion | 2026-2035 |
| Market Size 2025 | USD Billion | 26.79 |
| Market Size 2035 | USD Billion | 46.20 |
| CAGR 2019-2025 | Percentage | XX% |
| CAGR 2026-2035 | Percentage | 5.60% |
| CAGR 2026-2035 - Market by Region | Latin America | 6.1% |
| CAGR 2026-2035 - Market by Country | India | 6.8% |
| CAGR 2026-2035 - Market by Country | Canada | 6.6% |
| CAGR 2026-2035 - Market by Product Type | Wireless | 7.1% |
| CAGR 2026-2035 - Market by Category | Replacement | 6.1% |
| Market Share by Country 2025 | Japan | 5.8% |
Home energy management companies continue introducing intelligent load-management technology to simplify residential EV charger installation without costly electrical upgrades. Schneider Electric launched Schneider Charge, a smart Level 2 residential EV charger, in the United States and Canada in August 2026, featuring built-in SmartAmp technology that automatically adjusts charging output based on real-time household electrical capacity, avoiding panel upgrades that can otherwise cost up to USD9,000. Companies can integrate intelligent load-management technology directly into charging hardware to eliminate costly installation barriers for residential customers.
Industrial battery manufacturers continue expanding specialised product lines to serve backup power applications requiring lower total cost of ownership. Exide Technologies expanded its Marathon portfolio with a new thin plate pure lead battery range in July 2026, combining advanced TPPL technology with reduced total cost of ownership for telecom, data center, and industrial uninterruptible power supply operators requiring critical backup power. Companies can expand specialised battery and charging technology portfolios to serve high-reliability backup power applications across telecom and data centre infrastructure.
Automotive aftermarket charger manufacturers continue introducing ruggedised product lines addressing professional mechanics' demand for durable, hard-to-reach terminal access. Schumacher Electric launched its Rugged by Schumacher battery charger and maintainer series in November 2025, supporting both 6-volt and 12-volt systems with patent-pending Flex Eyelet Technology allowing clamps to convert into ring leads for improved terminal accessibility. Companies can introduce ruggedised, professional-grade product lines to differentiate against mass-market consumer charger offerings.
Power management companies continue partnering with charging network operators to deliver scalable, grid-integrated infrastructure addressing commercial fleet electrification demand. Eaton and ChargePoint launched breakthrough ultrafast DC vehicle-to-everything chargers in August 2025, delivering up to 600 kilowatts for passenger EVs and megawatt-scale charging for commercial fleets, with deliveries beginning in the second half of 2026 across North America and Europe. Companies can partner with charging network operators to deliver scalable, vehicle-to-grid-integrated infrastructure addressing commercial fleet electrification demand.
Power management companies continue expanding commercial charging portfolios to serve workplaces, multi-unit dwellings, and fleet operators alongside residential offerings. Schneider Electric launched Schneider Charge Pro, a commercial Level 2 EV charger bundling hardware, network management software, and a five-year warranty, in the United States in July 2026, offered in 48-amp and 80-amp configurations for workplaces, apartment communities, and fleet operators. Companies can bundle charging hardware with network management software and extended warranties to differentiate commercial charging offerings.
Dedicated electric vehicle charging infrastructure continues outpacing broader battery charger category growth as global EV adoption accelerates across both residential and commercial settings. Industry data published in July 2026 showed the electric vehicles application segment growing at a projected 15.60 percent CAGR, faster than the overall market's 5.60 percent rate, as manufacturers expand Level 2 and DC fast-charging product lines across both consumer and fleet-focused use cases. Companies can expand dedicated EV charging product lines to capture the fastest-growing application segment within the broader battery charger category.
Inductive charging technology continues gaining adoption across smartphones, wearables, and other portable consumer electronics as manufacturers prioritise cable-free convenience. Industry estimates published in May 2026 showed the wireless product type growing at a projected 11.20 percent CAGR, faster than the overall market, as consumer electronics manufacturers increasingly integrate inductive charging capability as a standard feature across premium and mid-tier device categories. Companies can integrate inductive wireless charging capability as a standard feature to capture accelerating consumer electronics demand.
Original equipment manufacturer-supplied chargers continue accounting for the bulk of category volume even as the replacement segment gains share alongside expanding device ownership. GS Yuasa and Panasonic both announced price increases of at least 20 percent for replacement lead-acid automotive batteries in the Japanese market in June 2026, citing sustained raw material, energy, and logistics cost pressure across the replacement battery and charger segment. Companies can maintain strong OEM bundling relationships while expanding compatible aftermarket replacement offerings to capture both category segments.
This Expert Market Research Report titled "Global Battery Charger Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Product Type
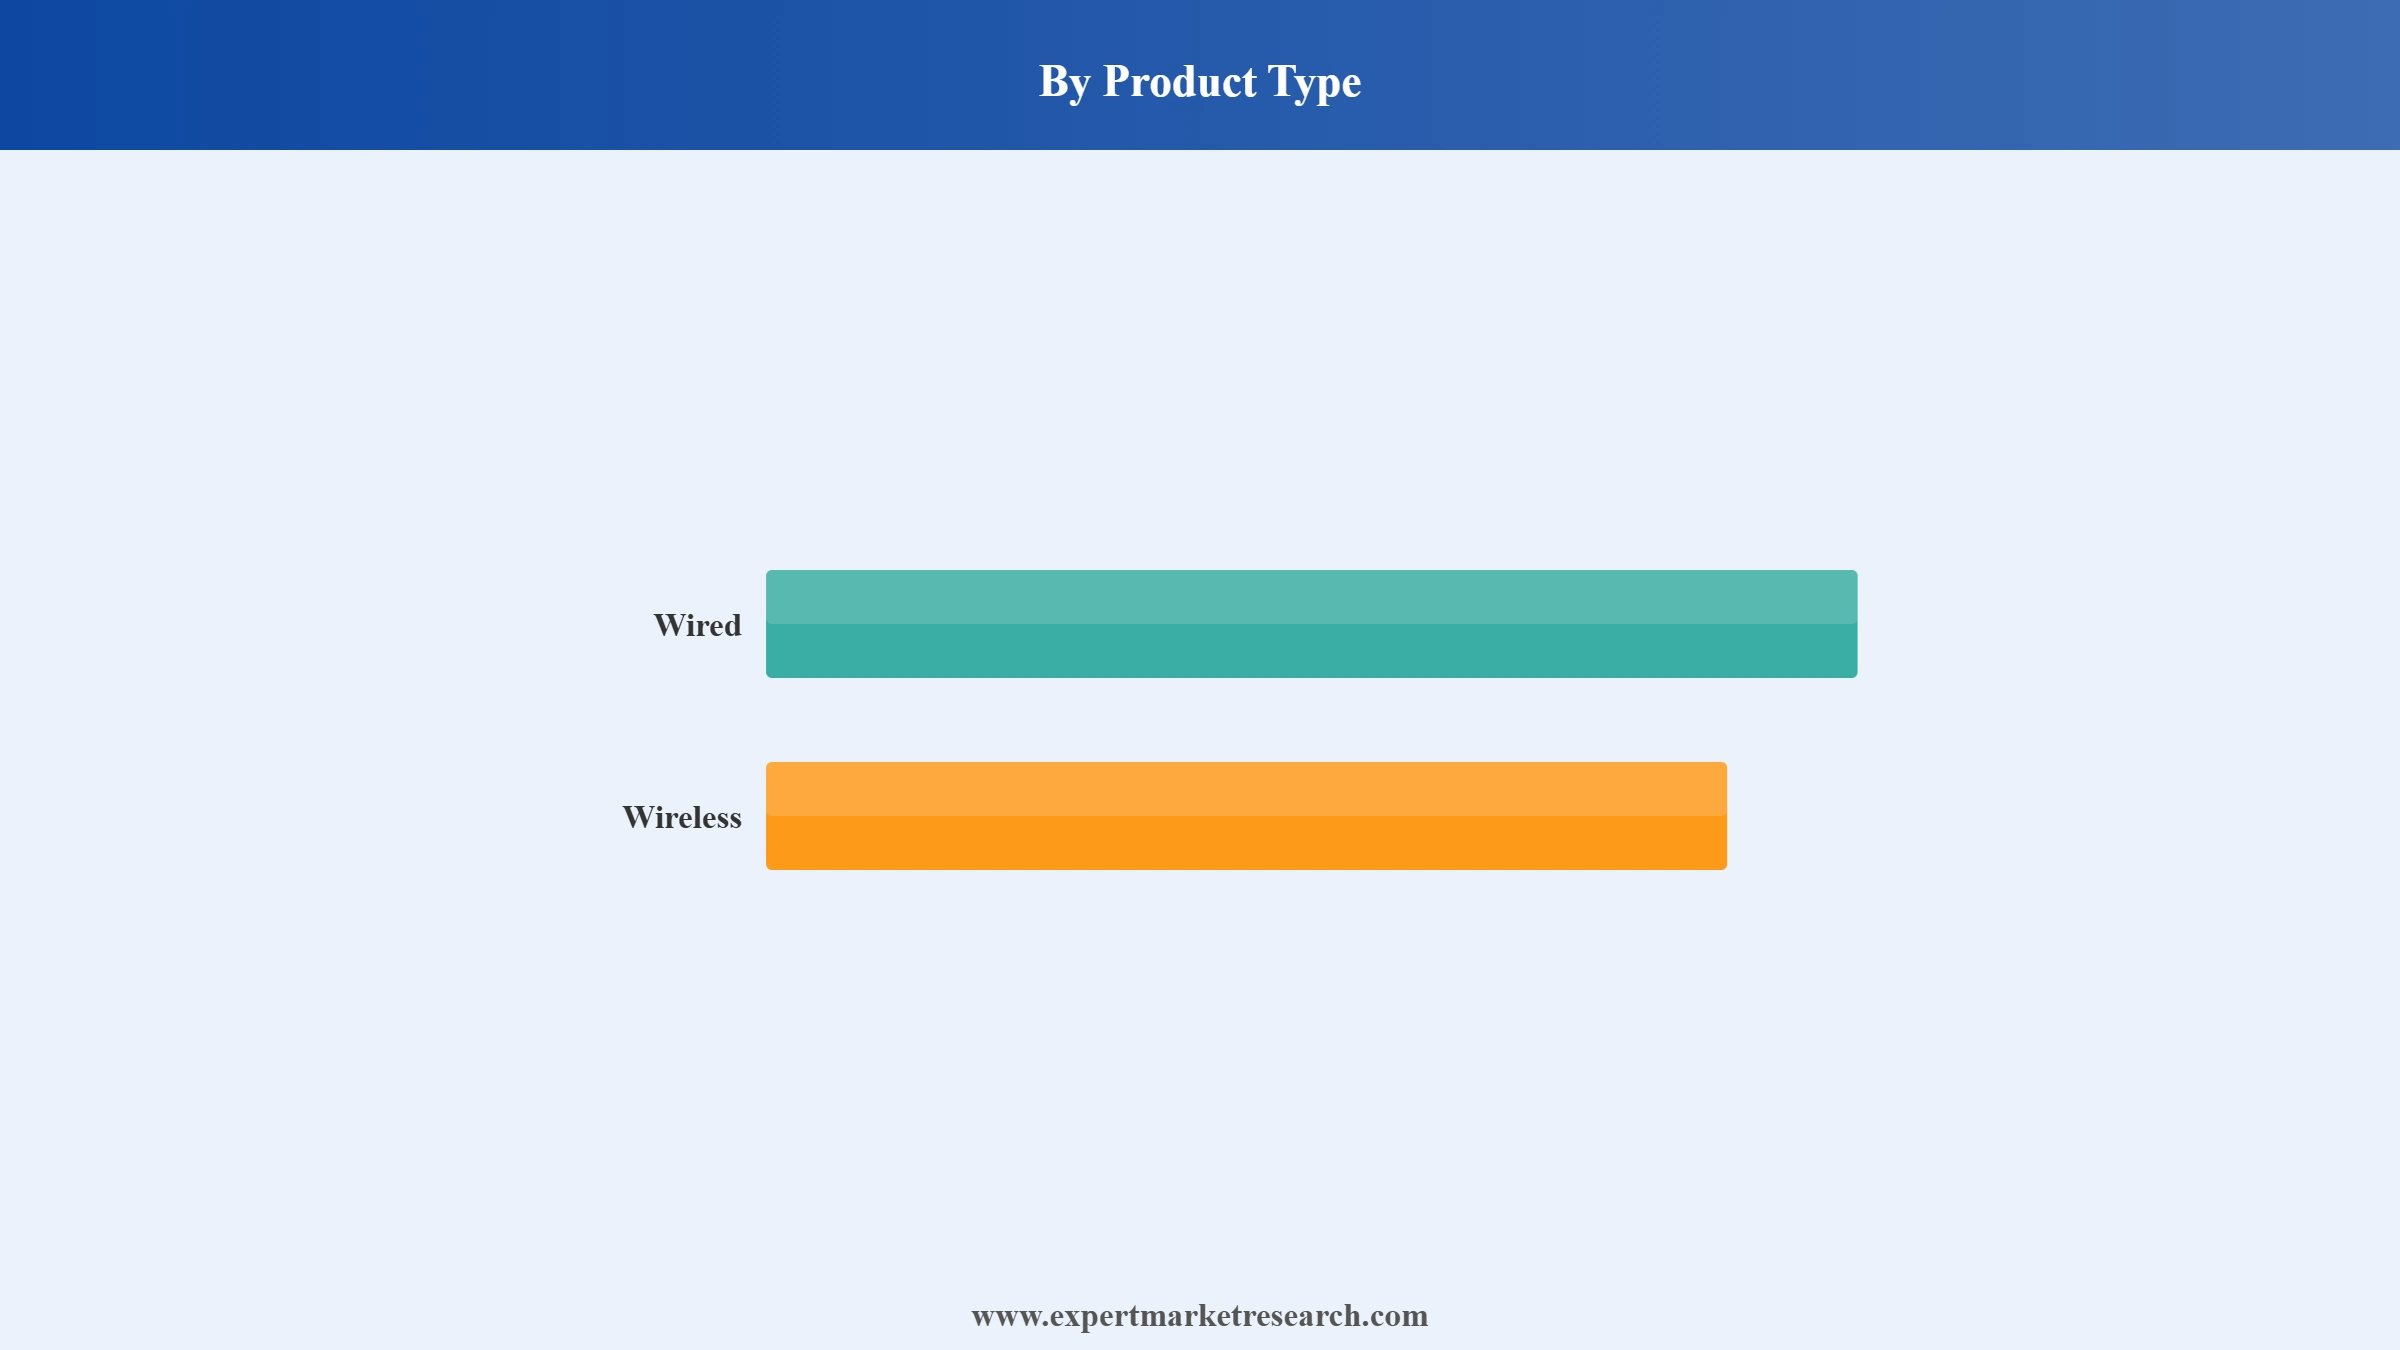
Key Insight: Wired accounts for the largest share of the market, reflecting established charging infrastructure and higher power delivery efficiency across most device categories worldwide. Wireless is growing fastest at a projected 11.20 percent CAGR, with industry reporting published in February 2026 highlighting several leading smartphone manufacturers announcing faster wireless charging speeds and magnetic alignment standards for upcoming device generations.
Market Breakup by Application
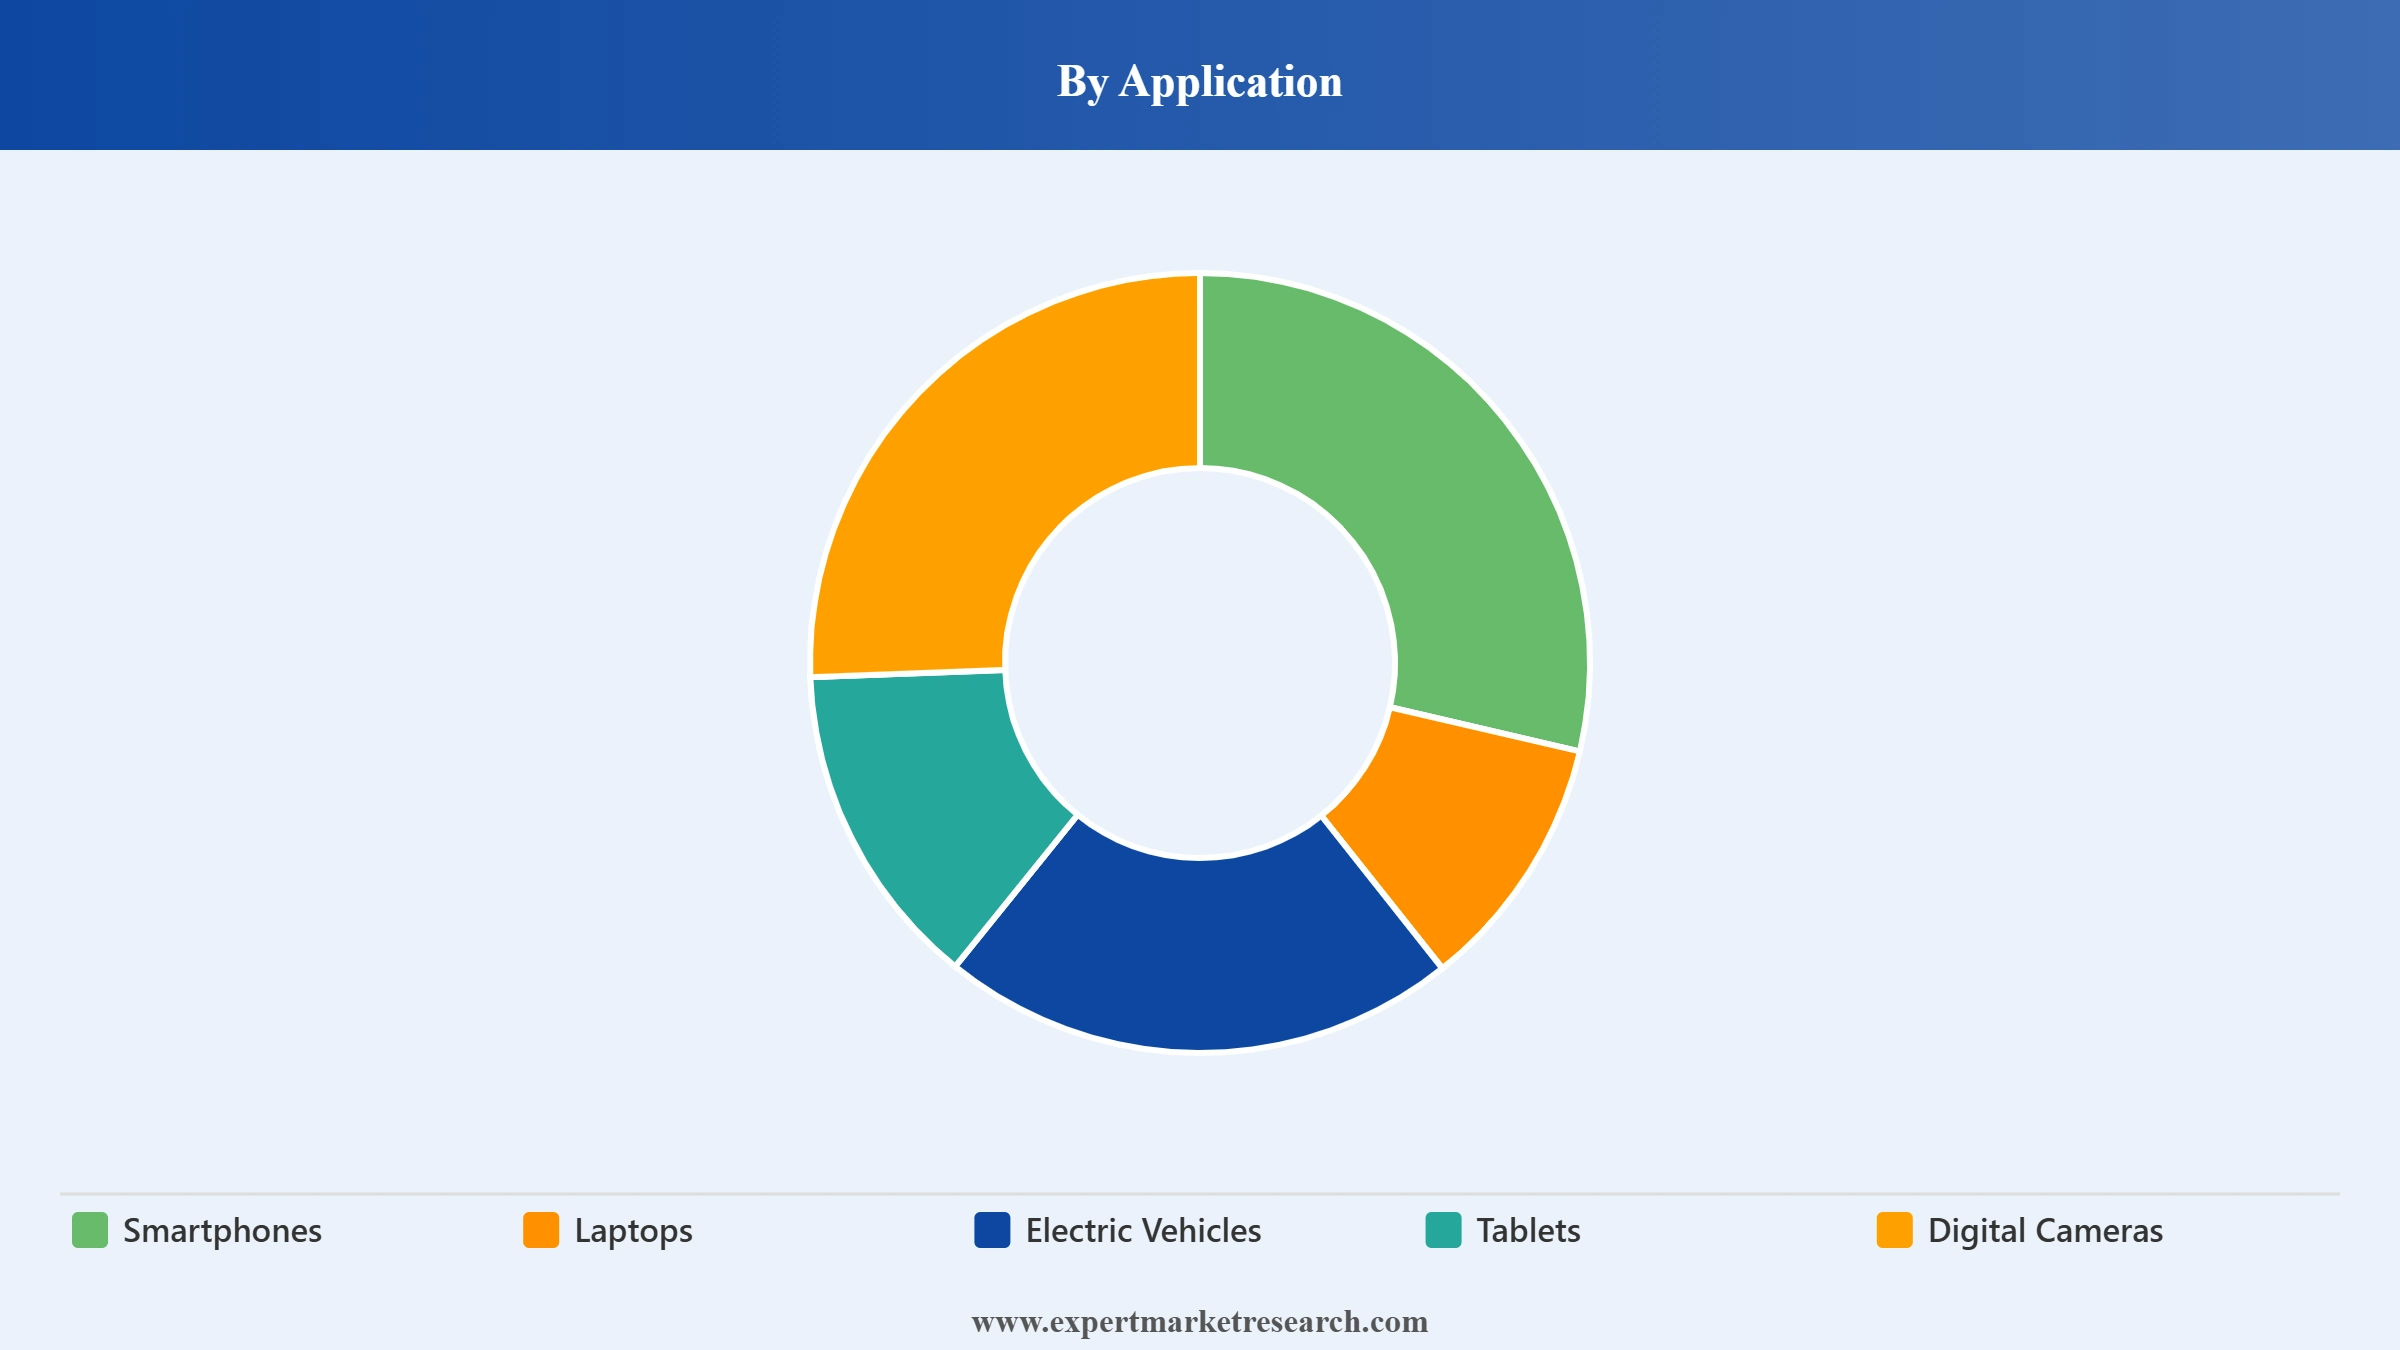
Key Insight: Smartphones accounts for the largest share of the market, reflecting the sheer scale of global device ownership and replacement cycles nationwide. Laptops and Tablets continue to represent substantial demand tied to remote work and education device adoption, while Digital Cameras and Others, including wearables and power tools, address distinct niche categories. Electric Vehicles is growing fastest at a projected 15.60 percent CAGR, illustrated by Schneider Electric's August 2026 launch of its SmartAmp-enabled residential Level 2 EV charger.
Market Breakup by Category
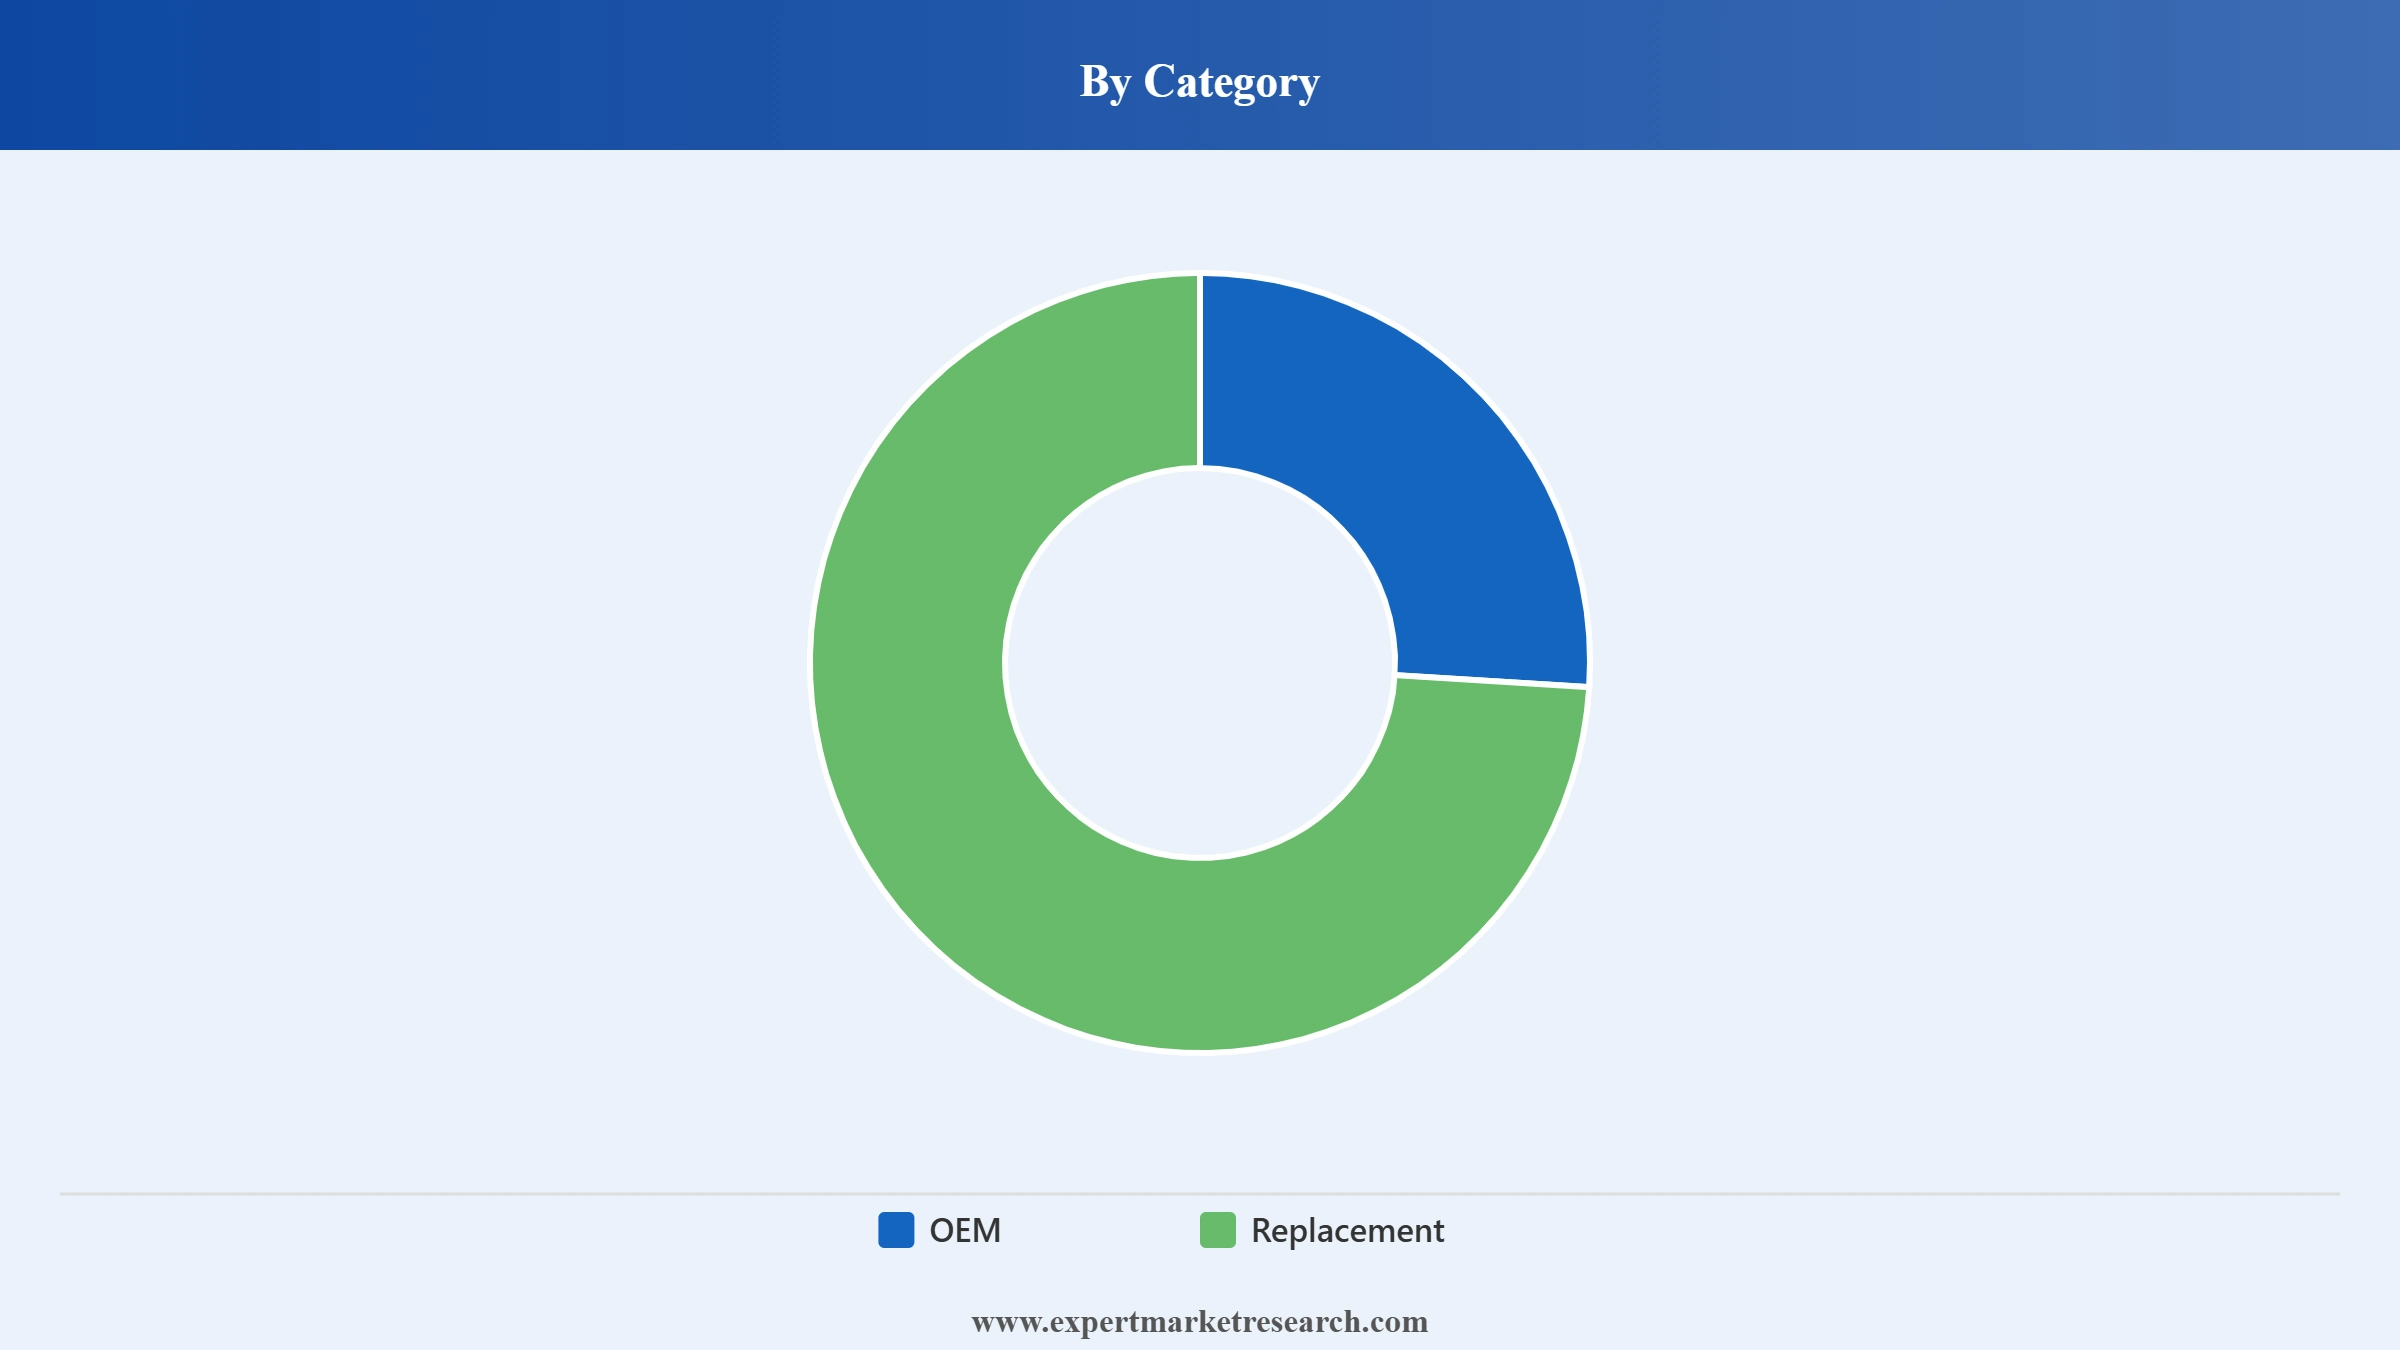
Key Insight: OEM accounts for the largest share of the market, reflecting chargers bundled directly with smartphones, laptops, and electric vehicles at point of sale worldwide. Replacement continues to grow steadily as devices age and consumers increasingly seek compatible aftermarket charging solutions, illustrated by Schumacher Electric's November 2025 launch of its Rugged battery charger and maintainer series targeting the automotive aftermarket segment specifically.
Market Breakup by Region
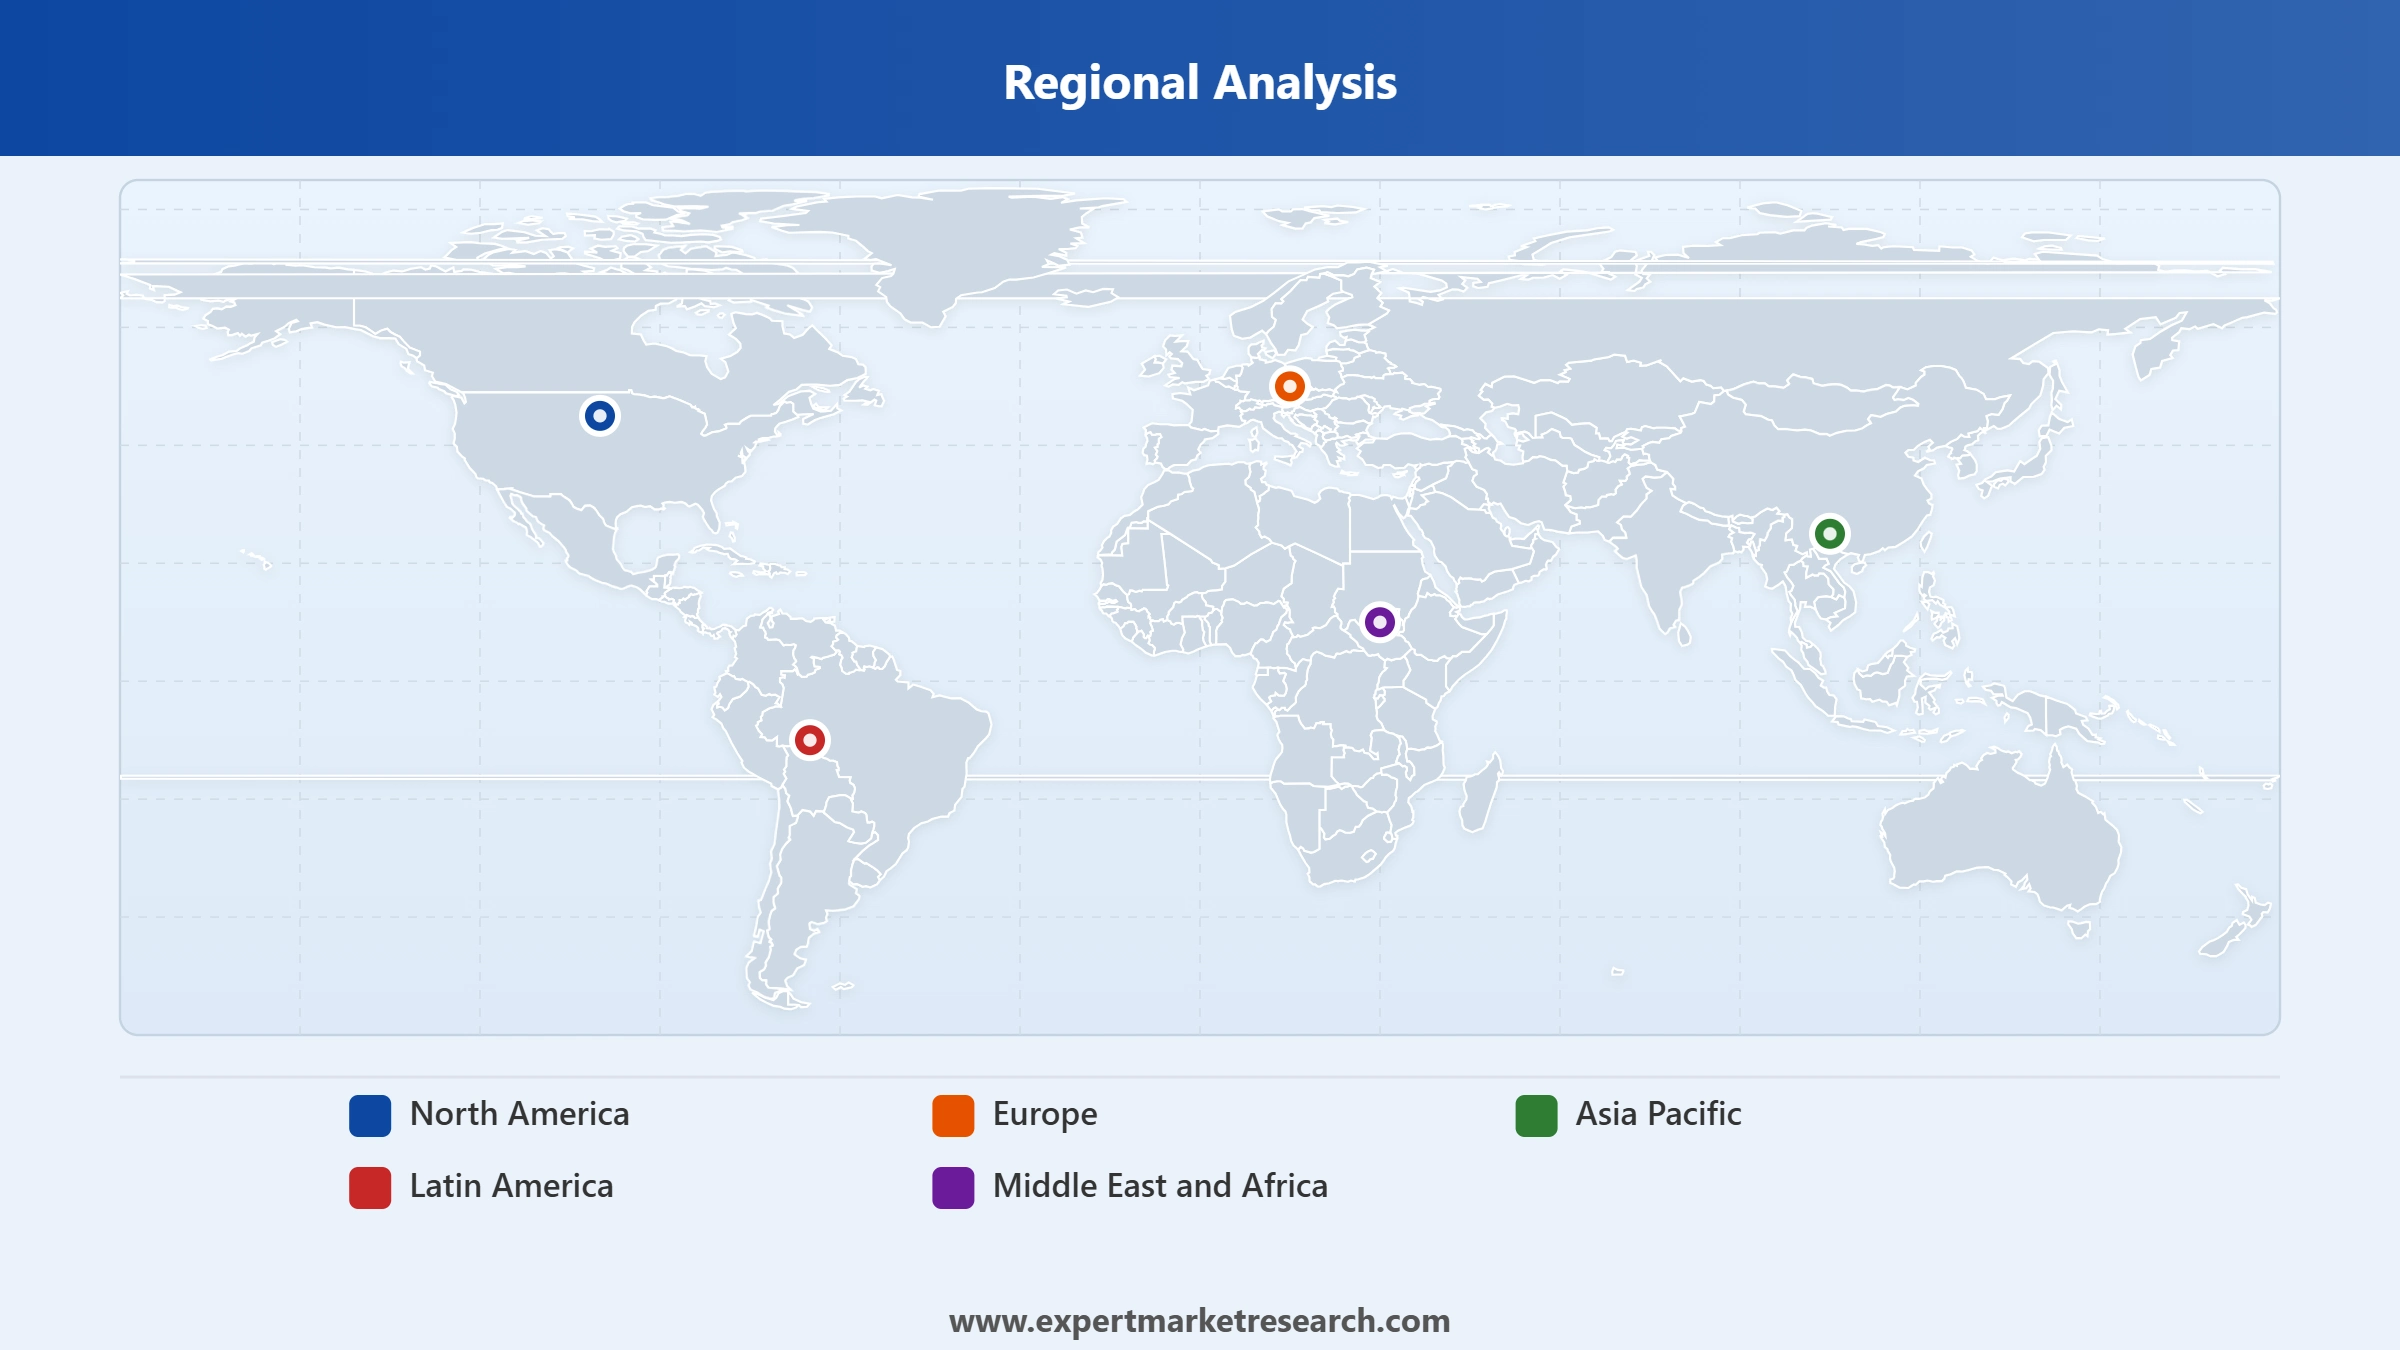
Key Insight: North America accounts for the largest share of the market, anchored by established power management companies and rapidly expanding EV charging infrastructure investment, illustrated by Eaton and ChargePoint's August 2025 launch of ultrafast DC V2X chargers across the region. Europe continues to represent substantial demand tied to established industrial battery manufacturing, reinforced by Exide Technologies' July 2026 Marathon TPPL battery range expansion. Latin America and Middle East and Africa serve steadily expanding demand as charging infrastructure investment accelerates across both regions. Asia Pacific is growing fastest at an estimated 9.40 percent CAGR, supported by expanding electric vehicle manufacturing and consumer electronics production across China, Japan, and India.
Read more about this report - Request a Free Sample
Wired continues to account for the largest share of the market, reflecting established charging infrastructure and higher power delivery efficiency across most device categories worldwide. Established manufacturers continue anchoring the wired segment through extensive OEM bundling relationships across smartphones, laptops, and electric vehicles nationwide.
Read more about this report - Request a Free Sample
Wireless is the fastest-growing product type at a projected 11.20 percent CAGR. Consumer electronics manufacturers continue integrating inductive charging capability as a standard feature, reinforced by rising adoption across premium and mid-tier smartphone and wearable device categories throughout 2026.
Smartphones continues to account for the largest share of the market, reflecting the sheer scale of global device ownership and replacement cycles worldwide. Established consumer electronics manufacturers continue anchoring the dominant application category through high-volume OEM charger bundling nationwide.
Read more about this report - Request a Free Sample
Electric Vehicles is the fastest-growing application at a projected 15.60 percent CAGR. Eaton and ChargePoint's August 2025 ultrafast DC vehicle-to-everything charging infrastructure, delivering up to 600 kilowatts for passenger EVs and megawatt-scale charging for commercial fleets, reinforced accelerating investment in dedicated EV charging technology across both residential and commercial settings.
OEM continues to account for the largest share of the market, reflecting chargers bundled directly with smartphones, laptops, and electric vehicles at point of sale worldwide. Established device manufacturers continue anchoring the dominant OEM category through standardised bundling practices across major product launches nationwide.
Read more about this report - Request a Free Sample
Replacement continues to grow steadily as devices age and consumers increasingly seek compatible aftermarket charging solutions. GS Yuasa and Panasonic both announced price increases of at least 20 percent for replacement lead-acid automotive batteries in the Japanese market in June 2026, citing sustained increases in raw material, energy, and logistics costs across the replacement battery segment.
The United States continues to anchor the region's outsized contribution to global battery charger demand, supported by Eaton and ChargePoint's ultrafast DC charging infrastructure rollout and Schneider Electric's expanding residential and commercial EV charger portfolio across North America.
Read more about this report - Request a Free Sample
Europe continues to represent substantial demand tied to established industrial battery manufacturing, reinforced by Exide Technologies' Marathon TPPL battery range expansion, while Latin America and Middle East and Africa serve steadily expanding demand as charging infrastructure investment accelerates across both regions. Asia Pacific is the fastest-growing region at an estimated 9.40 percent CAGR, supported by expanding electric vehicle manufacturing and consumer electronics production across China, Japan, and India.
The industry is fragmented, with global battery charger market companies ranging from established power management conglomerates to specialised industrial and automotive aftermarket manufacturers competing across product type, application, and category segments worldwide.
Competitive dynamics among global battery charger players are increasingly shaped by the pace of smart-grid and load-management technology integration, the depth of commercial fleet charging partnerships, and the strength of aftermarket distribution networks. Manufacturers are investing in intelligent charging software, vehicle-to-everything capabilities, and ruggedised product lines to secure long-term relationships with residential, commercial, and industrial customers alike.
Founded in 1836 and headquartered in Rueil-Malmaison, France, Schneider Electric is a global leader in home and commercial energy management, offering EV charging infrastructure through its Square D brand. The company launched Schneider Charge, a smart Level 2 residential EV charger featuring SmartAmp load-management technology, in the United States and Canada in August 2026, followed by its Schneider Charge Pro commercial offering in July 2026. Schneider Electric's integrated load-management technology differentiates its offering from competitors requiring costly electrical panel upgrades.
Founded in 1911 and headquartered in Dublin, Ireland, Eaton is an intelligent power management company serving customers in more than 160 countries with revenues of nearly USD25 billion. The company partnered with ChargePoint to launch breakthrough ultrafast DC vehicle-to-everything chargers in August 2025, delivering up to 600 kilowatts for passenger EVs and megawatt-scale charging for commercial fleets. Eaton's Everything as a Grid approach and vehicle-to-everything capabilities differentiate its offering from competitors focused solely on unidirectional charging infrastructure.
Founded in 1888 and headquartered in Milton, Georgia, United States, Exide Technologies is a global battery manufacturer serving automotive, industrial, and backup power applications. The company expanded its Marathon portfolio with a new thin plate pure lead battery range in July 2026, combining advanced technology with lower total cost of ownership for telecom, data center, and industrial uninterruptible power supply operators. Exide's specialised industrial charger and battery integration differentiates its offering from consumer-focused competitors.
Founded in 1947 and headquartered in Fort Worth, Texas, United States, Schumacher Electric designs and manufactures automotive battery chargers, jump starters, and maintainers for both professional and consumer markets. The company launched its Rugged by Schumacher battery charger and maintainer series in November 2025, featuring patent-pending Flex Eyelet Technology for improved terminal accessibility. Schumacher's automotive aftermarket specialisation and patent-pending clamp technology differentiate its offering from broader consumer electronics charger competitors.
Other key players in the global battery charger market include Hitachi Ltd., ABB Ltd., Phihong Technology Co. Ltd., Ultralife Corp., Yuasa Battery, Inc., Panasonic Holdings Corp., Analytic Systems Ware Ltd., Associated Equipment Corp., Charging Technologies Inc., and Hindlepower, Inc., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our global battery charger market trends 2026 report. Discover regional growth patterns, product type and application adoption trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 26.79 Billion.
The market is projected to grow at a CAGR of 5.60% between 2026 and 2035.
The market is estimated to witness healthy growth during 2026-2035 to reach around USD 46.20 Billion by 2035.
Integrating intelligent load-management and vehicle-to-everything technology, expanding commercial fleet charging partnerships, developing ruggedised aftermarket product lines, and investing in inductive wireless charging capability.
The key trends aiding the market include the growth of all-in-one chargers, the launch of high-speed chargers, and the trend of sustainability.
The market is broken down into North America, Europe, Asia Pacific, Latin Americam and the Middle East, and Africa.
Based on product type, market segmentations include wired and wireless.
Different applications of battery chargers are smartphones, laptops, electric vehicles, tablets, and digital cameras, among others.
The key players in the market include Schneider Electric SE, Eaton Corporation Plc, Exide Technologies, LLC, Schumacher Electric Corporation, Hitachi Ltd., ABB Ltd., Phihong Technology Co. Ltd., Ultralife Corp., Yuasa Battery, Inc., Panasonic Holdings Corp., Analytic Systems Ware Ltd., Associated Equipment Corp., Charging Technologies Inc., and Hindlepower, Inc.
Manufacturers face grid capacity constraints limiting large-scale fast-charging deployment, intensifying competition within an increasingly crowded residential EV charger category, and the need for continuous compatibility with evolving connector and communication standards.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Product Type |
|
| Breakup by Application |
|
| Breakup by Category |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




