

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
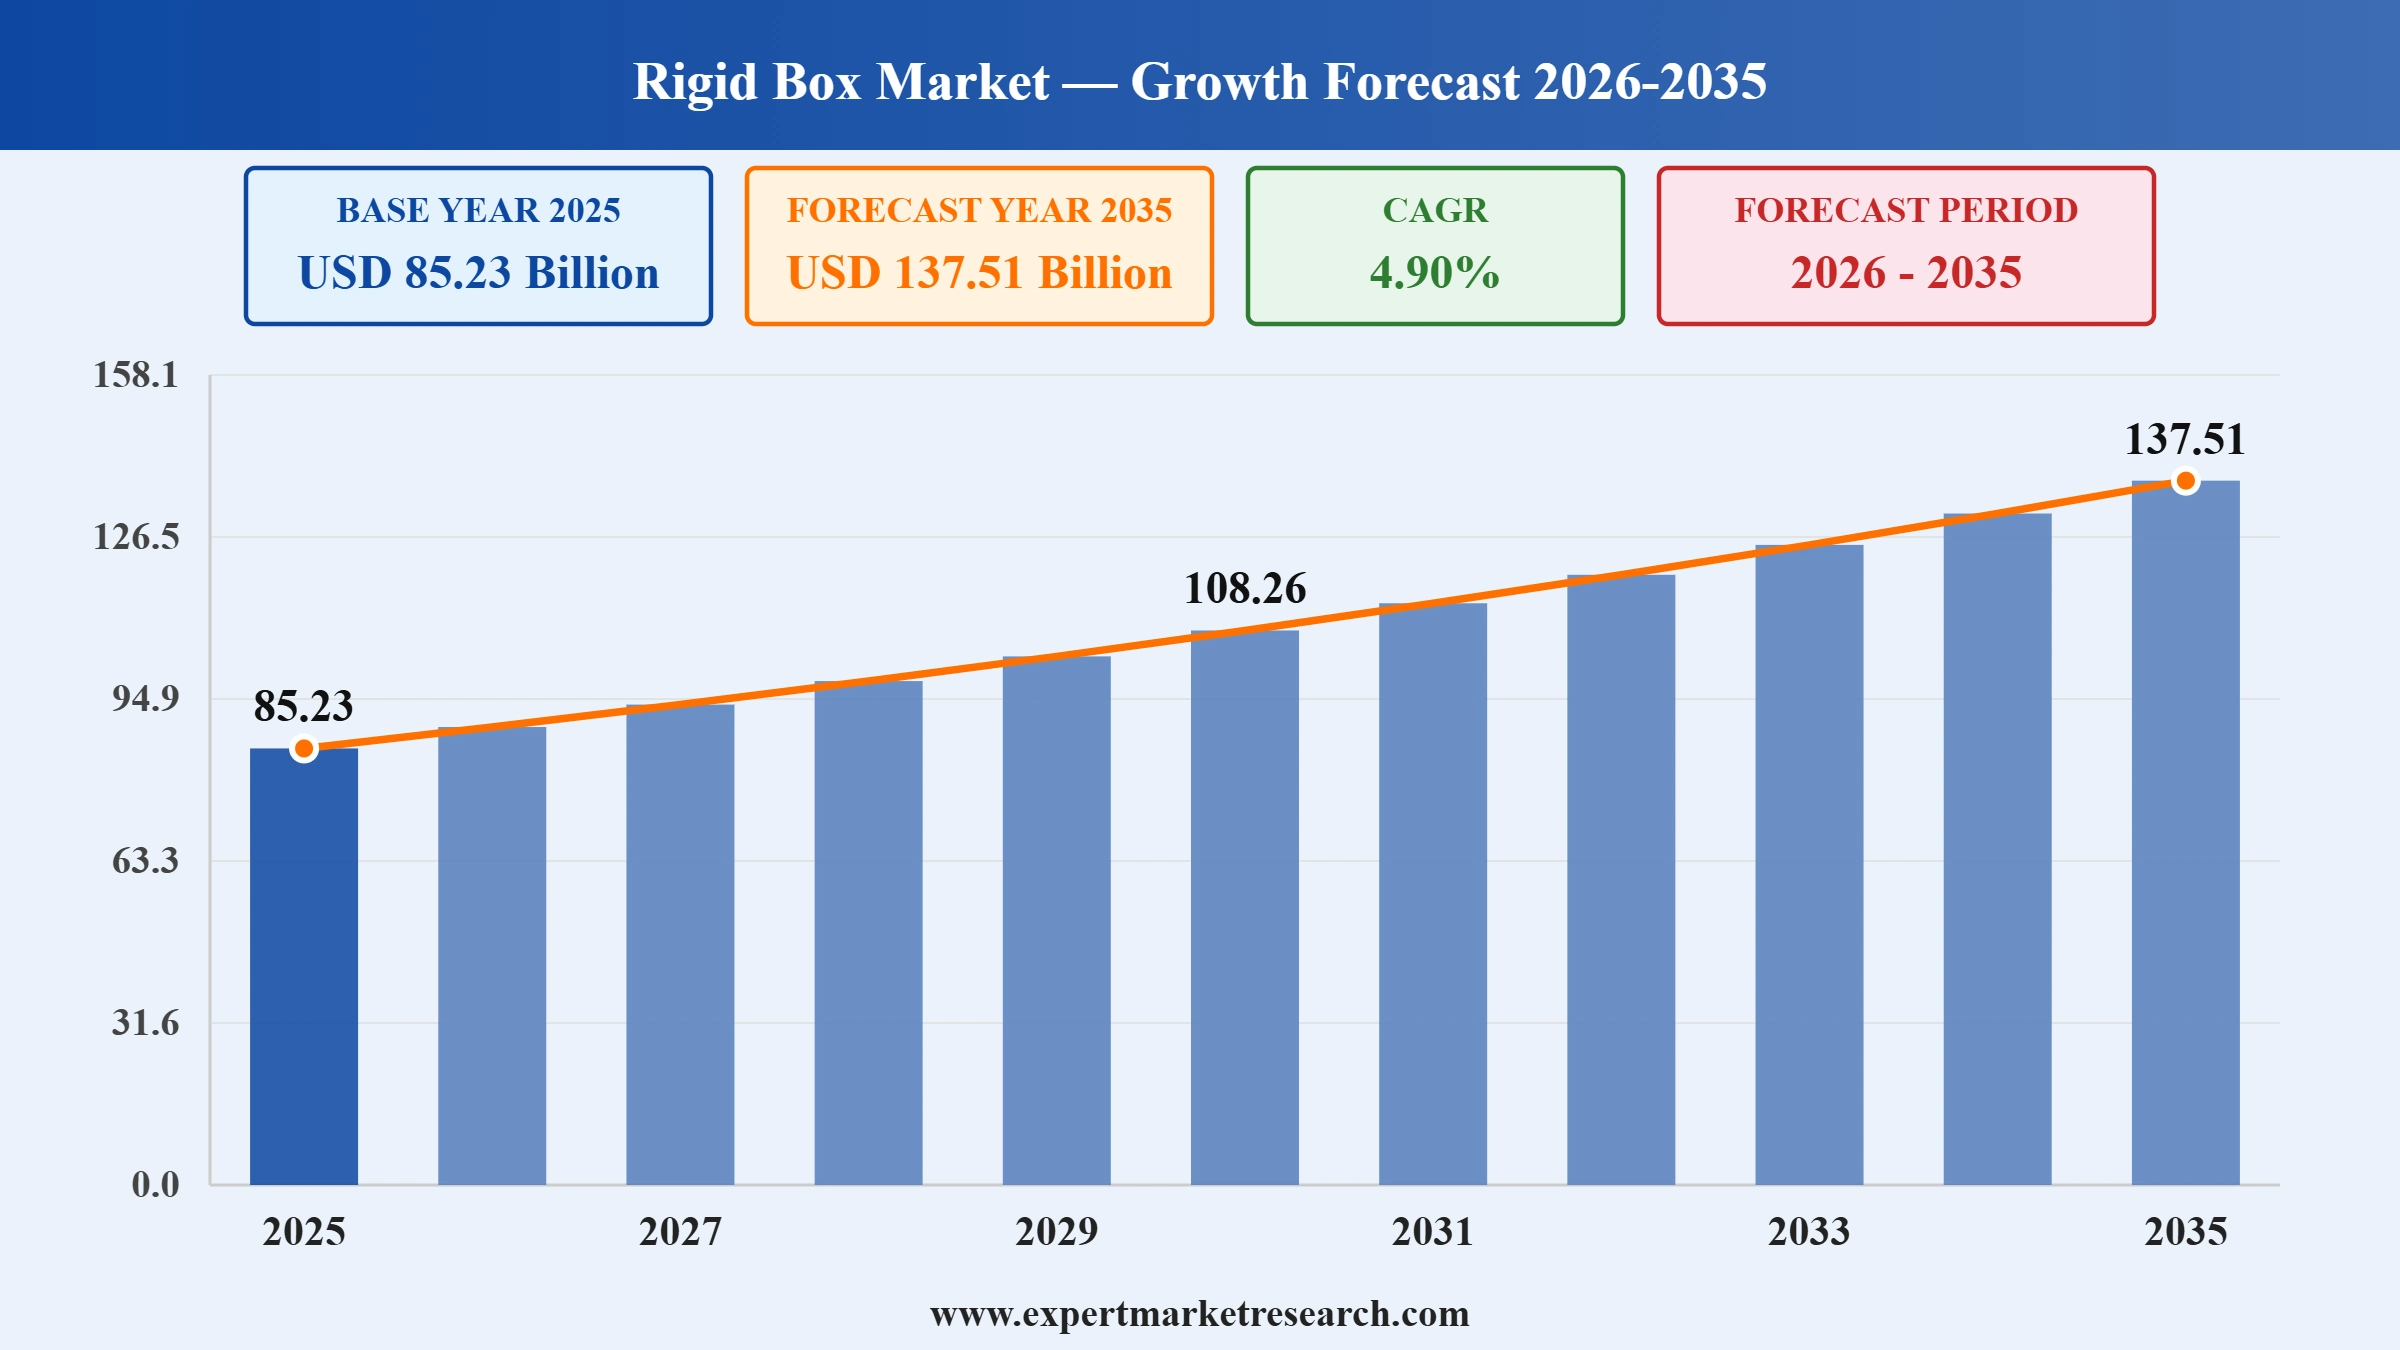
The global rigid box market attained a value of USD 85.23 Billion in 2025 and is projected to expand at a CAGR of 4.90% through 2035. The market is further expected to achieve USD 137.51 Billion by 2035. Rising demand for premium unboxing experiences, expanding luxury goods and e-commerce sectors, and continued brand owner investment in sustainable, FSC-certified packaging materials are encouraging converters to expand rigid box manufacturing capacity.
Rising demand for premium unboxing experiences continues to anchor steady demand across the rigid box market, as luxury brands increasingly treat packaging as a core brand differentiation tool rather than purely functional protection. Converters are also investing in sustainable, FSC-certified board sourcing and automated finishing technology as brand owners face mounting regulatory and consumer pressure to demonstrate credible sustainability credentials.
The rigid box market is witnessing further developments as European converters expand dedicated luxury rigid box manufacturing capacity to serve premium spirits, beauty, and confectionery brand owners. Such capacity expansion reflects continued premiumisation across the wider rigid box market as converters serving luxury brands pursue differentiated unboxing experiences alongside sustainability-aligned packaging architectures that increasingly determine which converters win flagship brand contracts.
In addition, recently merged packaging groups are increasingly investing in decorative finishing and set-up box capacity to strengthen their combined premium packaging portfolios following large-scale consolidation. Such post-merger investment underscores accelerating demand for premium presentation packaging across spirits, electronics, and personal care segments, as combined groups seek to realise cross-selling opportunities across their newly expanded customer bases.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
| Rigid Box Market Report Summary | Description | Value |
| Base Year | USD Billion | 2025 |
| Historical Period | USD Billion | 2019-2025 |
| Forecast Period | USD Billion | 2026-2035 |
| Market Size 2025 | USD Billion | 85.23 |
| Market Size 2035 | USD Billion | 137.51 |
| CAGR 2019-2025 | Percentage | XX% |
| CAGR 2026-2035 | Percentage | 4.90% |
| CAGR 2026-2035 - Market by Region | Asia Pacific | 5.7% |
| CAGR 2026-2035 - Market by Country | India | 6.5% |
| CAGR 2026-2035 - Market by Country | Brazil | 6.1% |
| CAGR 2026-2035 - Market by Product Type | Hinged Box | 5.7% |
| CAGR 2026-2035 - Market by End Use | Cosmetics and Personal Care | 5.6% |
| Market Share by Country 2025 | China | 13.6% |
Dunapack Packaging agreed to acquire three of Stora Enso's German packaging facilities, comprising operations generating approximately 74 million euros in 2025 turnover, with the transaction expected to close during 2026 pending merger clearance. Companies can pursue targeted plant acquisitions to increase geographical footprint and strengthen paper integration rates within an existing group structure.
Mayr-Melnhof announced expanded rigid luxury box manufacturing capacity at its European converting sites, targeting premium spirits, beauty, and confectionery brand owners with automation and FSC-certified board sourcing upgrades. Companies can pair automation investment with certified sustainable sourcing to meet luxury brand owner requirements for both production consistency and credible environmental credentials.
Smurfit WestRock announced fresh investment in its rigid set-up box and folding carton operations across North America, targeting premium consumer goods customers with expanded decorative finishing capacity. Companies can expand decorative finishing capacity following major mergers to capture cross-selling opportunities across a newly combined premium packaging customer base.
Konecranes received a contract from Palm to modernise automated paper roll handling equipment, supporting upstream paperboard production efficiency that feeds downstream rigid box converting operations. Companies can invest in upstream material handling automation to improve the production efficiency and cost structure of downstream packaging converting operations.
European packaging converters continue to expand dedicated luxury rigid box manufacturing capacity as premium spirits, beauty, and confectionery brand owners increasingly demand differentiated unboxing experiences. In April 2026, Mayr-Melnhof announced expanded rigid luxury box manufacturing capacity at its European converting sites, with the investment including automation and FSC-certified board sourcing upgrades, across the rigid box market. Such capacity investment reflects continued premiumisation as converters pursue differentiated unboxing experiences alongside sustainability-aligned packaging architectures that luxury brand owners increasingly require.
Recently merged global packaging groups continue to invest in decorative finishing and set-up box capacity to strengthen their combined premium packaging portfolios following large-scale industry consolidation. In March 2026, Smurfit WestRock announced fresh investment in its rigid set-up box and folding carton operations across North America, targeting premium consumer goods customers with expanded decorative finishing capacity according to the Wall Street Journal. Such post-merger investment reinforces the combined group's commercial momentum across spirits, electronics, and personal care packaging segments.
Established packaging groups continue to pursue targeted regional plant acquisitions to deepen geographical footprint and strengthen internal paper integration rather than relying solely on organic capacity expansion. In May 2026, Dunapack Packaging agreed to acquire three of Stora Enso's German packaging facilities, generating approximately 74 million euros in 2025 turnover, with the transaction expected to close during 2026 pending merger clearance. Such targeted acquisitions allow acquiring groups to expand their converting footprint with established customer relationships already in place.
Diversified forestry and packaging groups continue to apply sustainability research developed across their broader pulp, paper, and packaging operations to increasingly tailored rigid box product formulations. Mondi plc, headquartered in Weybridge, United Kingdom, continues to develop packaging solutions spanning consumer and industrial applications, drawing on the company's integrated forestry management and pulp production operations. Such vertically integrated raw material access gives diversified forestry groups a cost and sustainability credential advantage that pure converters purchasing paperboard from third parties cannot easily replicate.
Regional rigid box converters continue to compete alongside globally scaled packaging groups by offering closer customer relationships and more customised production runs than larger, more standardised manufacturing operations typically provide. Great Little Box Company Ltd., headquartered in Richmond, British Columbia, Canada, continues to serve regional customers with customised rigid box solutions tailored to smaller production volumes than large multinational converters typically prioritise. Such regional specialisation allows smaller converters to compete against larger groups on responsiveness and customisation rather than manufacturing scale.
This Expert Market Research's report titled "Global Rigid Box Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
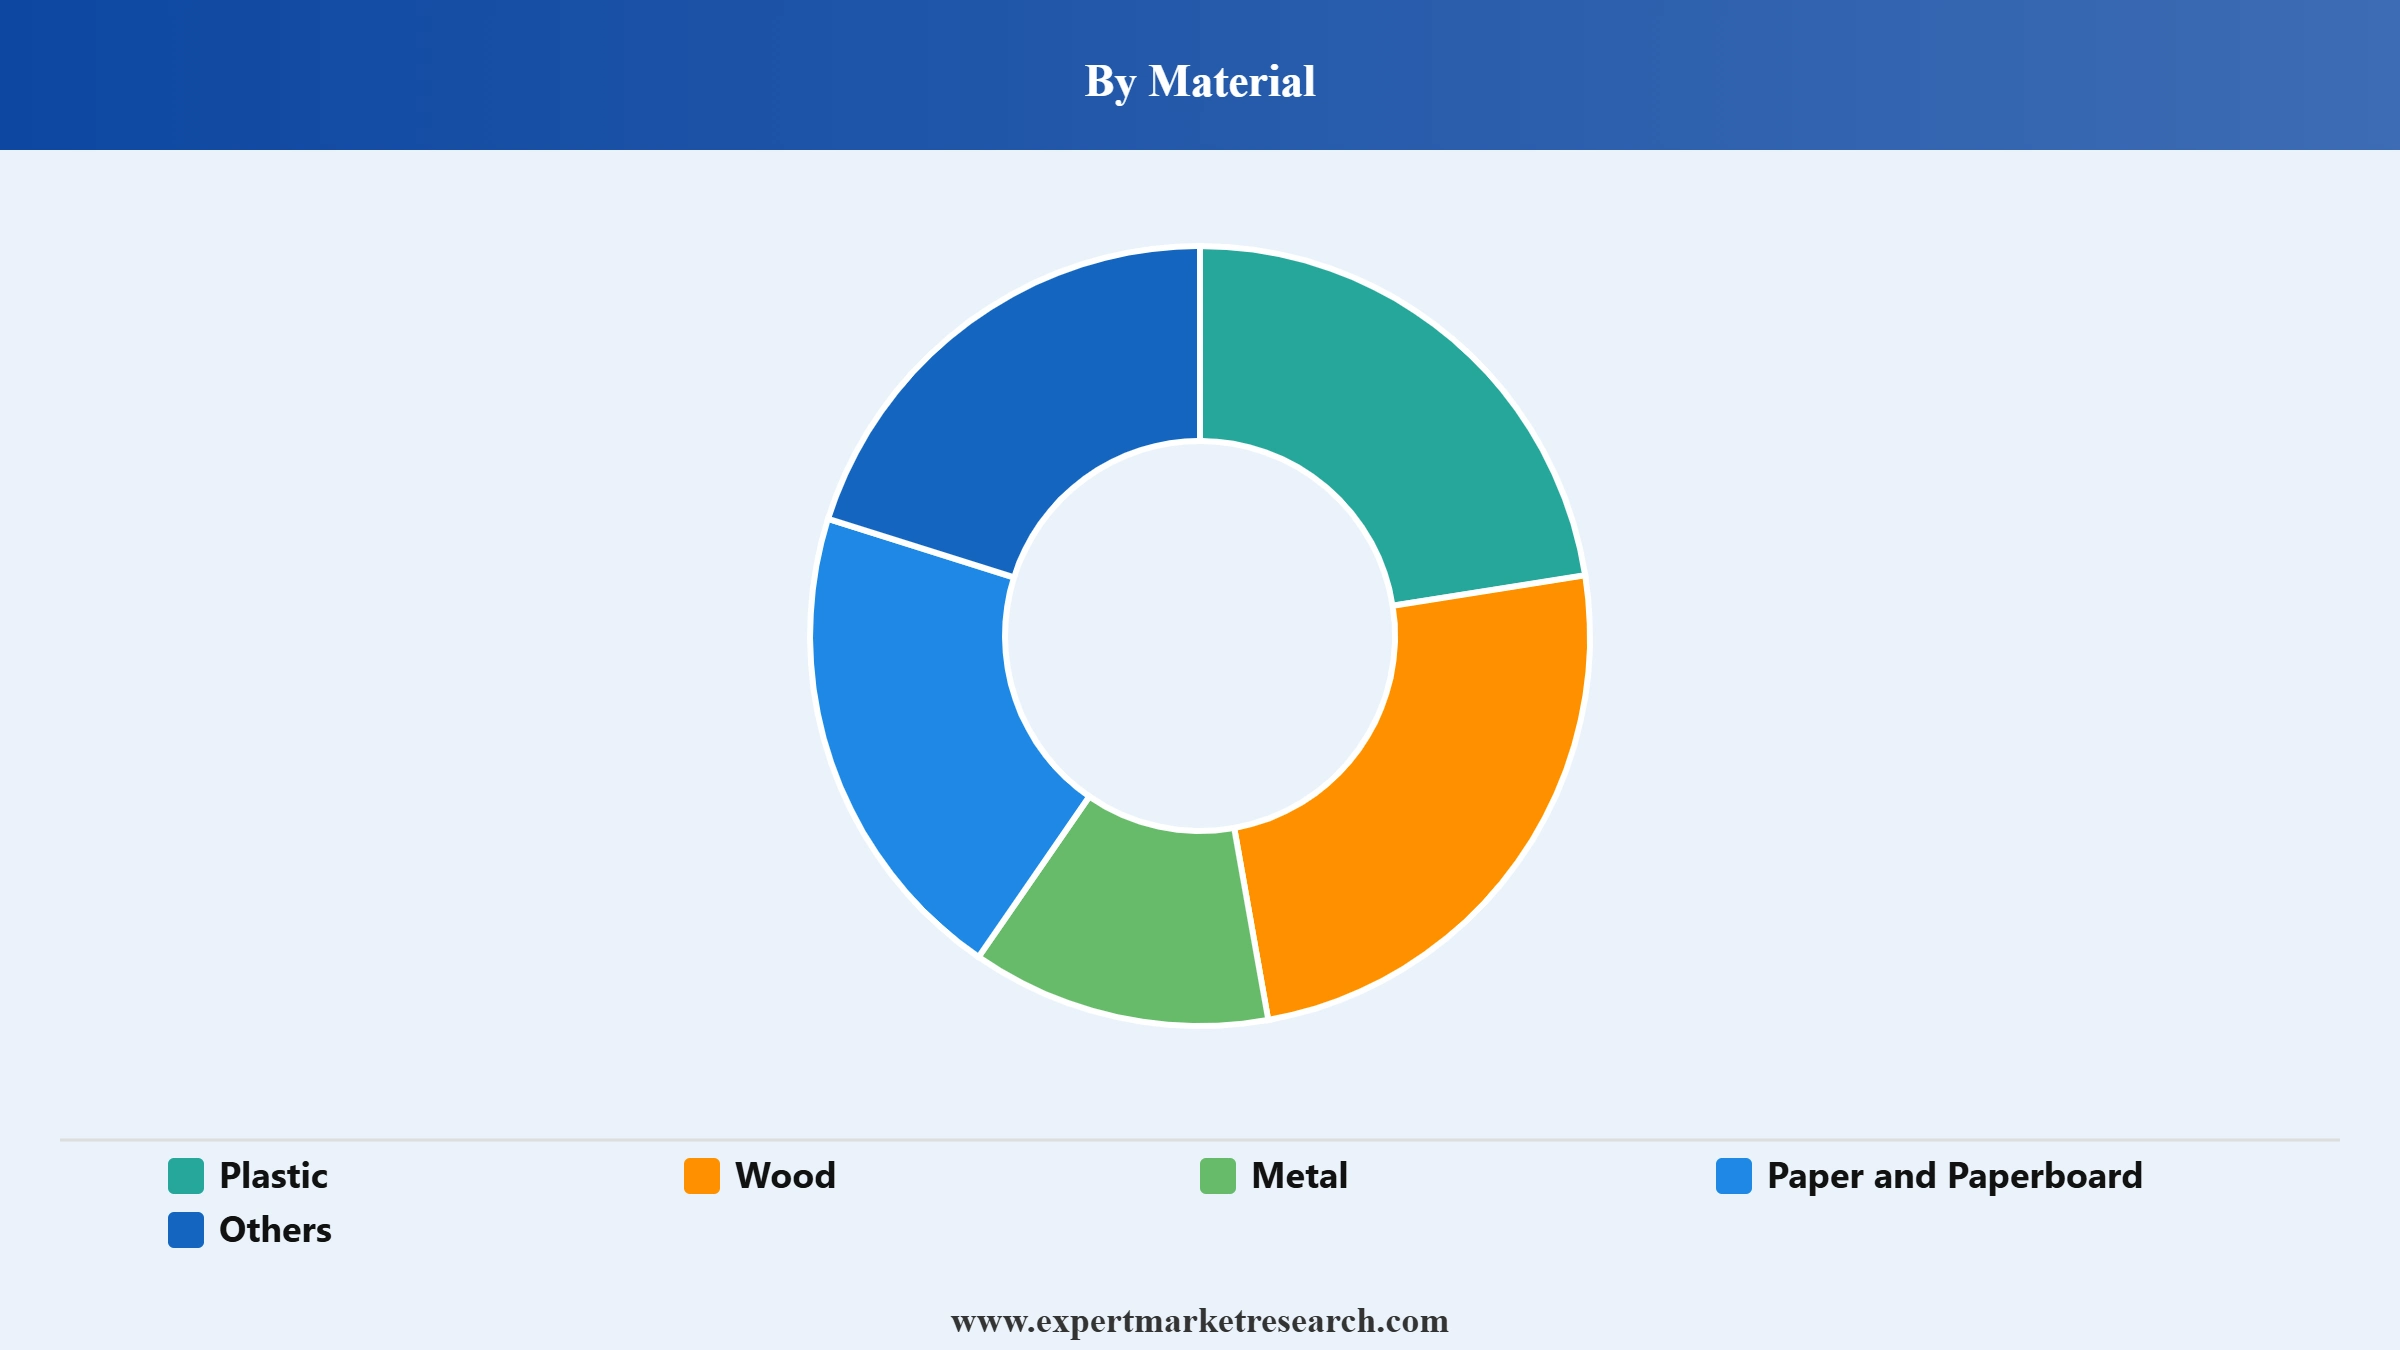
Market Breakup by Material
Key Insight: Paper and paperboard accounts for the largest share of the rigid box market, valued for its recyclability, cost-effectiveness, and broad regulatory acceptance across major consuming regions. Wood is growing at the fastest pace as luxury and premium spirits brands increasingly favour its tactile, high-end presentation qualities for flagship product packaging; in May 2026, Bordeaux-based coffret manufacturer Adam launched a new plot-specific wooden case design combining supply-chain transparency with detailed value-chain mapping for premium wine and spirits customers. Plastic continues to serve applications requiring transparency or specific durability properties, metal serves premium and reusable packaging niches, and other materials round out the remaining specialised category.
Market Breakup by Product Type
Key Insight: Rigid sleeve boxes account for a considerable share of the rigid box market, valued for their premium presentation and straightforward automated assembly compared with more complex hinged or telescopic formats. Collapsible boxes are growing at a fast pace as brand owners seek the premium aesthetic of rigid packaging alongside the shipping and storage efficiency benefits that flat-pack formats provide. Shoulder neck, hinged, telescopic, and two-piece boxes each continue to serve established niches spanning cosmetics, confectionery, and electronics packaging applications with distinct opening and closure requirements; a book-opening hinged design was featured in Diane von Furstenberg's 2026 fiftieth-anniversary campaign packaging, illustrating hinged formats' continued relevance for fashion and luxury brand storytelling.
Market Breakup by End Use
Key Insight: Cosmetics and personal care accounts for the largest end-use share of the rigid box market, reflecting the category's strong emphasis on premium unboxing experiences that reinforce brand positioning. Food and beverages, including premium spirits and confectionery, continue to see strong demand for gift-appropriate rigid packaging formats; in January 2026, Godiva unveiled its Valentine's Day collection featuring heart-shaped rigid gift boxes across multiple assortment sizes as part of the brand's centenary celebrations. Pharmaceuticals require rigid packaging meeting specific tamper-evidence and protection standards, electric and electronics brands increasingly use rigid boxes for premium device packaging, automotive and homecare applications serve smaller specialised niches, and other end uses round out the remaining category.
Market Breakup by Region
Key Insight: North America accounts for the largest share of the rigid box market, supported by advanced packaging technology adoption and strong luxury goods demand across the region's established converting base. Asia Pacific is expected to grow at the fastest pace as rising disposable incomes and expanding luxury retail penetration drive sustained demand across the region's growing middle-class consumer base. In July 2026, Indian converter Miracle Group outlined pan-India expansion plans spanning its rigid packaging and multi-format portfolio at the Indusfood Ahmedabad exhibition, highlighting the region's growing domestic manufacturing capacity. Europe continues to see steady demand supported by stringent EU Circular Economy Action Plan requirements mandating recyclable packaging by 2030, while Latin America and the Middle East and Africa are gradually scaling adoption alongside expanding formal retail infrastructure.
By material, paper and paperboard leads the market given its recyclability and cost-effectiveness
Paper and paperboard continues to account for the largest share of the market, valued for its recyclability, cost-effectiveness, and broad regulatory acceptance across major consuming regions increasingly tightening packaging sustainability requirements. Established paperboard converting operations continue to anchor steady replacement demand as brand owners reformulate existing packaging lines to meet evolving recyclability standards. In May 2026, Metsä Board showcased its Muoto moulded fibre technology at Interpack 2026, a three-dimensional fibre-based packaging concept formed directly from wet wood pulp without intermediate converting steps.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Wood is growing at the fastest pace across the rigid box market as luxury and premium spirits brands increasingly favour its tactile, high-end presentation qualities for flagship product packaging, positioning wood as a premium differentiator against more conventional paperboard formats used across mass-market applications.
By product type, rigid sleeve box leads the market while collapsible box grows fastest given shipping efficiency demands
Rigid sleeve boxes continue to account for a considerable share of the market, valued for their premium presentation and straightforward automated assembly compared with more complex hinged or telescopic formats. Established sleeve box production lines continue to anchor steady demand across cosmetics and premium confectionery packaging applications favouring this straightforward opening mechanism.
Collapsible boxes are growing at a fast pace across the market as brand owners seek the premium aesthetic of rigid packaging alongside the shipping and storage efficiency benefits that flat-pack formats provide, particularly important as e-commerce shipping costs continue to factor heavily into overall packaging format selection decisions. Structural innovation across the category was recognised in January 2026, when Mondi received nine WorldStar Global Packaging Awards, the industry's most prestigious accolade, for paper-based packaging solutions spanning multiple product formats.
By end use, cosmetics and personal care leads the market given the category's emphasis on premium unboxing experiences
Cosmetics and personal care continues to account for the largest end-use share of the market, reflecting the category's strong emphasis on premium unboxing experiences that reinforce brand positioning at the critical moment of first product interaction. Established cosmetics packaging relationships continue to anchor steady replacement demand as brands maintain consistent packaging partnerships across product line refreshes.
Food and beverages, including premium spirits and confectionery, continue to see strong demand across the rigid box market for gift-appropriate rigid packaging formats, particularly during peak holiday and gifting seasons when premium presentation becomes a more significant purchasing consideration than standard product periods.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
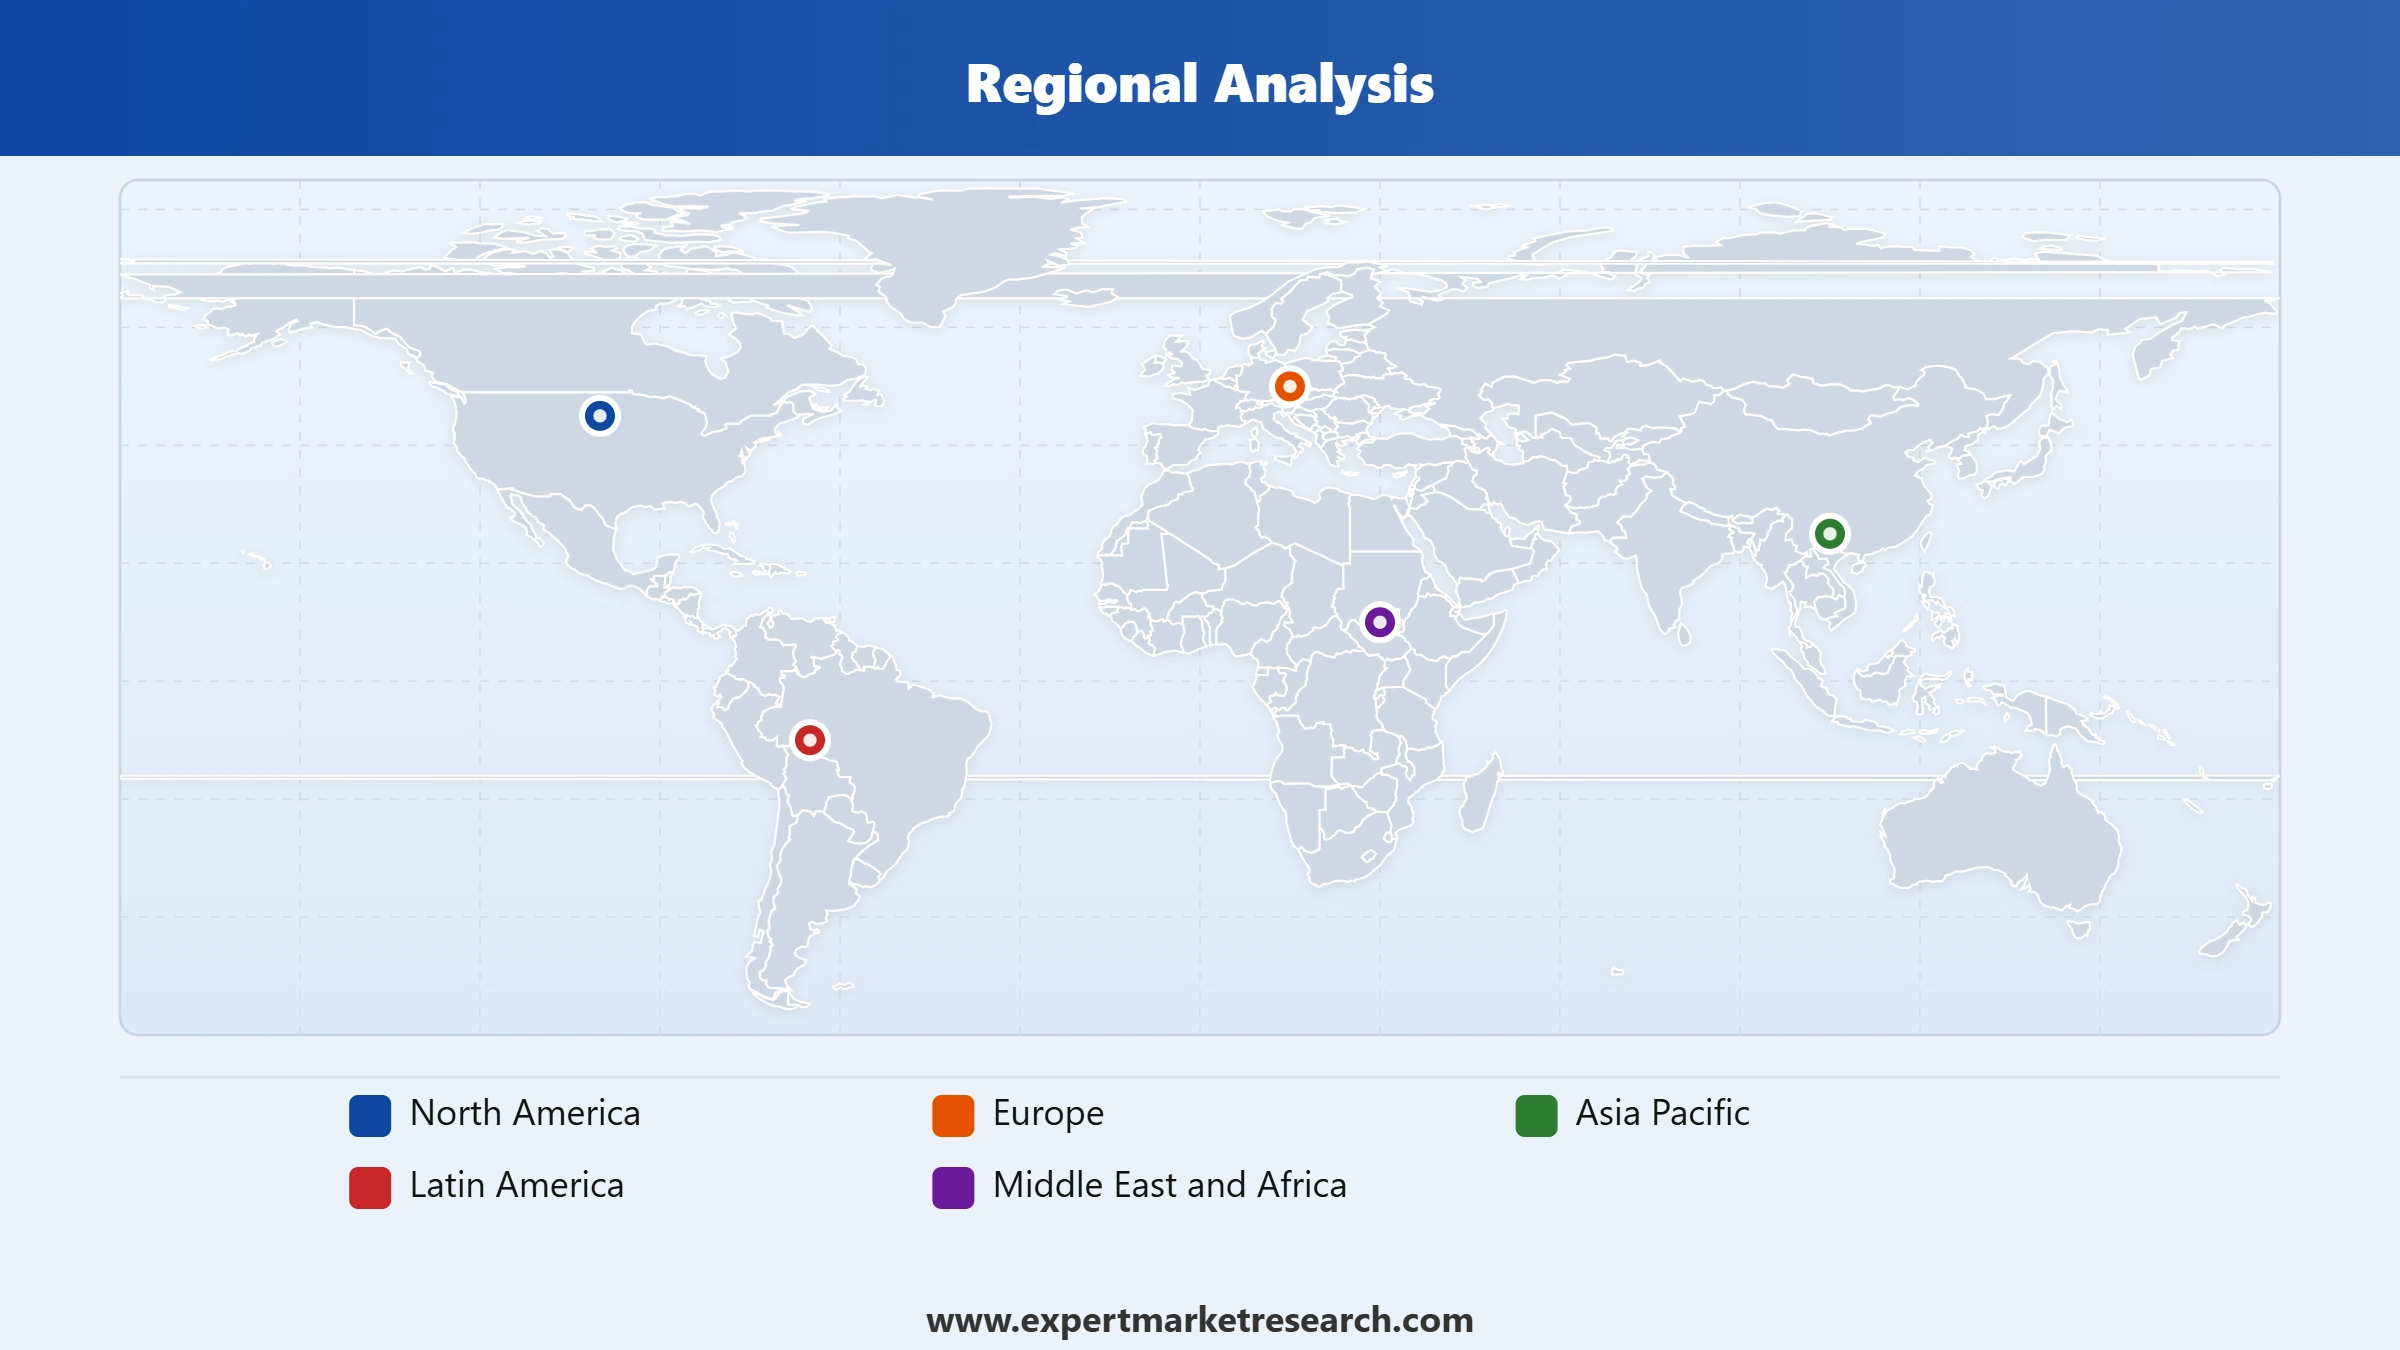
North America commands the largest share of the market through advanced packaging technology and strong luxury goods demand
North America holds the largest share of the rigid box market, supported by advanced packaging technology adoption and strong luxury goods demand across the region's established converting base. In September 2025, Georgia-Pacific announced an agreement to acquire Anchor Packaging, a specialist in rigid food containers, complementing its existing Dixie tableware products business and reinforcing the region's position as a hub for rigid packaging consolidation.
Asia Pacific is expected to grow at the fastest pace as rising disposable incomes and expanding luxury retail penetration drive sustained demand across the region's growing middle-class consumer base. Regional converters are increasingly investing in automated finishing capacity to serve this growing demand base directly, reducing reliance on imported premium packaging from established European and North American manufacturing hubs. In January 2026, Chinese converter Jihong Group started up a 45 million US dollar facility in the United Arab Emirates, its first Middle East site, illustrating growing Asian converters' ambitions to serve premium packaging demand well beyond their home markets.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The global industry is moderately consolidated, with rigid box companies ranging from vertically integrated forestry and packaging groups spanning multiple product platforms to specialist regional converters competing across material, product type, and end-use segments. Established players operate across the full rigid box value chain, from paperboard and forestry sourcing through converting, decorative finishing, and complete rigid packaging manufacturing for luxury, cosmetics, and consumer goods customers.
Competitive dynamics among rigid box players are increasingly shaped by the pace of large-scale industry consolidation, the scale of decorative finishing and automation investment, and the race to secure FSC-certified sustainable board sourcing meeting tightening regulatory requirements. Manufacturers are investing in expanded luxury packaging capacity, targeted regional plant acquisitions, and vertically integrated raw material access to differentiate their offering and secure long-term brand owner relationships.
Founded in 1898 and headquartered in Memphis, Tennessee, United States, International Paper supplies paperboard-based rigid packaging solutions alongside a vastly larger global paper and packaging business spanning containerboard and pulp production. As the world's largest paper and packaging company by revenue, the company maintains substantial vertically integrated raw material access supporting its rigid box converting operations. International Paper's scale advantages in pulp and paperboard production provide cost and supply security benefits that smaller specialist converters typically cannot replicate.
Founded in 1934 and headquartered in Espoo, Finland, Metsä Group supplies paperboard and packaging materials through its Metsä Board division, alongside a broader forestry, pulp, and tissue products business built on sustainable Nordic forest management. The company's cooperative ownership structure, rooted in Finnish forest owner membership, differentiates its governance model from publicly traded competitors. Metsä Group's integrated forestry-to-packaging value chain supports strong sustainability credentials increasingly demanded by premium brand owner customers.
Founded in 1967 and headquartered in Weybridge, United Kingdom, Mondi supplies rigid packaging solutions alongside a broader portfolio spanning pulp production, forest management, and industrial packaging materials including plastic films. The company's combined forestry management and packaging manufacturing operations provide vertically integrated raw material access from managed forests through finished packaging products. Mondi's diversified material science expertise, spanning both paper and plastic film technology, allows it to serve customers across multiple rigid box material preferences.
Founded in 1934 and headquartered in Dublin, Ireland, Smurfit Kappa supplies rigid and corrugated packaging solutions, now operating as Smurfit WestRock following its major merger with WestRock Company, combining European and North American packaging manufacturing operations. The company's substantially expanded post-merger scale positions it among the largest global packaging groups by combined manufacturing footprint. Smurfit WestRock's integrated European and North American operations provide geographic diversification that smaller regional converters cannot match.
Other key players in the rigid box market include Great Little Box Company Ltd., Packaging Bee, Stora Enso Oy, Schwarz Partners Packaging, LLC., Georgia-Pacific LLC, and Synergic Impressions Pvt Ltd, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our rigid box market trends 2026 report. Discover regional growth patterns, material and end-use trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$3999 $3599
$2499 $2249
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The market is projected to grow at a CAGR of 4.90% between 2026 and 2035.
Expanding dedicated luxury packaging manufacturing capacity, investing in decorative finishing technology following major industry consolidation, and pursuing targeted regional plant acquisitions to deepen geographical footprint and paper integration.
The key trends fuelling the growth of the market include rising popularity of luxury rigid boxes, expansion of the e-commerce sector, and increasing use of rigid boxes for promotions.
The significant product types of rigid boxes in the market are shoulder neck box, rigid sleeve box, hinged box, telescopic box, two-piece box, and collapsible box.
The various end uses of rigid boxes in the market include cosmetics and personal care, pharmaceuticals, food and beverages, automotive, homecare, and electric and electronics, among others.
The various materials of rigid boxes in the market are plastic, wood, metal, and paper and paperboard, among others.
The major regions in the market are North America, Europe, the Asia Pacific, Latin America, and the Middle East and Africa.
The key players in the market include International Paper, Metsä Group, Mondi plc, Smurfit Kappa Group, Great Little Box Company Ltd., Packaging Bee, Stora Enso Oy, Schwarz Partners Packaging, LLC., Georgia-Pacific LLC, and Synergic Impressions Pvt Ltd, among others.
In 2025, the market reached an approximate value of USD 85.23 Billion.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach about USD 137.51 Billion by 2035.
Converters face rising raw material costs for FSC-certified and sustainable paperboard, the technical complexity of integrating decorative finishing capacity following large-scale mergers, and tightening EU Circular Economy Action Plan requirements mandating fully recyclable packaging materials by 2030.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Material |
|
| Breakup by Product Type |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




