

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
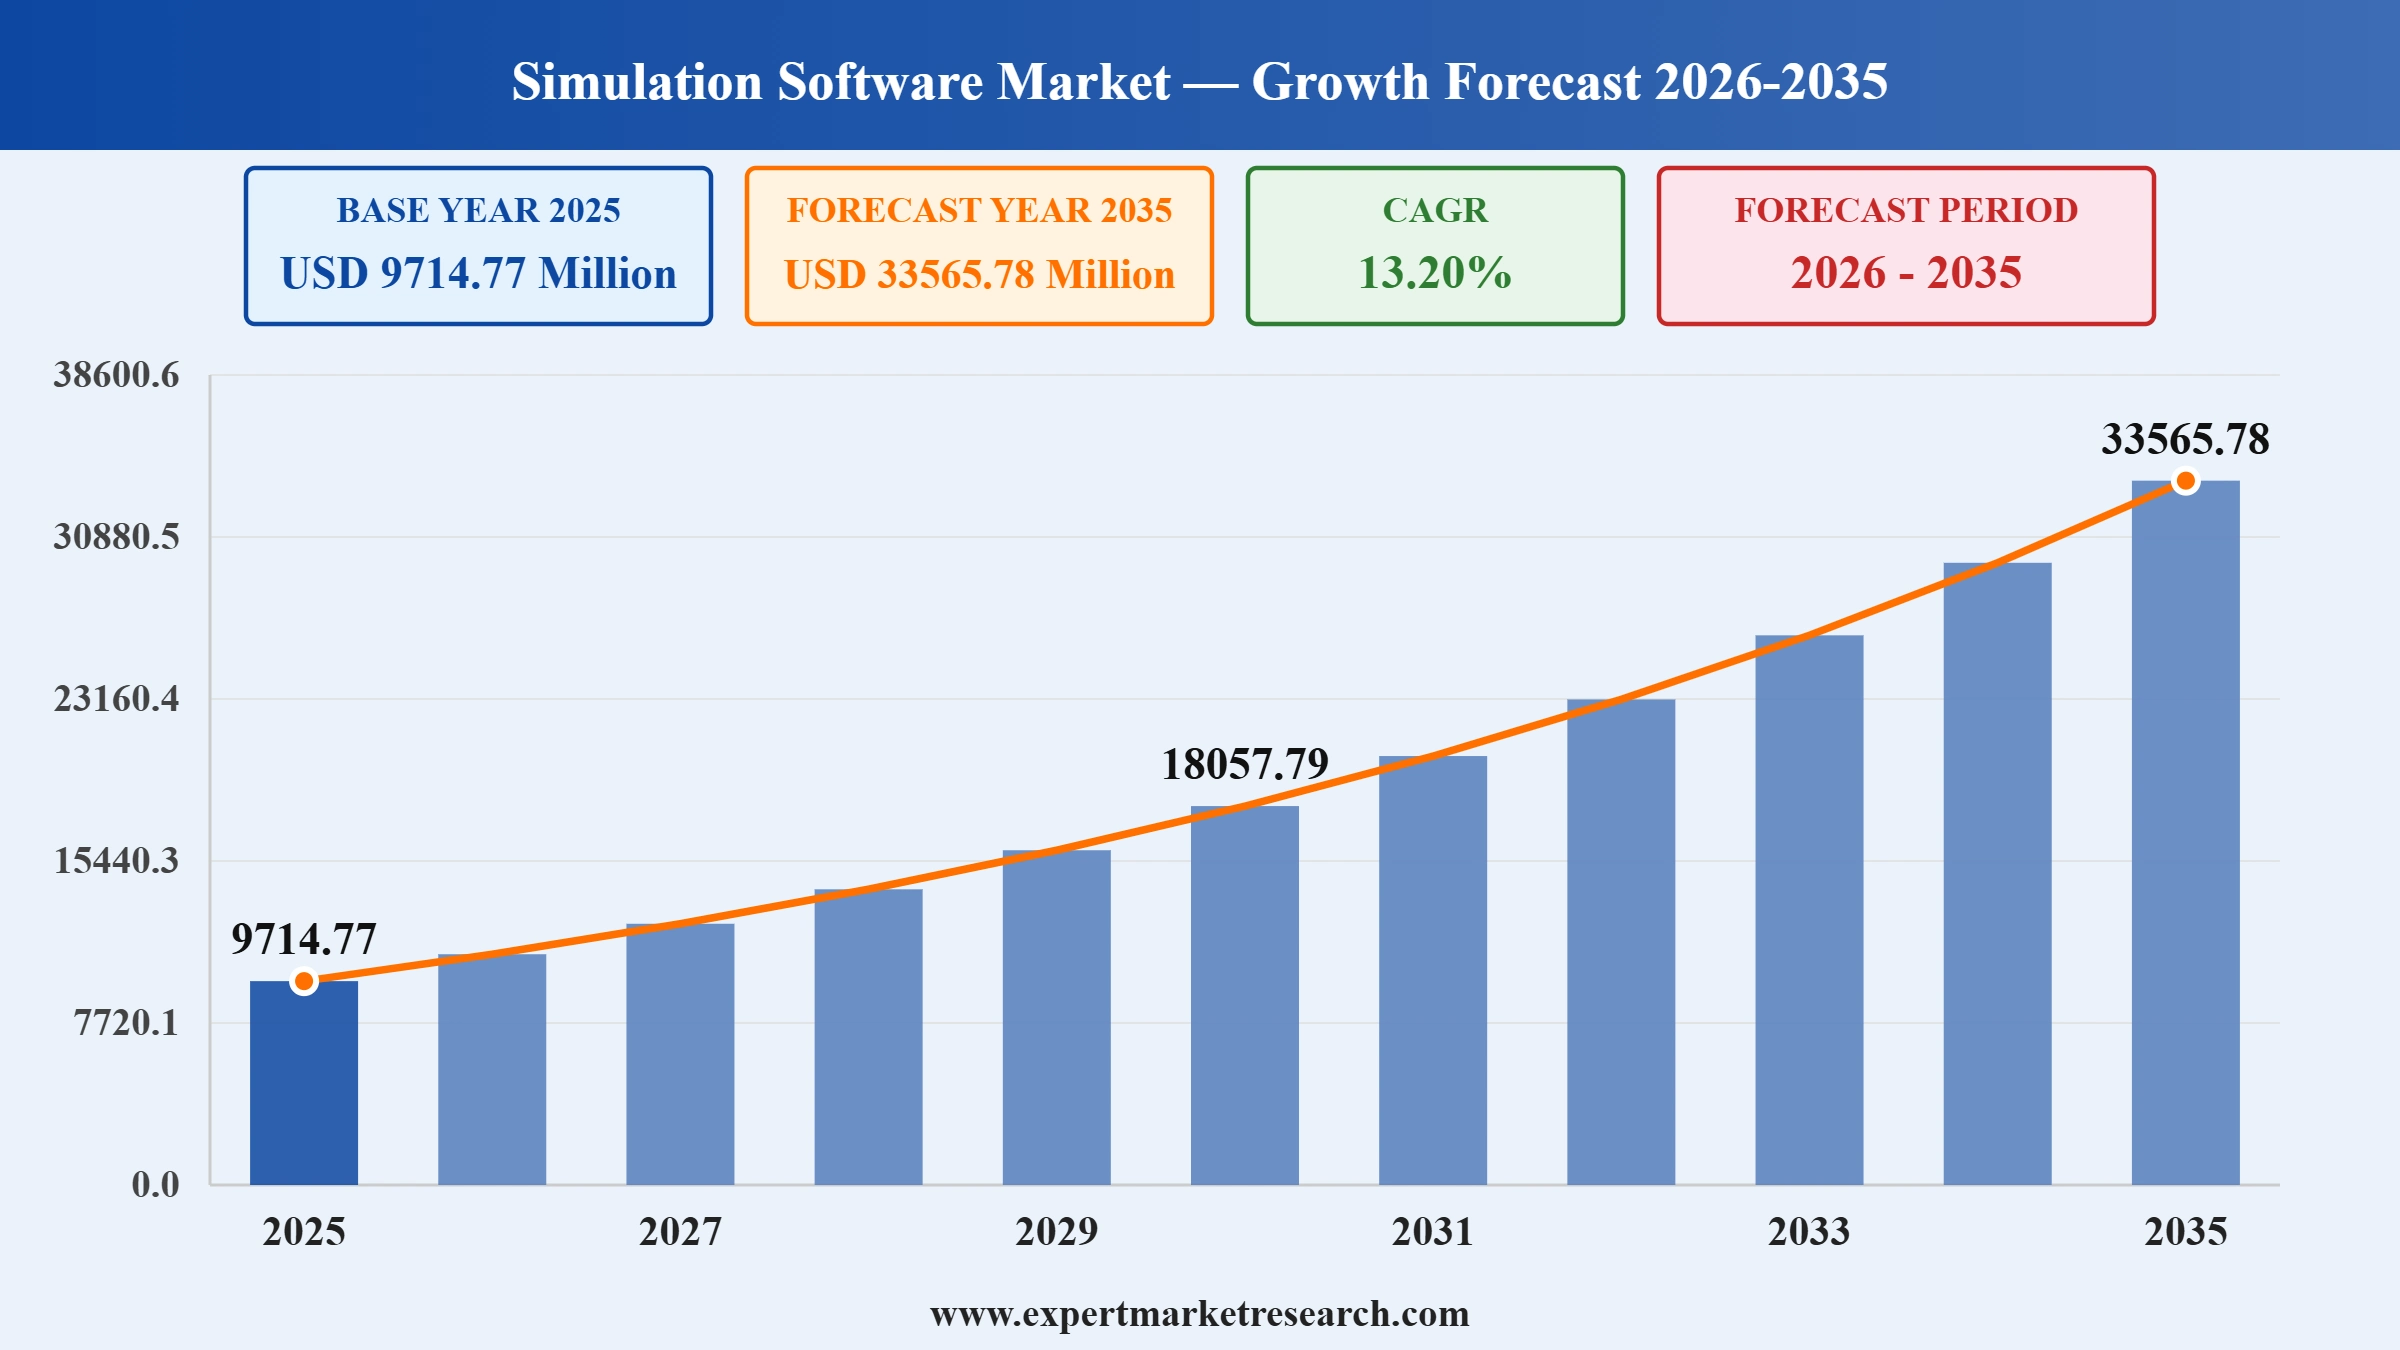
The simulation software market attained a value of USD 9714.77 Million in 2025 and is projected to expand at a CAGR of 13.20% through 2035. The market is further expected to achieve USD 33565.78 Million by 2035. The increased incorporation of real-time digital twins running simulations connected with IoT data streams is pursuing the capacity to predict decisions, limit the risk of operations, and increase the accuracy of the design in industrial environments.
The simulation software market covers tools that apply numerical methods to predict how a product or system will behave under specified physical conditions, spanning structural, thermal, fluid, electromagnetic and multiphysics analysis. These tools allow designs to be evaluated and refined virtually before physical prototypes are built or production equipment is committed, and they extend into system-level modelling where mechanical behaviour, electronic function and embedded software interact.
What has changed the character of this market is that simulation is no longer a verification step performed near the end of design. Products have become too complex to validate physically within commercial timescales, and artificial intelligence has compressed solve times to the point where engineers can explore hundreds of configurations during concept development rather than checking a handful of candidates after the architecture is fixed. That shift moves simulation from a cost centre attached to testing into design infrastructure that shapes how engineering budgets are allocated.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
| Simulation Software Market Report Summary | Description | Value |
| Base Year | USD Million | 2025 |
| Historical Period | USD Million | 2019-2025 |
| Forecast Period | USD Million | 2026-2035 |
| Market Size 2025 | USD Million | 9714.77 |
| Market Size 2035 | USD Million | 33565.78 |
| CAGR 2019-2025 | Percentage | XX% |
| CAGR 2026-2035 | Percentage | 13.20% |
| CAGR 2026-2035 - Market by Region | Asia Pacific | 13.9% |
| CAGR 2026-2035 - Market by Country | USA | 13.6% |
| CAGR 2026-2035 - Market by Country | UK | 13.5% |
| CAGR 2026-2035 - Market by Deployment Type | Cloud | 14.1% |
| CAGR 2026-2035 - Market by End User | IT and Telecommunication | 14.6% |
| Market Share by Country 2025 | Australia | 2.5% |
Regulatory pressure and sustainability considerations are major factors behind the broader utilization of simulation software. Many governments are pushing for virtual testing as a means to cut down on the waste of physical prototyping. Simultaneously, businesses are leveraging simulation to find ways to reduce their energy consumption, accelerating the simulation software market value. These two factors are enhancing the necessity of simulation tools and even driving their adoption in sectors that were previously considered reluctant to advanced digital solutions.
In January 2025, NVIDIA expanded its Omniverse platform with generative physical AI models and blueprints, enabling faster 3D world creation, synthetic data generation, and scalable simulation for robotics applications. The platform has now become a tool for manufacturers to run simulations of entire production lines even before physically setting them up. United States National Institute of Standards and Technology claims that simulation-driven digital twins have the potential to shrink product development time to a significant extent. This trend in the simulation software market is encouraging firms to invest in simulation at earlier stages not only as testing tools, but as main design infrastructure, influencing the way engineering budgets are distributed across the industries.
Moreover, simulation software is now being integrated within the product lifecycle management, supply chain modeling, and even workforce training programs. Organizations no longer view simulation solely as a backend validation tool. Instead, it is becoming a front-end decision-making asset, enabling scenario analysis before capital commitments are made. In March 2026, Greensea launched Bayonet training simulator with physics-based virtual environment, enabling realistic mission rehearsal, operator skill development, and integration with autonomous underwater vehicle systems. Vendors are reacting by delivering cloud-native simulation platforms through which geographically distributed teams can collaborate in real time. This simulation software market trend is making the enterprises rethink their approaches toward risk and design validation.
Synopsys filed second quarter fiscal 2026 results on 27 May 2026 showing revenue of USD 2.276 billion, up 42 percent year on year, with the Ansys acquisition contributing USD 652.4 million, alongside a backlog of approximately USD 11.0 billion, six-month operating cash flow of USD 1.486 billion, and charges including USD 403.6 million in amortisation of acquired intangibles and USD 115.9 million in restructuring. Simulation vendors can pursue integration with adjacent design disciplines to expand addressable engineering spend.
Synopsys released Ansys 2026 R1 on 12 March 2026 introducing GeomAI for generative geometry exploration, a Mesh Agent in Ansys Mechanical that identifies and resolves meshing problems, a Discovery Validation Agent verifying simulation setup, SimAI Premium software as a service alongside SimAI Pro desktop, expanded Engineering Copilot availability, and TwinAI combining simulation with sensor and test data. Vendors can automate the setup and meshing work that historically consumed a substantial share of engineer time.
The Ansys 2026 R1 release delivered the first integrated capabilities across the combined Synopsys and Ansys portfolios, connecting VC Functional Safety Manager with medini analyze for automotive and aerospace safety analysis, QuantumATK with Granta MI for materials data management, OptoCompiler with Lumerical FDTD for photonic design, and SCADE with TPT for embedded control system testing, alongside AVxcelerate Sensors with GPU acceleration and NVIDIA Omniverse integration. Suppliers can position workflow continuity rather than individual solver capability as the competitive differentiator.
Altair released HyperWorks 2026 on 8 December 2025 following its acquisition by Siemens, applying geometric deep learning, generative algorithms and GPU-accelerated reduced order modelling to produce physics-based predictions reported at up to 1,000 times faster than traditional simulation in secure browser environments, with electromagnetic simulations 40 percent faster, enterprise-scale batch meshing and assembly handling, and JetZero applying its FlightStream module to blended wing aircraft development targeting 50 percent fuel efficiency improvement. Vendors can deliver solver-class accuracy without high-performance computing prerequisites.
Digital twins are evolving from research support tools into integral components of industrial operations. Siemens Digital Industries Software, for example, is one of the companies on the forefront of this development in the simulation software market. They enable the online simulation of factories and at the same time, give operators the possibility to test changes without interrupting production. The European Commission, through its industrial digitization programs, has facilitated the use of digital twin technology by manufacturers, so that they can increase the level of efficiency as well as the environmental sustainability of their production processes. Aligning with this trend, in the healthcare sector, in March 2026, L&T Technology Services launched NVIDIA-powered AI lung digital twin platform enabling 3D visualization, real-time simulation, improved diagnostic accuracy, and enhanced bronchoscopy planning for respiratory care.
Deployment of simulation software through the cloud is reshaping the simulation software market dynamics. Firms like Autodesk, Inc. have increased the number of cloud simulation tools so that a wider group of engineers is able to run even the most complicated simulation scenarios without having to rely on their own computers. In March 2026, Synopsys launched a digital twin platform enabling cloud-based virtual prototyping, early software development, and collaborative system validation before hardware availability, accelerating engineering workflows significantly.
Artificial intelligence is becoming standard in simulation technology, enabling automated design generation and identification of optimal solutions. ANSYS, Inc. offers simulation solutions enhanced by AI, boosting demand in the simulation software market. Moreover, the United States Department of Energy has pinpointed AI-based engineering simulation as a means to boost innovation in energy systems. In March 2026, Aesthetic Record integrated EntityMed AI simulation platform enabling real-time treatment visualization, automated lead capture, improved patient engagement, and seamless workflow integration for aesthetic practices.
Simulation technology within healthcare is becoming increasingly prominent for drug development and medical device testing. Dassault Systmes SE is recognized for its virtual human models helping clinical research. Regulatory bodies such as the FDA are increasingly accepting simulation data for approval, driving adoption and accelerating growth in the simulation software market. This signifies doing fewer physical experiments, leading to savings of both time and cost. In March 2026, Surgical Science upgraded endometriosis ultrasound simulator with advanced training modules, enabling structured learning, improved diagnostic accuracy, and realistic case-based simulation for clinical skill development.
Governments encourage the use of simulations as a way of achieving sustainability goals. The Green Deal of the European Union motivates the industry to cut down on emissions. Companies like Altair Engineering Inc. are working on solutions that maximize natural resources and at the same time, minimize wastage. Many firms in the simulation software market leverage simulation to evaluate environmentally friendly designs prior to the manufacturing stage. For example, in August 2025, KBC launched Petro-SIM 7.6 with AI/ML integration, enabling advanced digital twin simulation, improved process optimization, reduced emissions, and enhanced decision-making across energy and petrochemical operations.
The Expert Market Research's report titled “Simulation Software Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Deployment Type
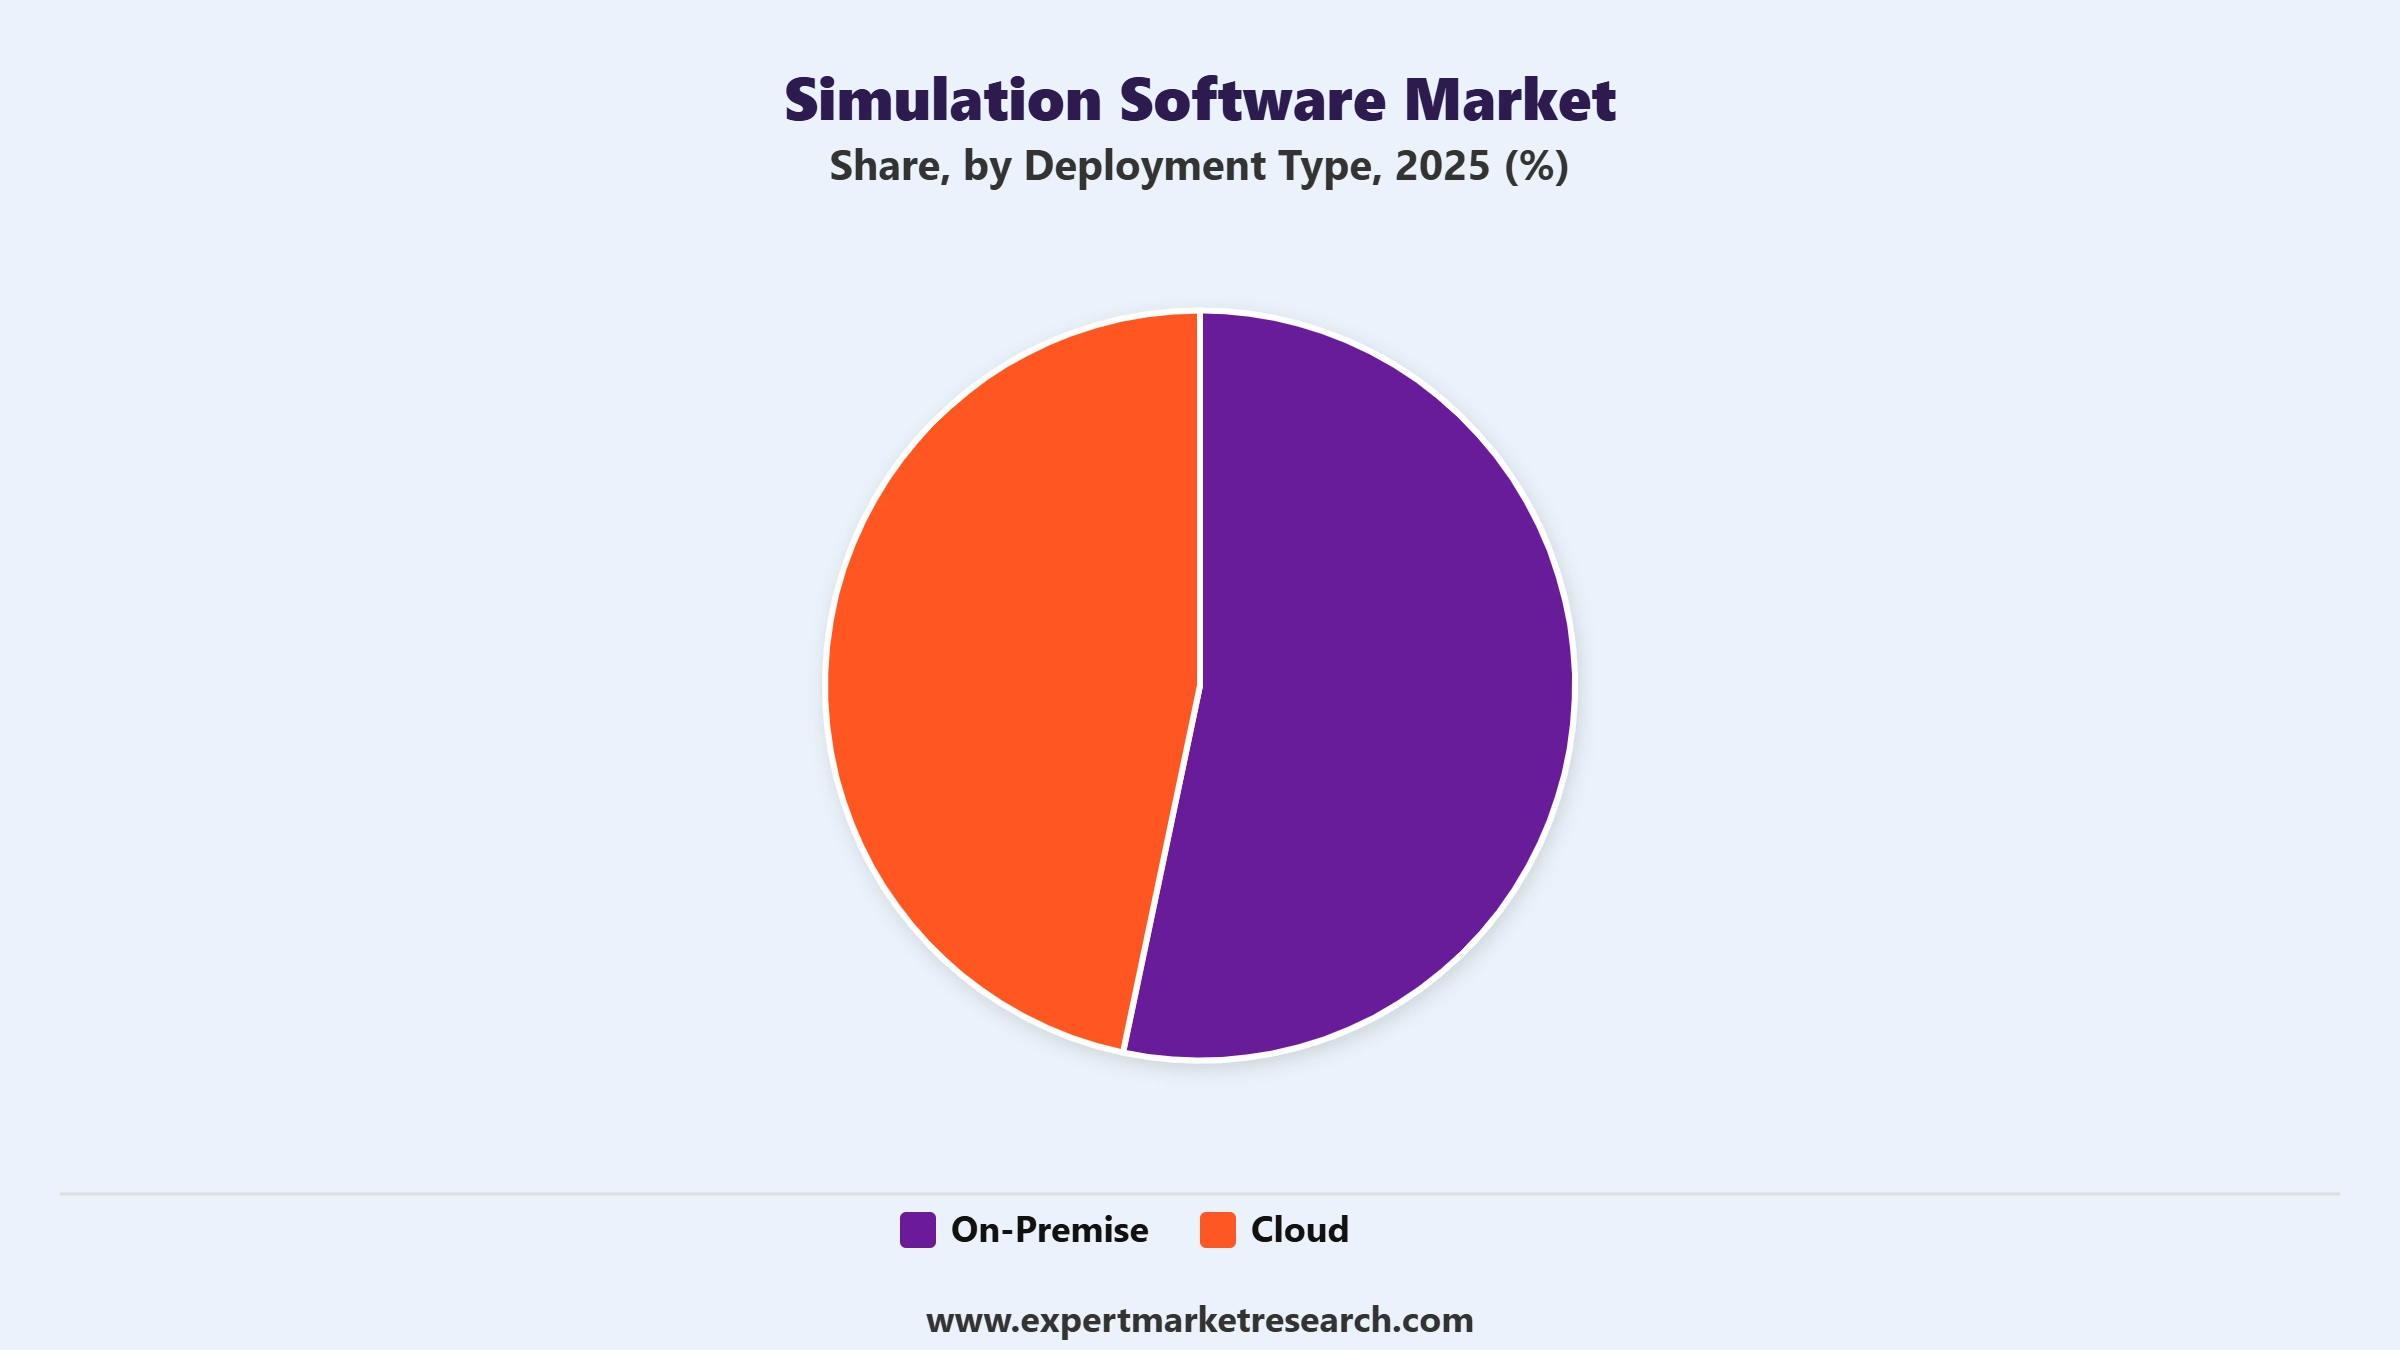
Key Insight: On-premises deployment continues to dominate the simulation software market scope especially where data control and compliance are key, for example, in regulated industries. However, cloud deployment is becoming more popular as it provides flexible scaling and easier collaboration. In March 2026, CoreWeave advanced AI native cloud platform with integrated infrastructure, flexible capacity, and optimized orchestration, enabling scalable, production-ready AI deployment across complex enterprise workloads. This combination provides operational flexibly without sacrificing security. To make it easier for companies who are experimenting with cloud capabilities, vendors are providing interoperable platforms that support both environments.
Market Breakup by End Use
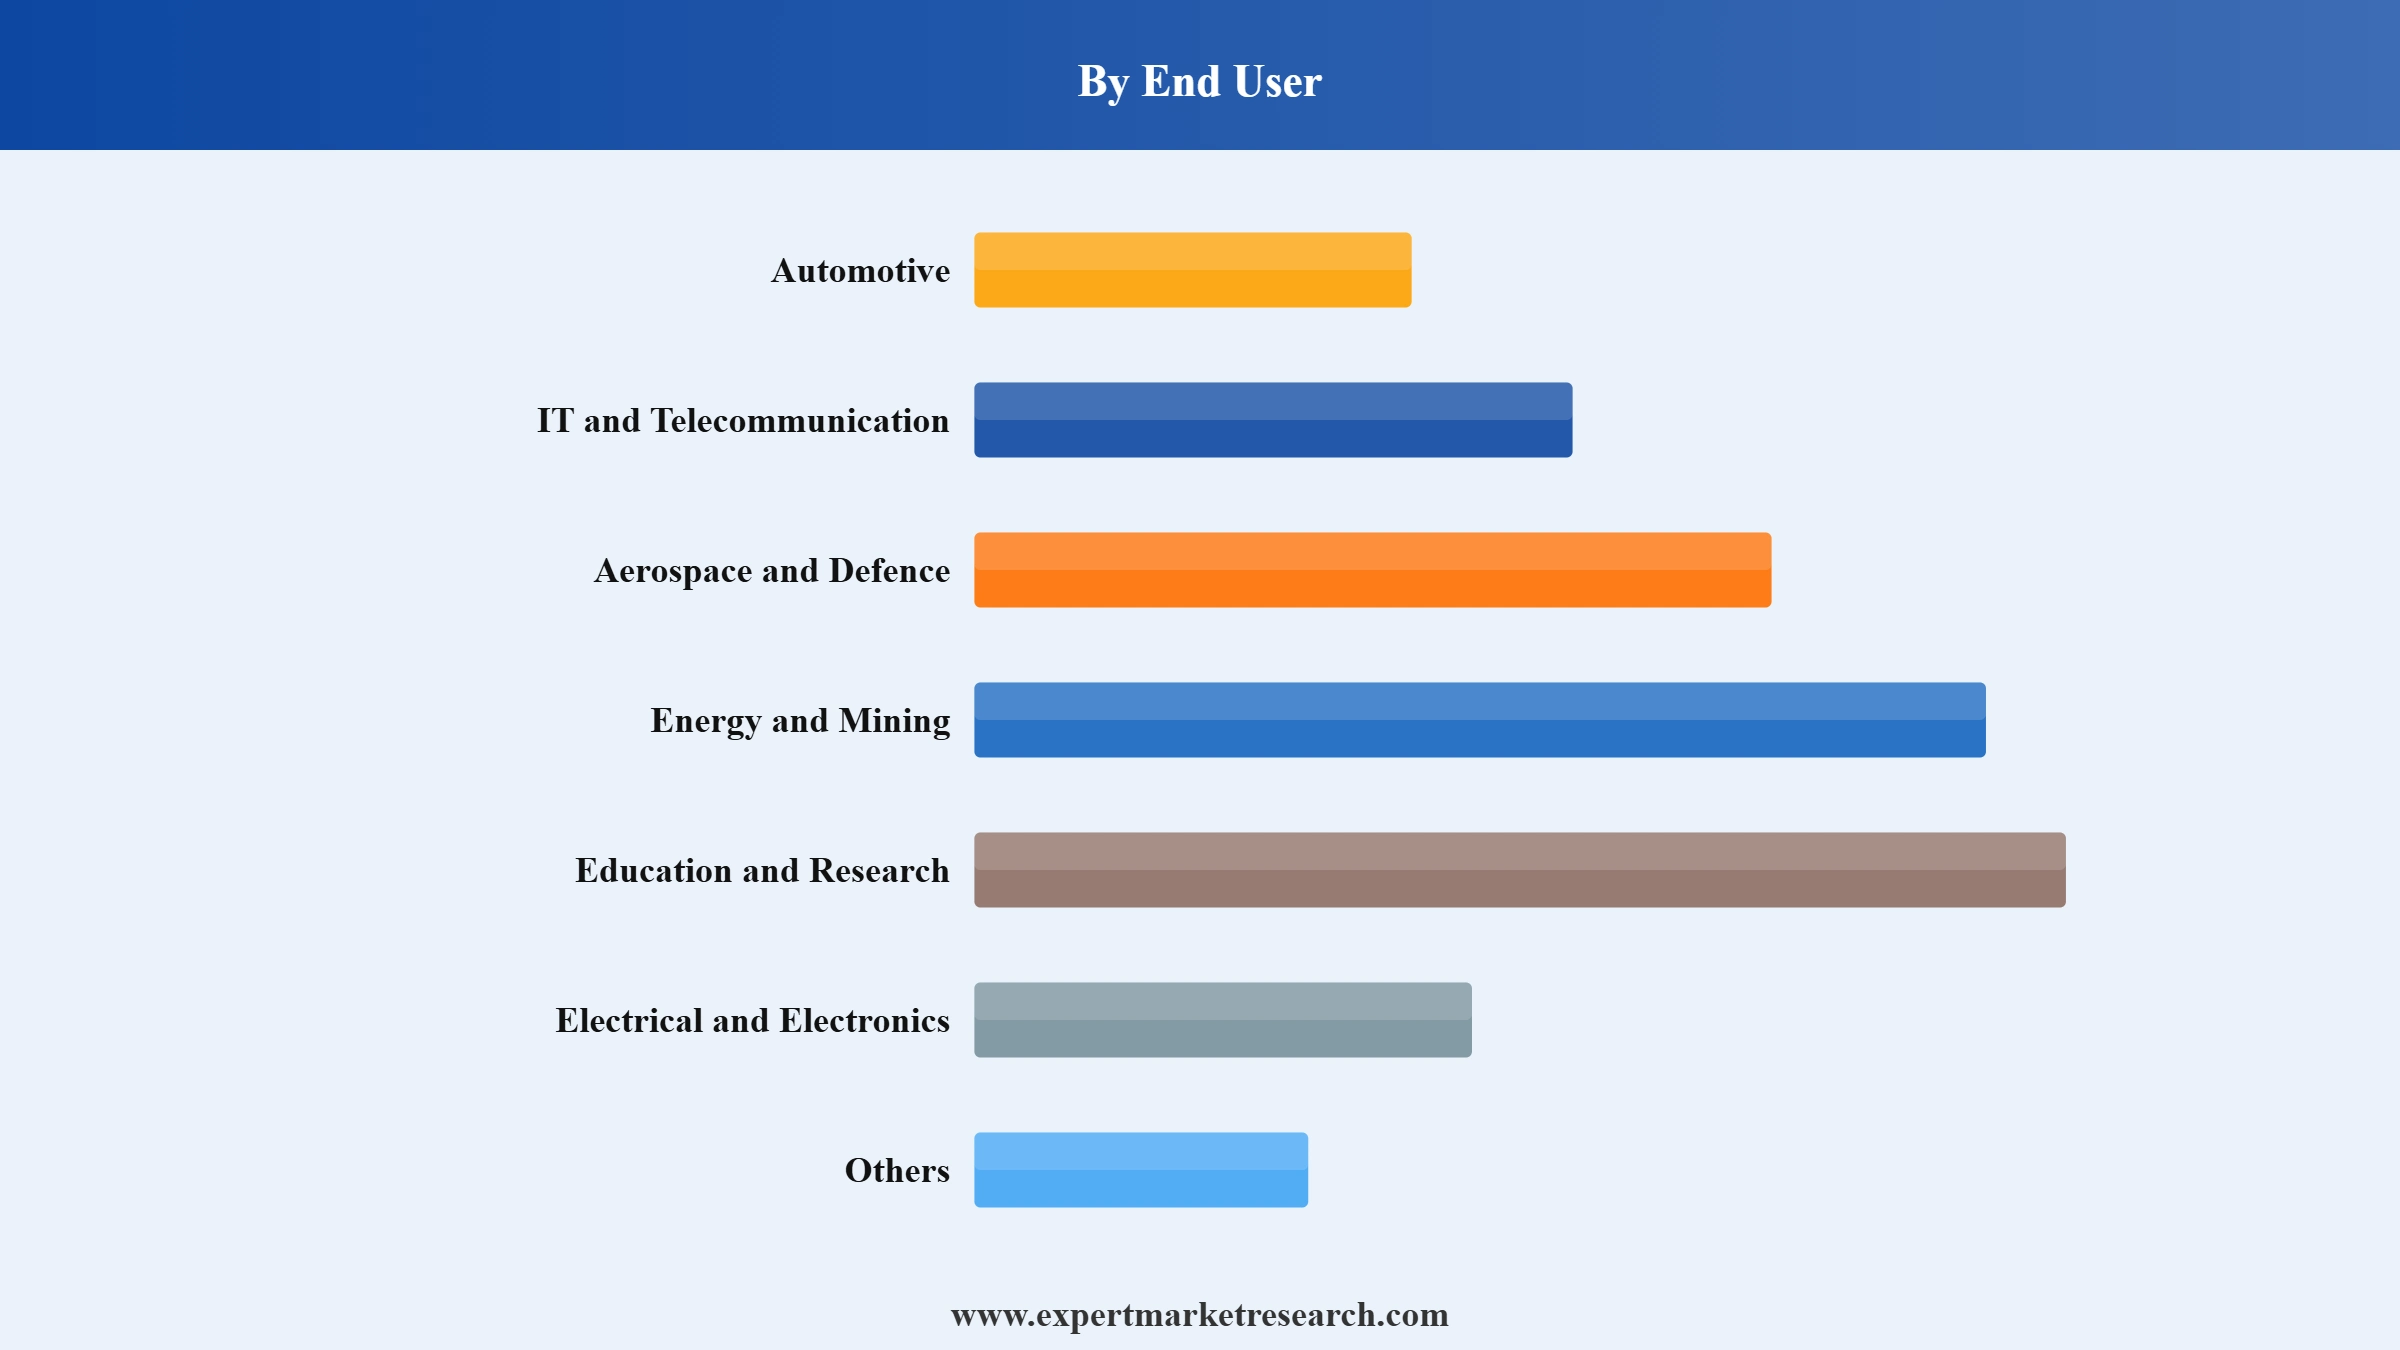
Key Insight: The automotive industry leads the simulation software market growth because of constant needs for designing and testing, while aerospace and defense sectors are expanding their markets shares owing to precision-driven requirements. In January 2026, Joby deployed CAE flight simulators delivering high-fidelity training environments, supporting FAA certification and enabling scalable pilot training capacity of up to 250 annually. IT and telecommunication sectors are implementing simulation for network modeling and infrastructure planning. Energy and mining industries depend on simulation for operational safety and efficiency improvements. Education and research institutions are employing these tools for advanced studies and innovation projects. Electrical and electronics companies use simulation for circuit design and thermal management.
Market Breakup by Region
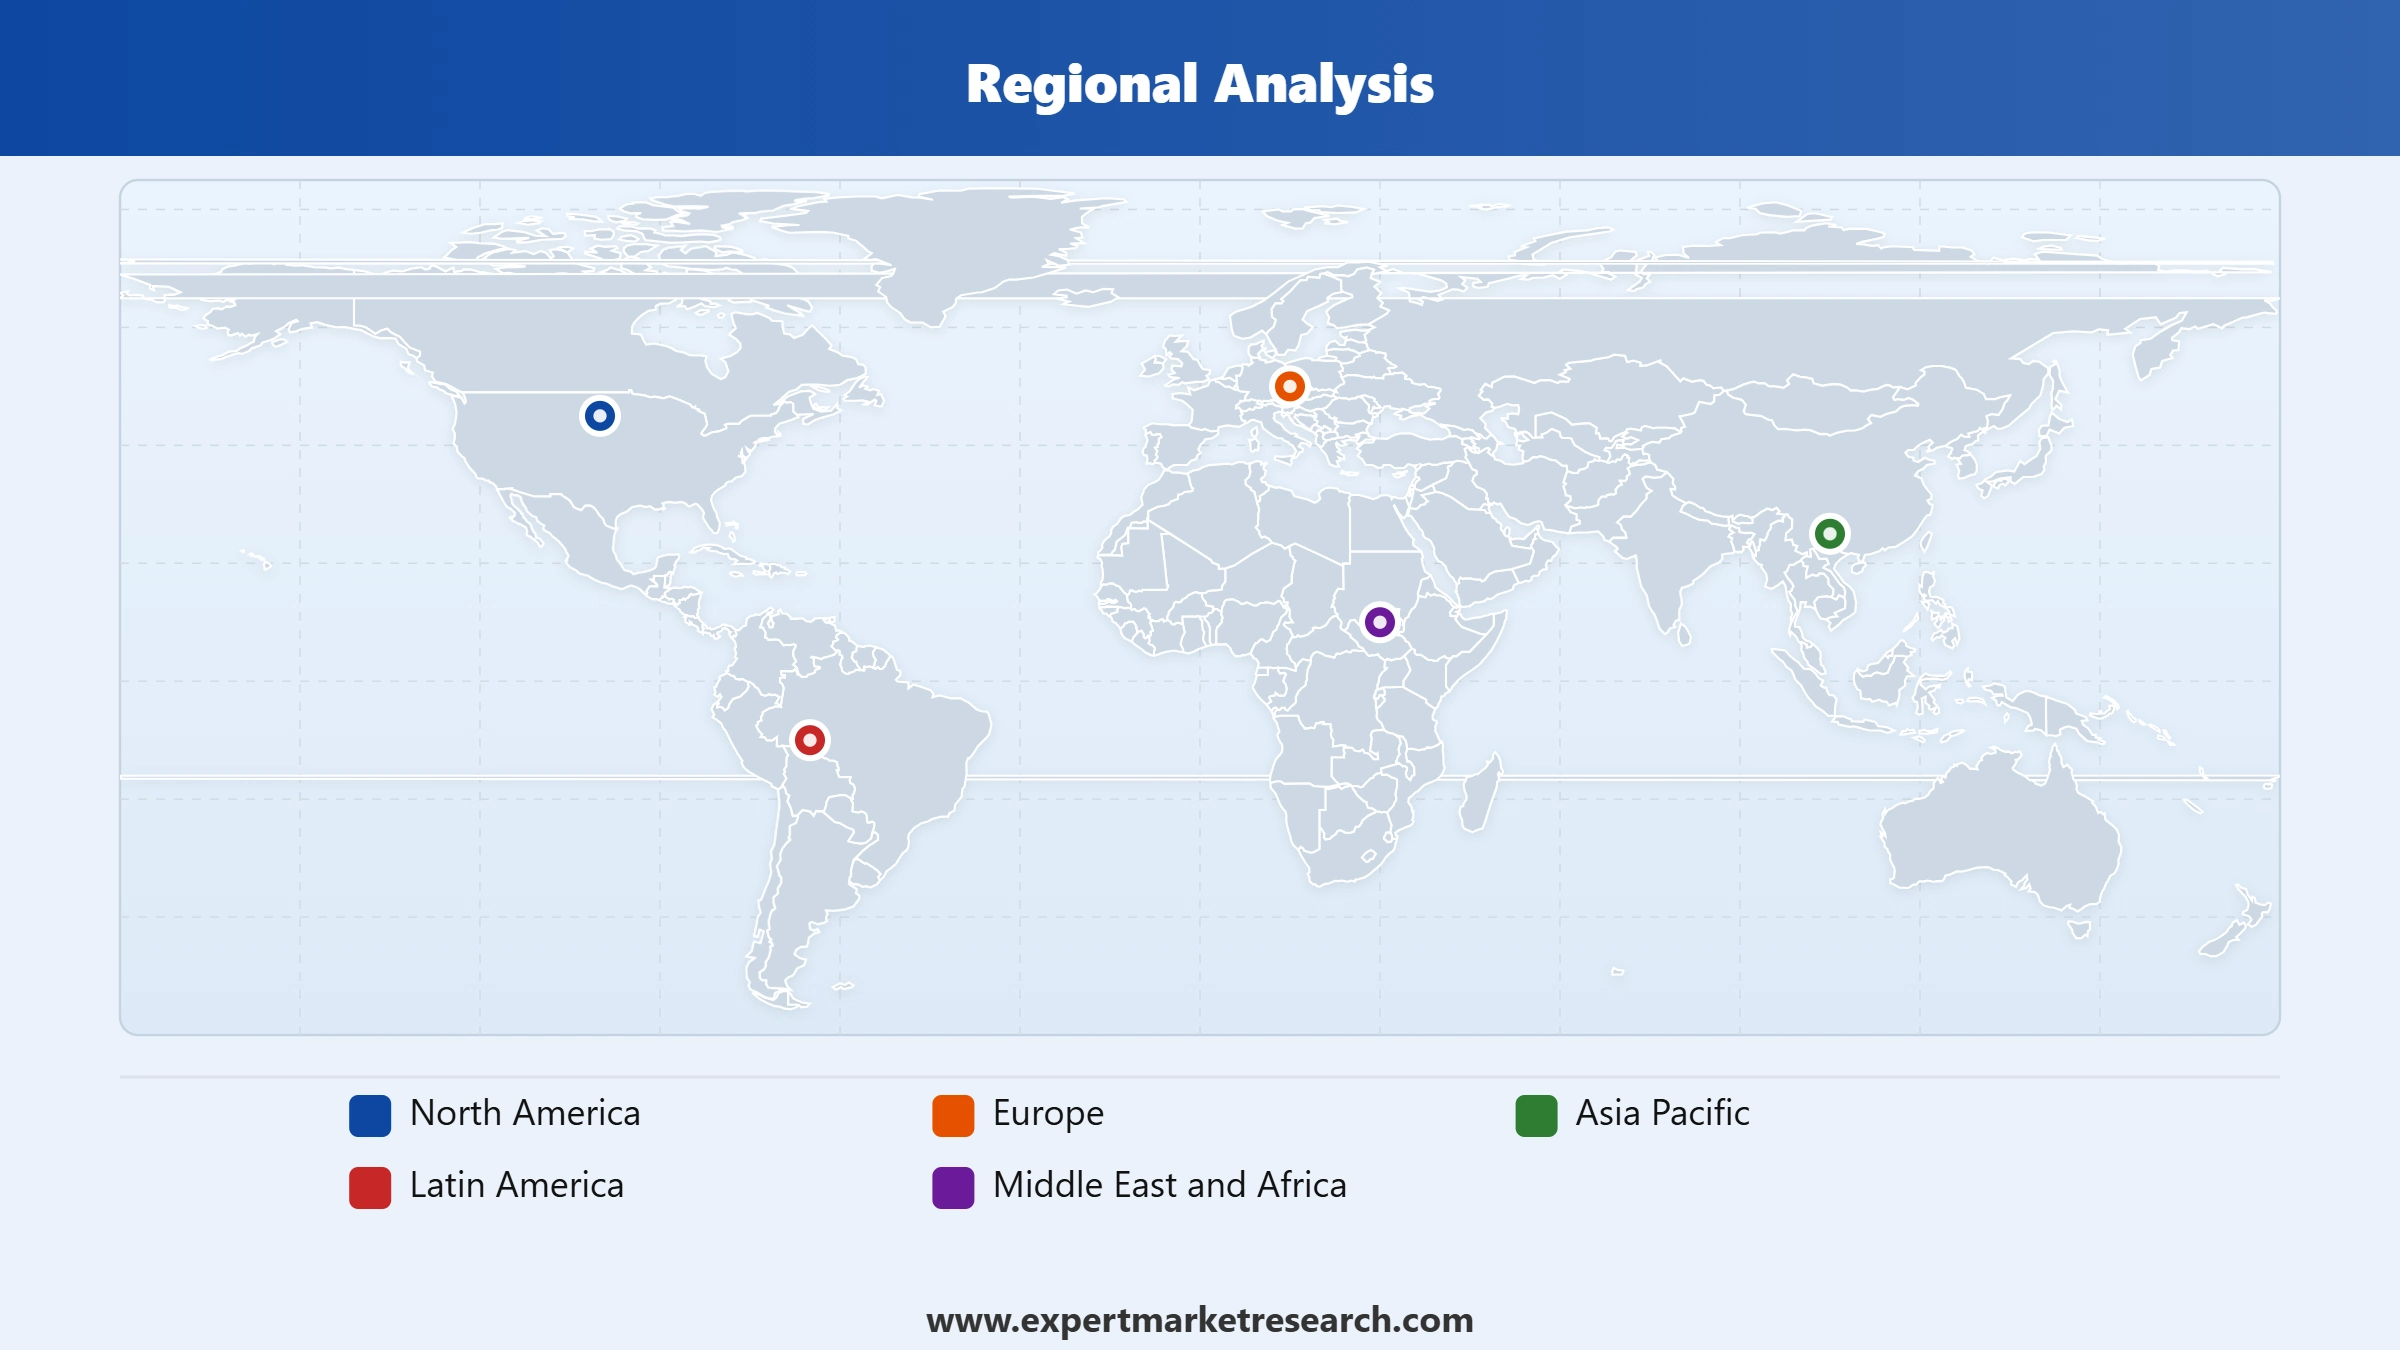
Key Insight: The simulation software market in North America is currently positioned at the forefront due to the region’s early adoption and the presence of strong innovation ecosystems. Asia Pacific is growing at an accelerated pace owing to industrial growth and digital transformation initiatives. Europe retains a stable demand level, owing to its focus on engineering precision and sustainability. Latin America exhibits a slow trend of adoption, influenced by industrial and infrastructure development. The Middle East and Africa regions are mainly using simulation tools in the energy and construction sectors. Differences amongst regions are evident, being the result of economic conditions, industrial maturity, and policy support, which necessitates vendors to change their strategies.




Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By deployment type, the on-premise segment captures the dominant share in the market due to data control and security requirements
On-premise deployment continues to retain a sizeable loyal customer base, particularly within industries that deal with confidential data, boosting the simulation software market value. Aerospace, defense sectors, as well as prominent automotive companies prefer simulation environments that remain safe, within their own premises. Dassault Systmes SE offers support for top-tier on-premises solutions that can be combined with the already existing PLM systems. Such arrangements improve the manageability of simulation models; however, they require a substantial investments. In March 2026, SimScale partnered with AI Engineering enabling meshless SPH cloud simulation, delivering 10 to 20 times faster fluid analysis using NVIDIA AI infrastructure.
On the other hand, cloud-based simulation is expanding its share in the simulation software market, mainly due to the flexibility and cost benefits. Autodesk, Inc. for example, has come up with cloud simulation products that support real-time collaboration between team members in different locations. This considerably helps global engineering teams that co-develop models. Using cloud services results in less reliance on powerful local computers and therefore, the initial costs of participation are significantly lowered.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By end users, the automotive segment account for a substantial share of the market due to high simulation usage in design cycles
Automotive companies use simulation extensively to reduce the time it takes to develop products. Testing car crashes, aerodynamics, and thermal performance are becoming more validated through virtual models. Firms like ANSYS, Inc. offer car manufacturers solutions to simulate various scenarios even before making physical prototypes. Additionally, the rise of electric vehicles is creating challenges, particularly in battery simulation. Automakers are under pressure to innovate faster, making simulation tools indispensable. In December 2025, Siemens launched PAVE360 Automotive digital twin platform enabling full-system virtual integration, reducing development time from months to days, accelerating software-defined vehicle innovation.
The simulation software market is growing steadily and changing user requirements are continuously changing the pattern of demand. Aerospace and defense are emerging as new markets with significant growth potential. This is because of the stringent performance and security requirements. Simulation software is playing an important role in reducing costs and speeding up the process. This is evident in the strategy pursued by Dassault Systèmes SE, which provides industry-specific solutions for advanced aerodynamic and structural simulations. In addition, governments are supporting the concept of virtual testing programs in the defense and aerospace industry.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
North America secures the leading market position due to strong technology adoption and R&D investments
North America continues to lead the simulation software market revenue, backed by the widespread use of leading-edge technologies and major R&D spending. Different sectors such as automotive, aerospace, and technology facilitate the early adoption of simulation tools. Autodesk, Inc. and ANSYS, Inc. are providing the latest simulation platforms. Moreover, the presence of a strong innovation culture also leads to early adoption. In November 2025, Buildroid AI launched simulation-first robotics platform in United States, enabling virtual testing of construction workflows, accelerating deployment, and improving productivity through coordinated multi-robot operations.
The simulation software market in Asia Pacific is rapidly growing as a result of the development of industries and the upsurge of digital tools. Major players such as China, India, and Japan are focusing on manufacturing and infrastructural development. Siemens Digital Industries Software is enlarging its presence in this region to cater to the growing demand. Enterprises are embracing simulation at a steady pace, frequently beginning with the most elementary uses.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
The market is evolving, with simulation software companies increasingly identifying integrated platforms as their core focus rather than a collection of individual tools. Autodesk, Inc. and Dassault Systmes SE are both developing ecosystems that integrate design, simulation, and product lifecycle management. Such strategies aim at retaining customers for an extended period. Another key trend in the market is the transition to AI-enabled simulation where the software can proactively recommend design enhancements. ANSYS, Inc. is allocating resources to this domain. In parallel, Rockwell Automation, Inc. is connecting simulation with industrial automation systems, which is resulting in new applications.
The most significant opportunity for the simulation software market players lies with mid-sized companies who are increasingly realizing the value of this technology. Vendors offering intuitive user interfaces and flexible pricing models are gaining traction, as competition increasingly shifts from technical capabilities to strategic positioning.
Autodesk Inc. is a company that was set up in 1982, and its main office is in San Francisco, United States. It specializes in the creation of cloud-based design and simulation tools. The organization is working to enhance its Fusion platform, which will allow product design and simulation to be integrated.
Founded in 1903 with its head office in Milwaukee, United States, Rockwell Automation Inc. merges industrial automation with simulation. It is working on digital twin solutions that link the factory operations to simulation models, resulting in enhanced decision-making and better operational efficiency.
Founded in 1970 and with its main office at Canonsburg, United States, Ansys, Inc is a company that develops engineering simulation software solutions. The enterprise is adopting AI-driven simulation workflows that enable faster and more accurate results, expanding adoption beyond automotive and aerospace industries.
Founded 1981 and located in Vlizy-Villacoublay, France, Dassault Systmes SE provides simulation platforms that are integrated with product lifecycle management. It concentrates on industry-specific solutions with aerospace and healthcare as main focus areas, thus enabling highly detailed and accurate virtual testing environments.
Other key players in the market include Bentley Systems, Incorporated, and Siemens Aktiengesellschaft, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
The simulation software industry faces a skills challenge that constrains adoption more tightly than product capability does. Running credible analyses requires understanding both the physics being modelled and the numerical methods approximating it, and organisations that purchase licences frequently cannot staff them, leaving capability underused. Vendors must also address the validation burden, since simulation results carry weight only when correlation against physical measurement establishes that the model reflects reality work that consumes engineering time and creates a chicken-and-egg problem for organisations reducing physical testing.
Several restraints temper growth. Integration complexity across design, product lifecycle and manufacturing systems absorbs implementation effort that buyers underestimate. Computing cost remains material for high-fidelity analysis despite cloud alternatives, particularly for transient and multiphysics problems. Licence expense also restricts adoption among smaller engineering organisations where the analysis workload cannot justify enterprise pricing.
Opportunities remain substantial. Agent-assisted setup widens the user base from dedicated analysts to design engineers who need the results directly. Integrated toolchains that carry results between disciplines without manual translation address a persistent source of error and delay. Asia Pacific offers the fastest regional growth at a 13.9% CAGR through 2035, driven by manufacturing expansion and semiconductor investment.
Unlock the latest insights with our simulation software market trends 2026 report. Discover regional growth patterns, consumer preferences, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.
Portable Bluetooth Speakers Market


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 9714.77 Million.
The market is projected to grow at a CAGR of 13.20% between 2026 and 2035.
Investing in cloud-based platforms, developing user-friendly interfaces, integrating AI capabilities, targeting mid-sized enterprises, and expanding industry-specific solutions are helping stakeholders strengthen market position and drive adoption.
The key trends in the market the various technological advancements such as machine learning, which enhance the productivity of the simulator, and the increasing instances of cloud breaches caused due to misconfiguration.
The major regions in the market are North America, Latin America, the Middle East and Africa, Europe, and the Asia Pacific.
The various deployment types of simulation software in the market are on-premise and cloud.
The significant end users of simulation software in the market are automotive, IT and telecommunication, aerospace and defence, energy and mining, education and research, and electrical and electronics, among others.
The key players in the market include Autodesk Inc., Rockwell Automation Inc., Ansys, Inc., Dassault Systèmes SE, Bentley Systems, Incorporated, and Siemens Aktiengesellschaft, among others.
The market is estimated to witness a healthy growth in the forecast period of 2026-2035 to reach USD 33565.78 Million by 2035.
High implementation costs, complex integration with existing systems, shortage of skilled professionals, and concerns around data security are slowing adoption, especially among smaller enterprises and highly regulated industries.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Deployment Type |
|
| Breakup by End User |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
| Report Price and Purchase Option | Explore our purchase options that are best suited to your resources and industry needs. |
| Delivery Format | Delivered as an attached PDF and Excel through email, with an option of receiving an editable PPT, according to the purchase option. |
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




