

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
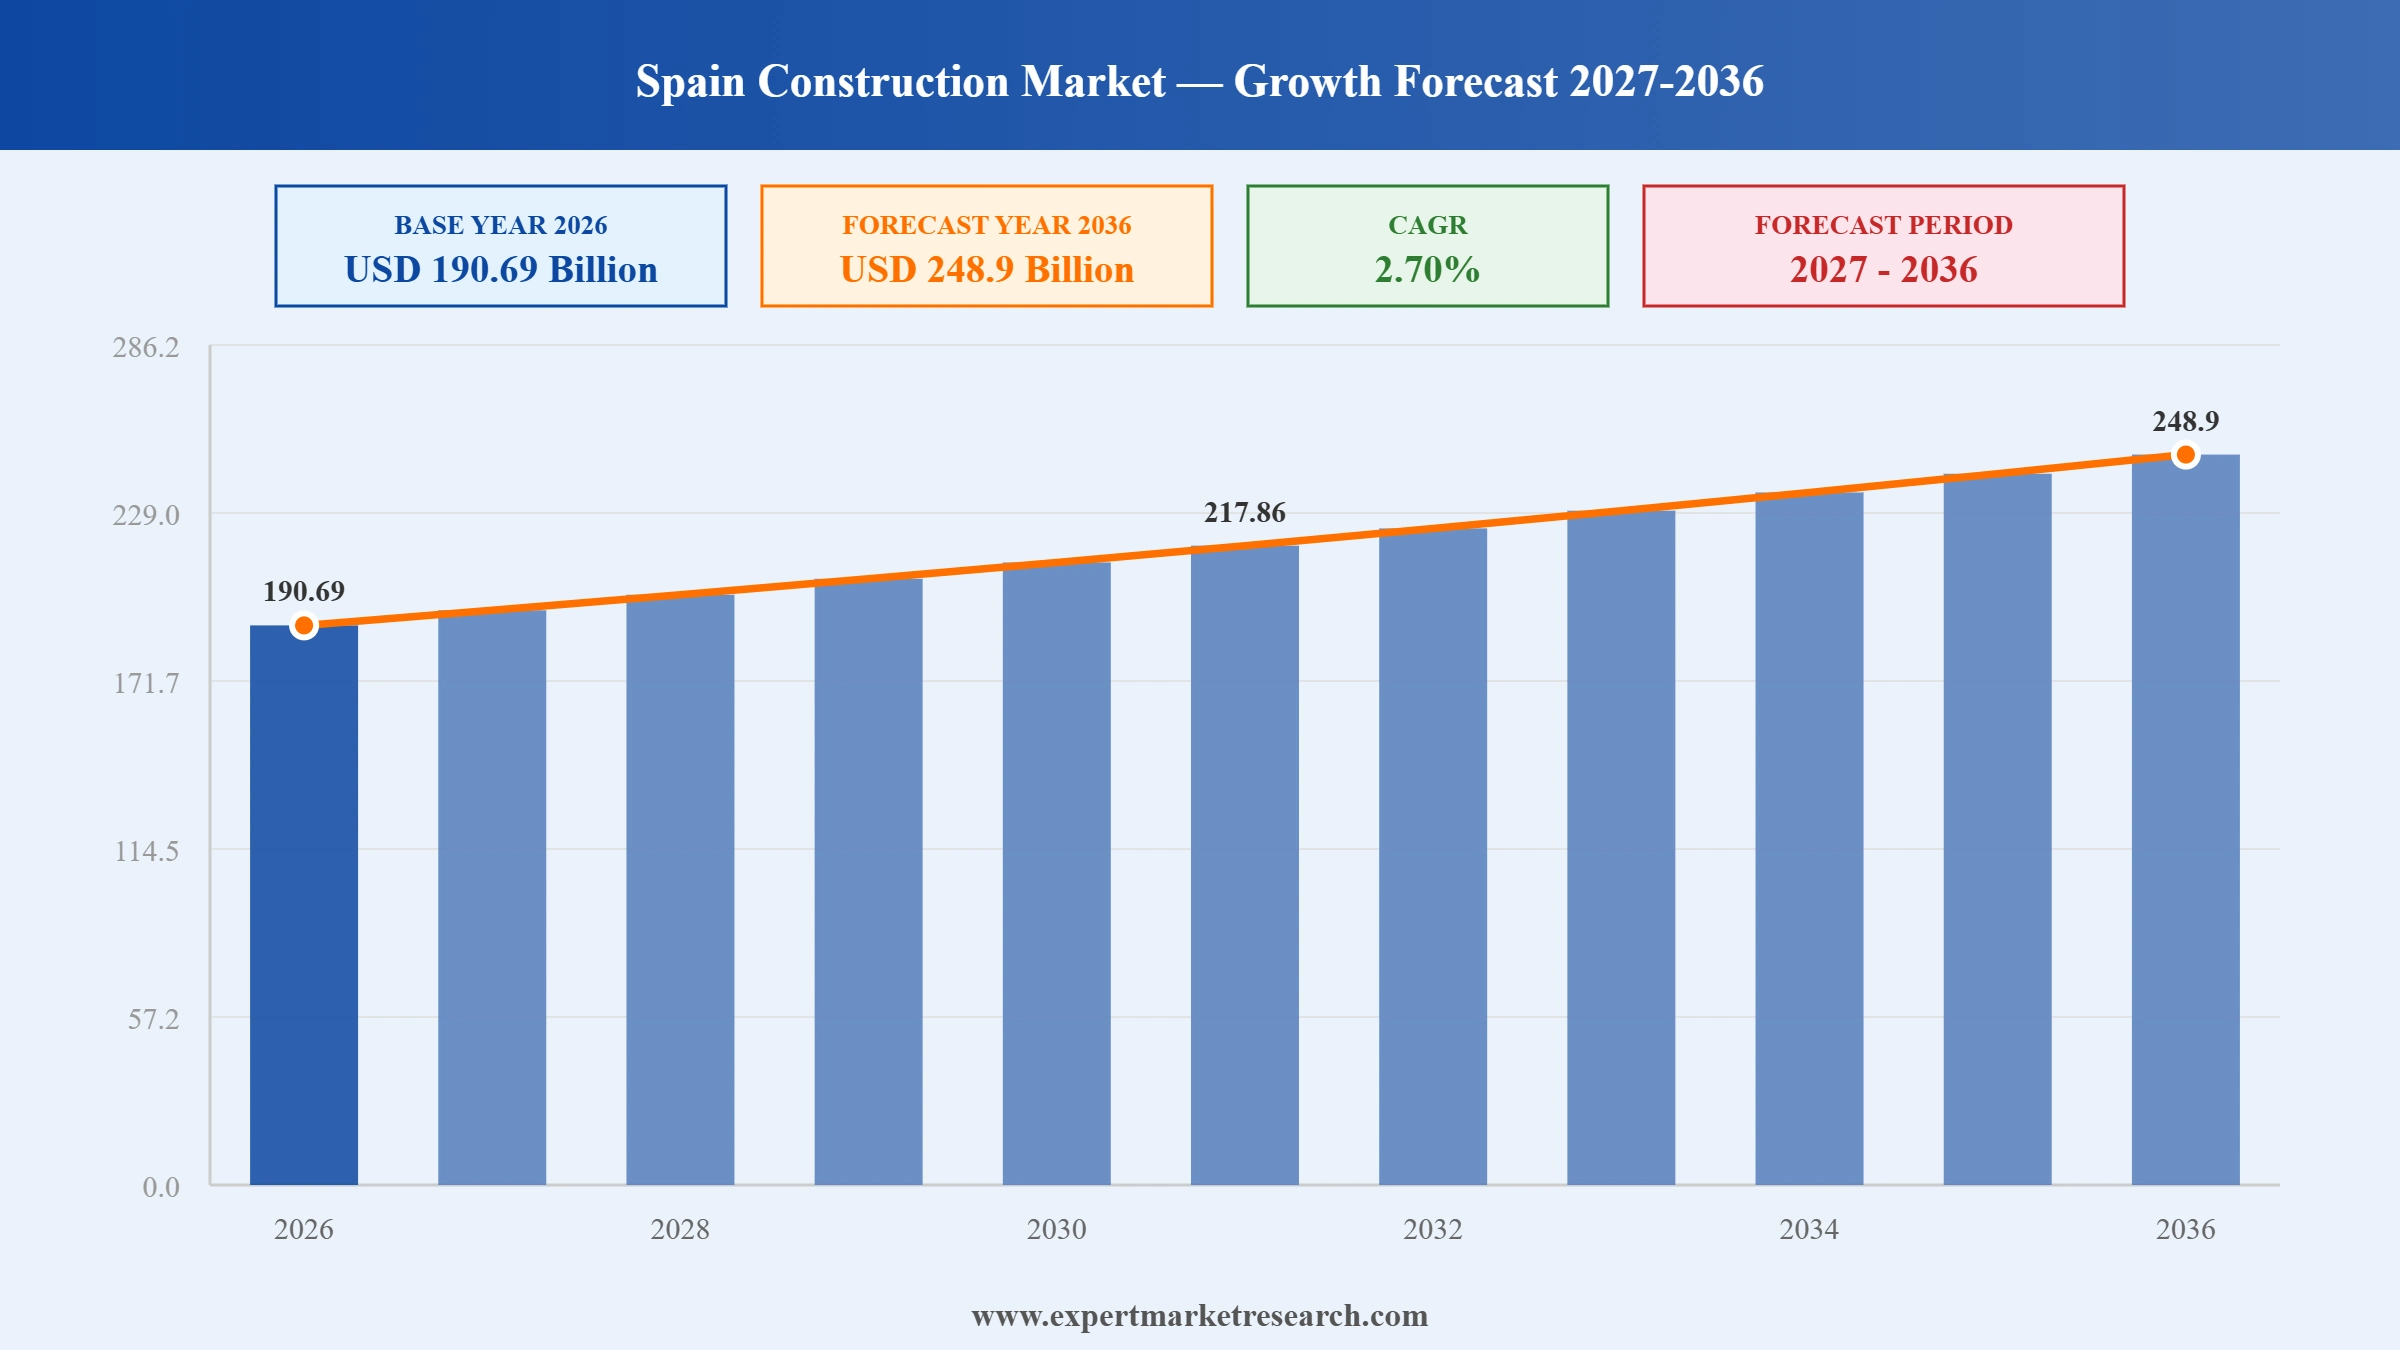
The Spain construction market attained a value of USD 185.68 Billion in 2025 and is projected to expand at a CAGR of 2.70% through 2035. The market is further expected to reach USD 242.36 Billion by 2035. Rising infrastructure investment, sustained residential demand, and expanding renovation activity are driving overall growth in the market, with government backed recovery funds and energy efficiency mandates reshaping how developers and contractors approach new and existing building stock.
The Spain construction market encompasses new construction and renovation activity serving commercial, residential, industrial, and institutional end users across the country. Demand continues to be shaped by sustained infrastructure investment, government backed recovery funds, and rising renovation activity as building owners pursue energy efficiency compliance, with new construction accounting for the largest activity share given continued residential and infrastructure development across the market.
Established Spain construction companies are increasingly competing for large scale public infrastructure tenders through strategic consortiums, reflecting intensifying competition for major transportation and utility projects. In July 2026, a group of leading contractors began pursuing approximately 5 billion euros in Madrid public works, spanning water treatment plants, hospitals, and major railway projects backed by regional and municipal authorities.
Established Spain construction companies are increasingly directing investment toward digital project management and sustainable building practices rather than relying solely on conventional construction methods, reflecting a strategic shift toward efficiency as labour shortages and material costs pressure margins nationwide. Companies are pursuing parallel investment across renewable energy infrastructure, renovation services, and international expansion rather than remaining narrowly focused on domestic new build activity, while strengthening partnerships across engineering, utilities, and transportation sectors to accelerate project delivery. Deals of this kind help contractors secure long term revenue visibility across multiyear concessions and public private partnerships that increasingly define the Spain construction market.
Read more about this report - Request a Free Sample
| Spain Construction Market Report Summary | Description | Value |
| Base Year | USD Billion | 2025 |
| Historical Period | USD Billion | 2019-2025 |
| Forecast Period | USD Billion | 2026-2035 |
| Market Size 2025 | USD Billion | 185.68 |
| Market Size 2035 | USD Billion | 242.36 |
| CAGR 2019-2025 | Percentage | XX% |
| CAGR 2026-2035 | Percentage | 2.70% |
| CAGR 2026-2035 - Market by Region | Madrid | 3.3% |
| CAGR 2026-2035 - Market by Region | Valencian Community | 2.9% |
| CAGR 2026-2035 - Market by Type | Commericial | 3.0% |
| CAGR 2026-2035 - Market by Application | Renovation | 3.0% |
| Market Share by Region 2025 | Madrid | 21.2% |
Three major Spanish construction groups submitted bids for the 234.8-million-euro expansion of Gran Canaria Stadium ahead of the 2030 football World Cup, each partnering with regional Canary Islands business allies. Regional partnerships forged through such bids help firms across the Spain construction market build lasting visibility ahead of major sporting events, while securing valuable local subcontracting relationships for future tender rounds.
Spain's construction sector continued accessing its share of approximately 154 billion dollars in NextGenerationEU recovery resources, with roughly 70 percent flowing into infrastructure, renewable energy, and building rehabilitation programmes across every autonomous region. Contractors across the Spain construction market benefit from multiyear visibility into infrastructure and renovation pipelines whenever recovery funding flows at this scale, allowing firms to plan procurement well ahead of tender deadlines.
FCC Group reported full year turnover growth of 6.9 percent to 9.7 billion euros, driven partly by acquisitions in the United Kingdom, United States, and France that expanded its water and environmental services divisions abroad. Sustained turnover growth of this scale reinforces investor confidence in diversified Spanish groups that balance steady domestic construction activity against faster growing international service contracts.
The company reported that its EBITDA surged 30 percent to 113 million euros in the third quarter of 2025, as recapitalisation and cost control measures offset a decline in overall revenue caused by fewer new project awards. Turnaround progress of this kind reassures lenders across the Spain construction market that recapitalised contractors can convert restructuring efforts into genuine profitability gains, supporting future access to competitive financing terms.
Established Spanish engineering firms across the Spain construction market are increasingly pursuing large scale international contracts, rather than concentrating solely on domestic projects, as global infrastructure investment accelerates. This is helping firms diversify revenue while building specialised project delivery capabilities that transfer across offshore and onshore facility categories. In April 2026, COMSA secured a major railway reconstruction contract in Croatia previously held by a rival European contractor, valued at approximately 255 million euros, strengthening its presence across Central European rail markets.
Established Spanish construction groups across the Spain construction market are increasingly winning specialised healthcare infrastructure contracts, rather than focusing solely on conventional building projects, as regional health authorities modernise treatment capabilities. This is helping contractors build differentiated expertise in complex, technically demanding facility types that command higher margins than standard building work. In November 2025, Sacyr was awarded construction of a new Proton Therapy Unit at Hospital La Paz in Madrid, worth 16.5 million euros, reinforcing the capital's growing specialised healthcare infrastructure pipeline and treatment capacity.
Established electrical infrastructure groups across the Spain construction market are increasingly forming strategic alliances with battery technology manufacturers, rather than developing storage capabilities independently, as renewable energy penetration exceeds half of national electricity generation. This is helping firms offer packaged solutions combining generation and storage expertise. In February 2026, Elecnor formalised a strategic agreement with technology manufacturer Gotion and development firm Battman to strengthen its position in Spain's battery energy storage sector amid accelerating renewable capacity additions and evolving national grid requirements.
Established Spanish construction companies across the Spain construction market are increasingly reporting sustained international revenue diversification, rather than relying primarily on domestic activity, as they seek to reduce exposure to any single national market. This is helping companies stabilise earnings across economic cycles, since downturns in one national market rarely coincide with downturns in another. In July 2026, Grupo San Jose reported new contract awards spanning residential and industrial projects in Spain alongside a residential complex in Santiago de Chile, extending its footprint into Latin America.
Established public infrastructure authorities are increasingly advancing multibillion euro tender programmes covering water treatment, healthcare, and transportation, rather than issuing smaller standalone contracts, to accelerate regional infrastructure renewal. This is helping authorities attract stronger competitive bids from leading national contractors, who value the multiyear revenue visibility such programmes provide. In May 2026, the Port of Barcelona awarded a 111.5-million-euro contract to build three new berths at its Energy wharf, expanding capacity for future maritime energy operations.
The Expert Market Research's report titled “Spain Construction Market Report and Forecast 2026-2035” offers a detailed analysis of the market based on the following segments:
Market Breakup by Construction Type
Key Insight: New construction accounts for the largest activity share in the Spain construction market, supported by sustained residential and infrastructure development across major Spanish cities. Building owners across Barcelona and Valencia in particular are driving renovation activity as they pursue energy efficiency compliance, illustrated by Spain's January 2026 extension of income tax deductions covering qualifying energy efficiency renovations through the year.
Market Breakup by End Use
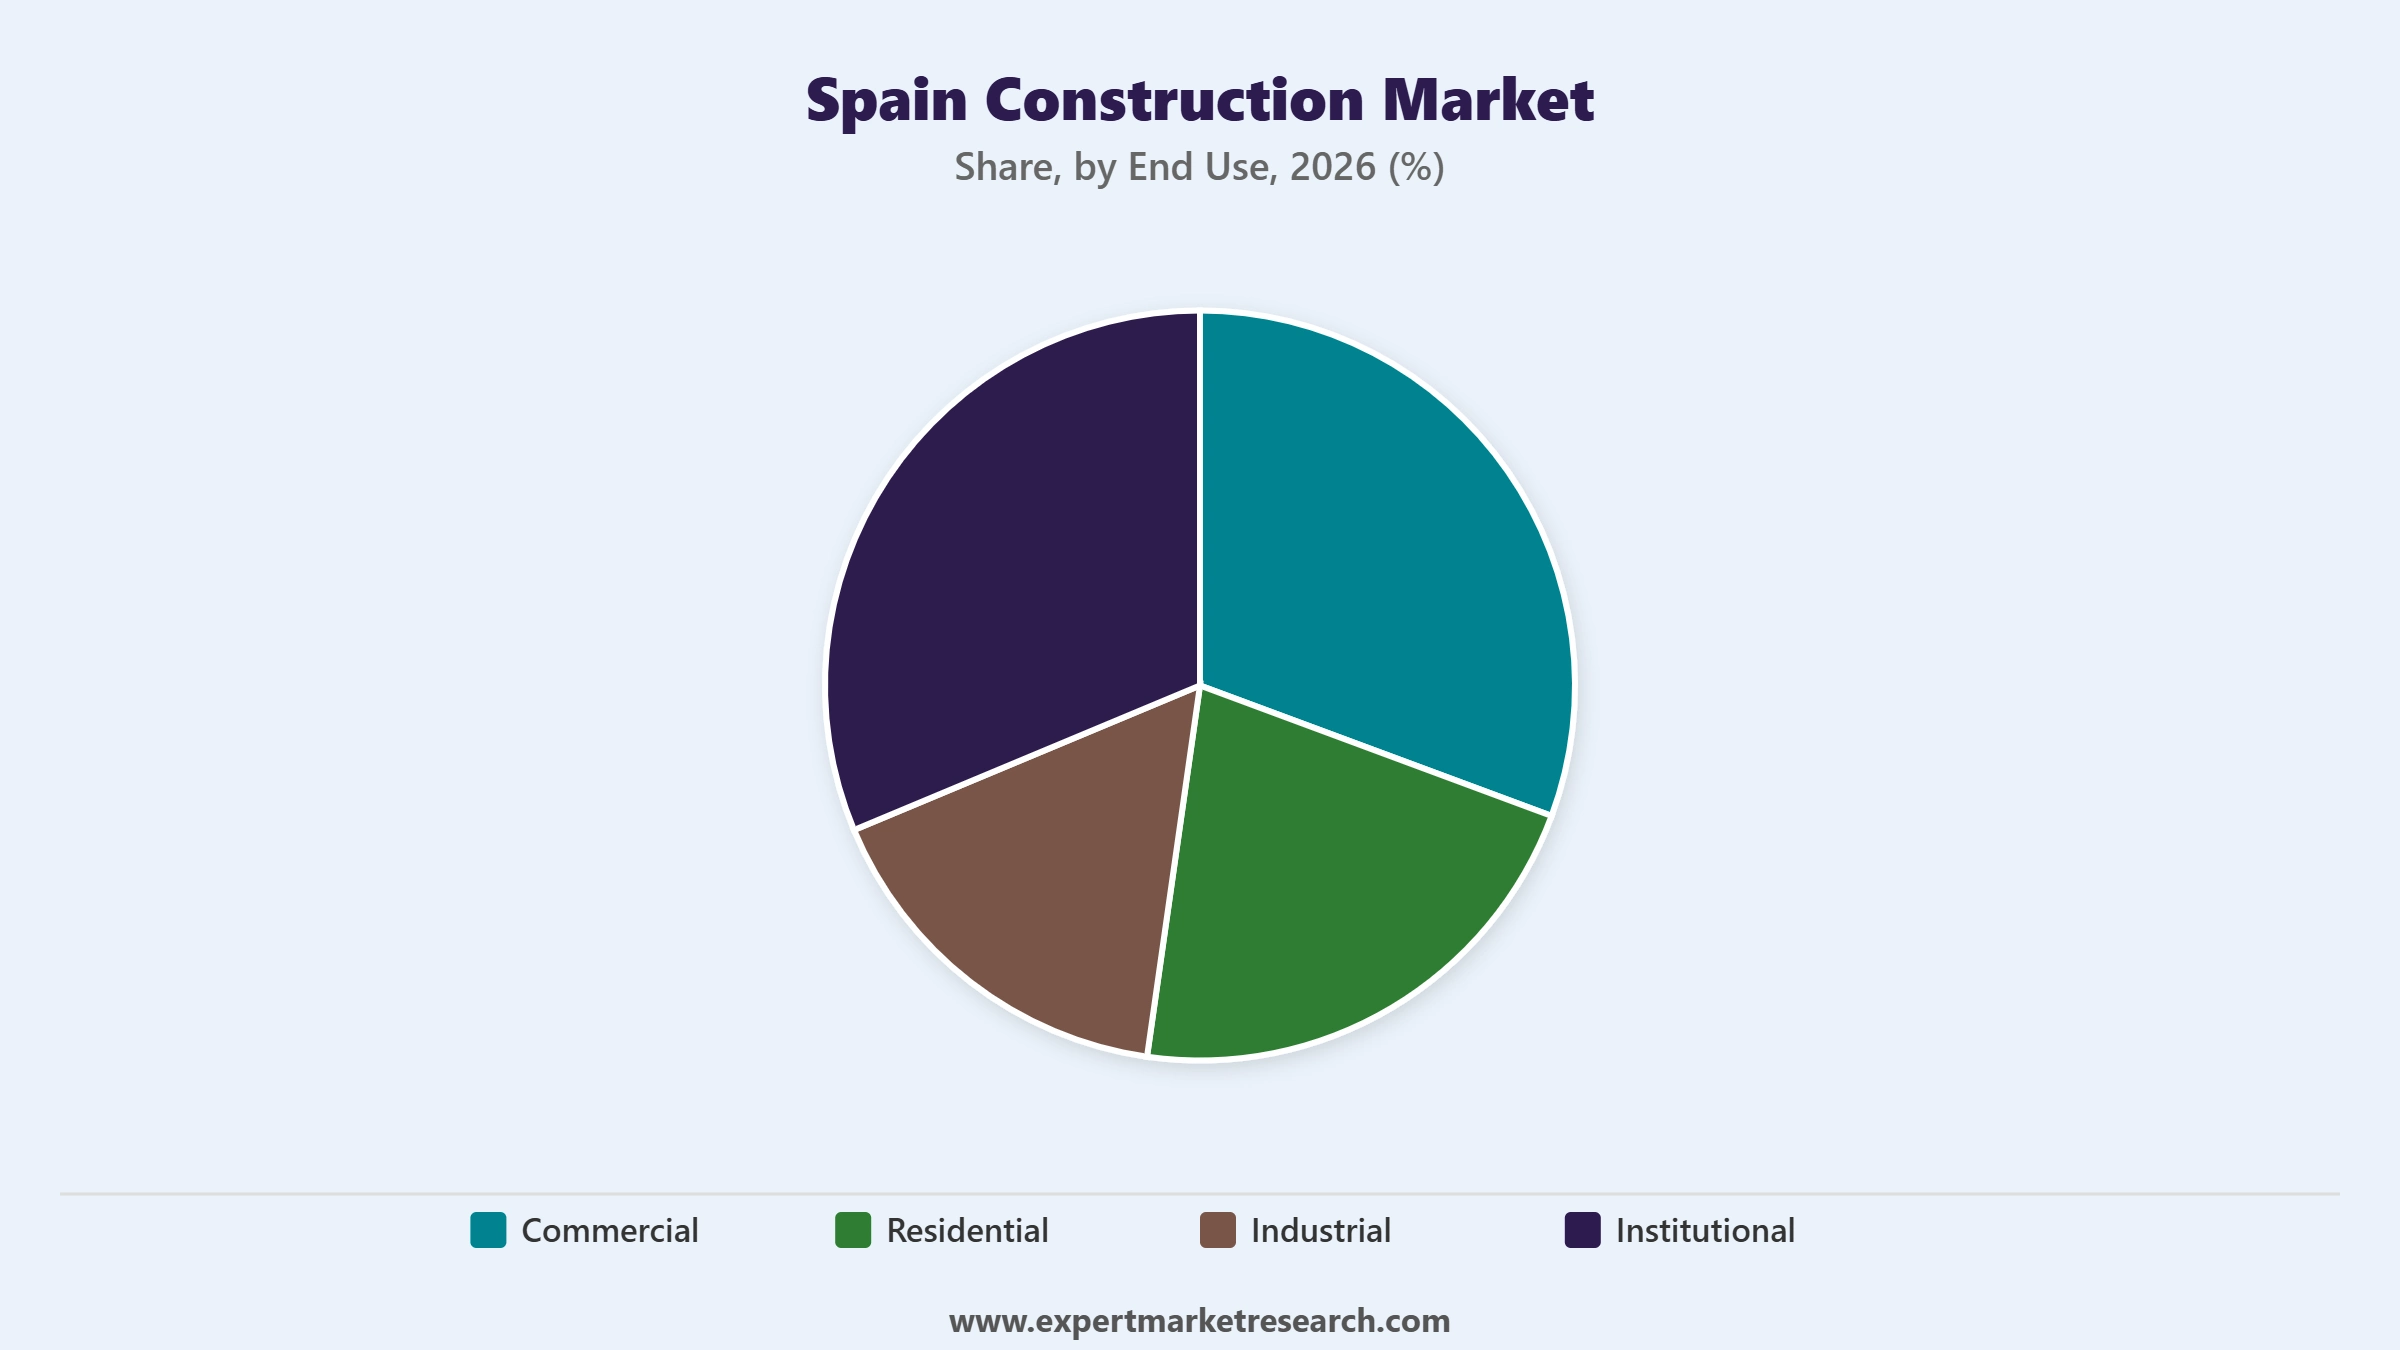
Key Insight: Sustained housing demand across major metropolitan areas keeps residential construction as the leading end use category in the Spain construction market. Office, retail, and hospitality development supported by recovering tourism activity continues to expand the commercial segment, while logistics and manufacturing facility investment underpins industrial construction. Spanning hospitals, schools, and public buildings, institutional construction is registering the fastest growth as government infrastructure programmes accelerate.
Market Breakup by Region
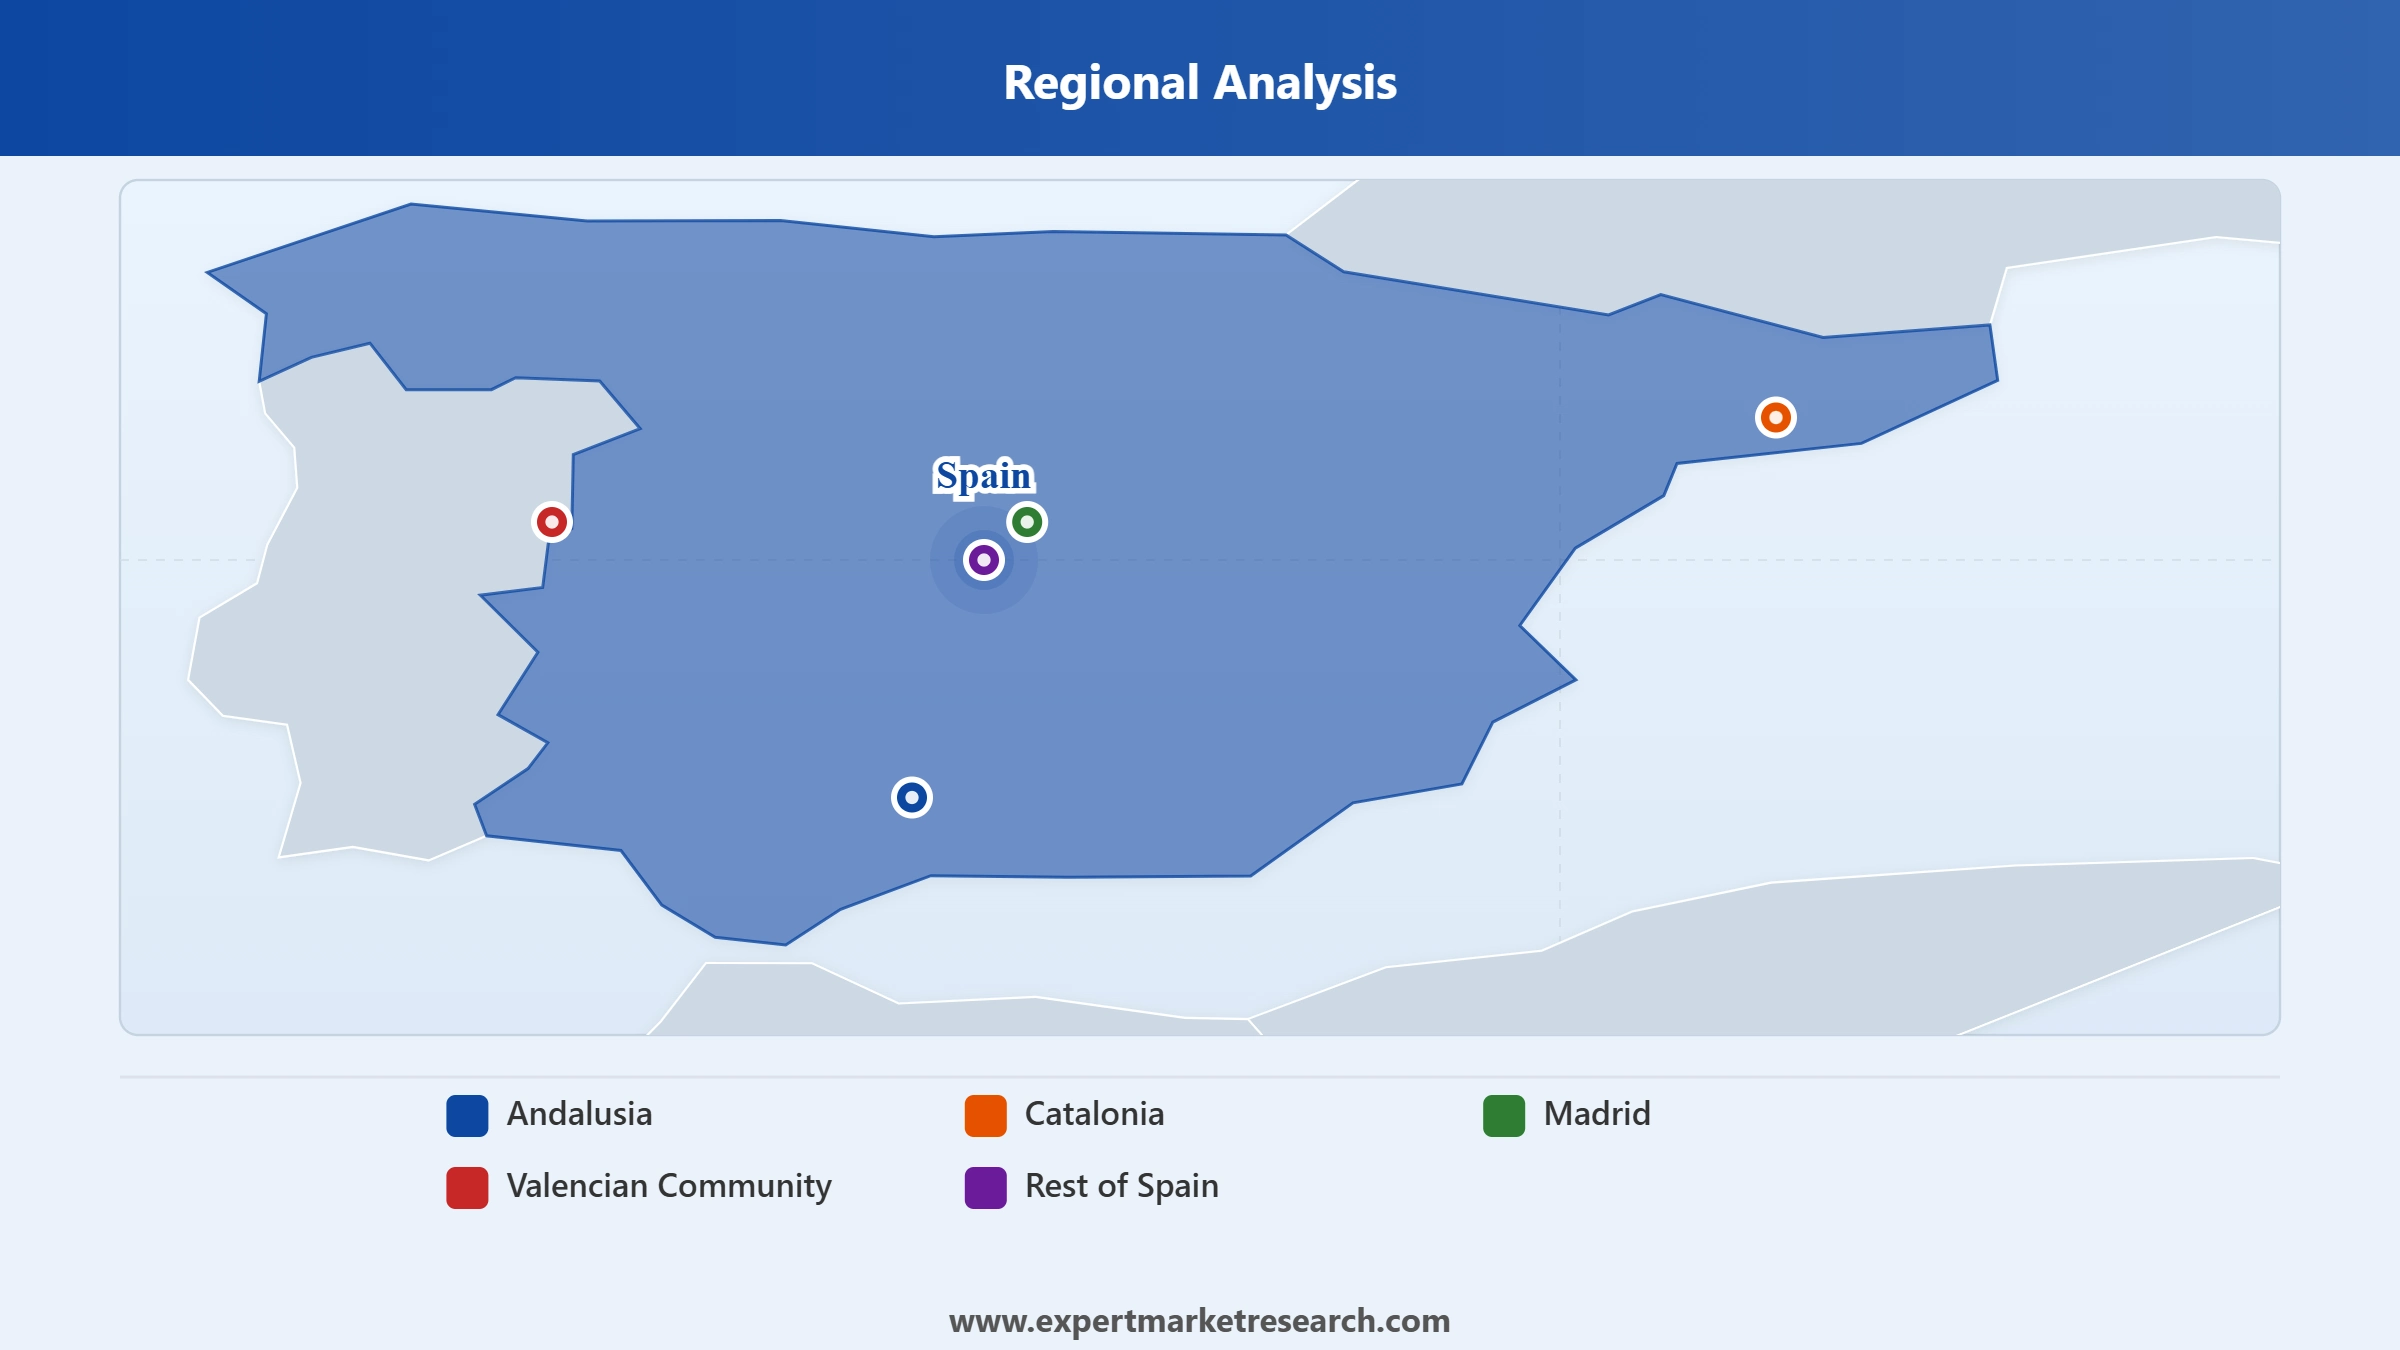
Key Insight: Regional dynamics in the Spain construction market continue to shape competitive strategies. Major public infrastructure tenders and concentrated corporate investment place Madrid at the front of regional growth, while Barcelona's commercial and residential development pipeline sustains steady demand across Catalonia. Tourism related hospitality construction benefits Andalusia, residential and industrial activity keeps expanding across the Valencian Community, and the remaining regions together contribute a broad, geographically distributed base of smaller projects.
Read more about this report - Request a Free Sample
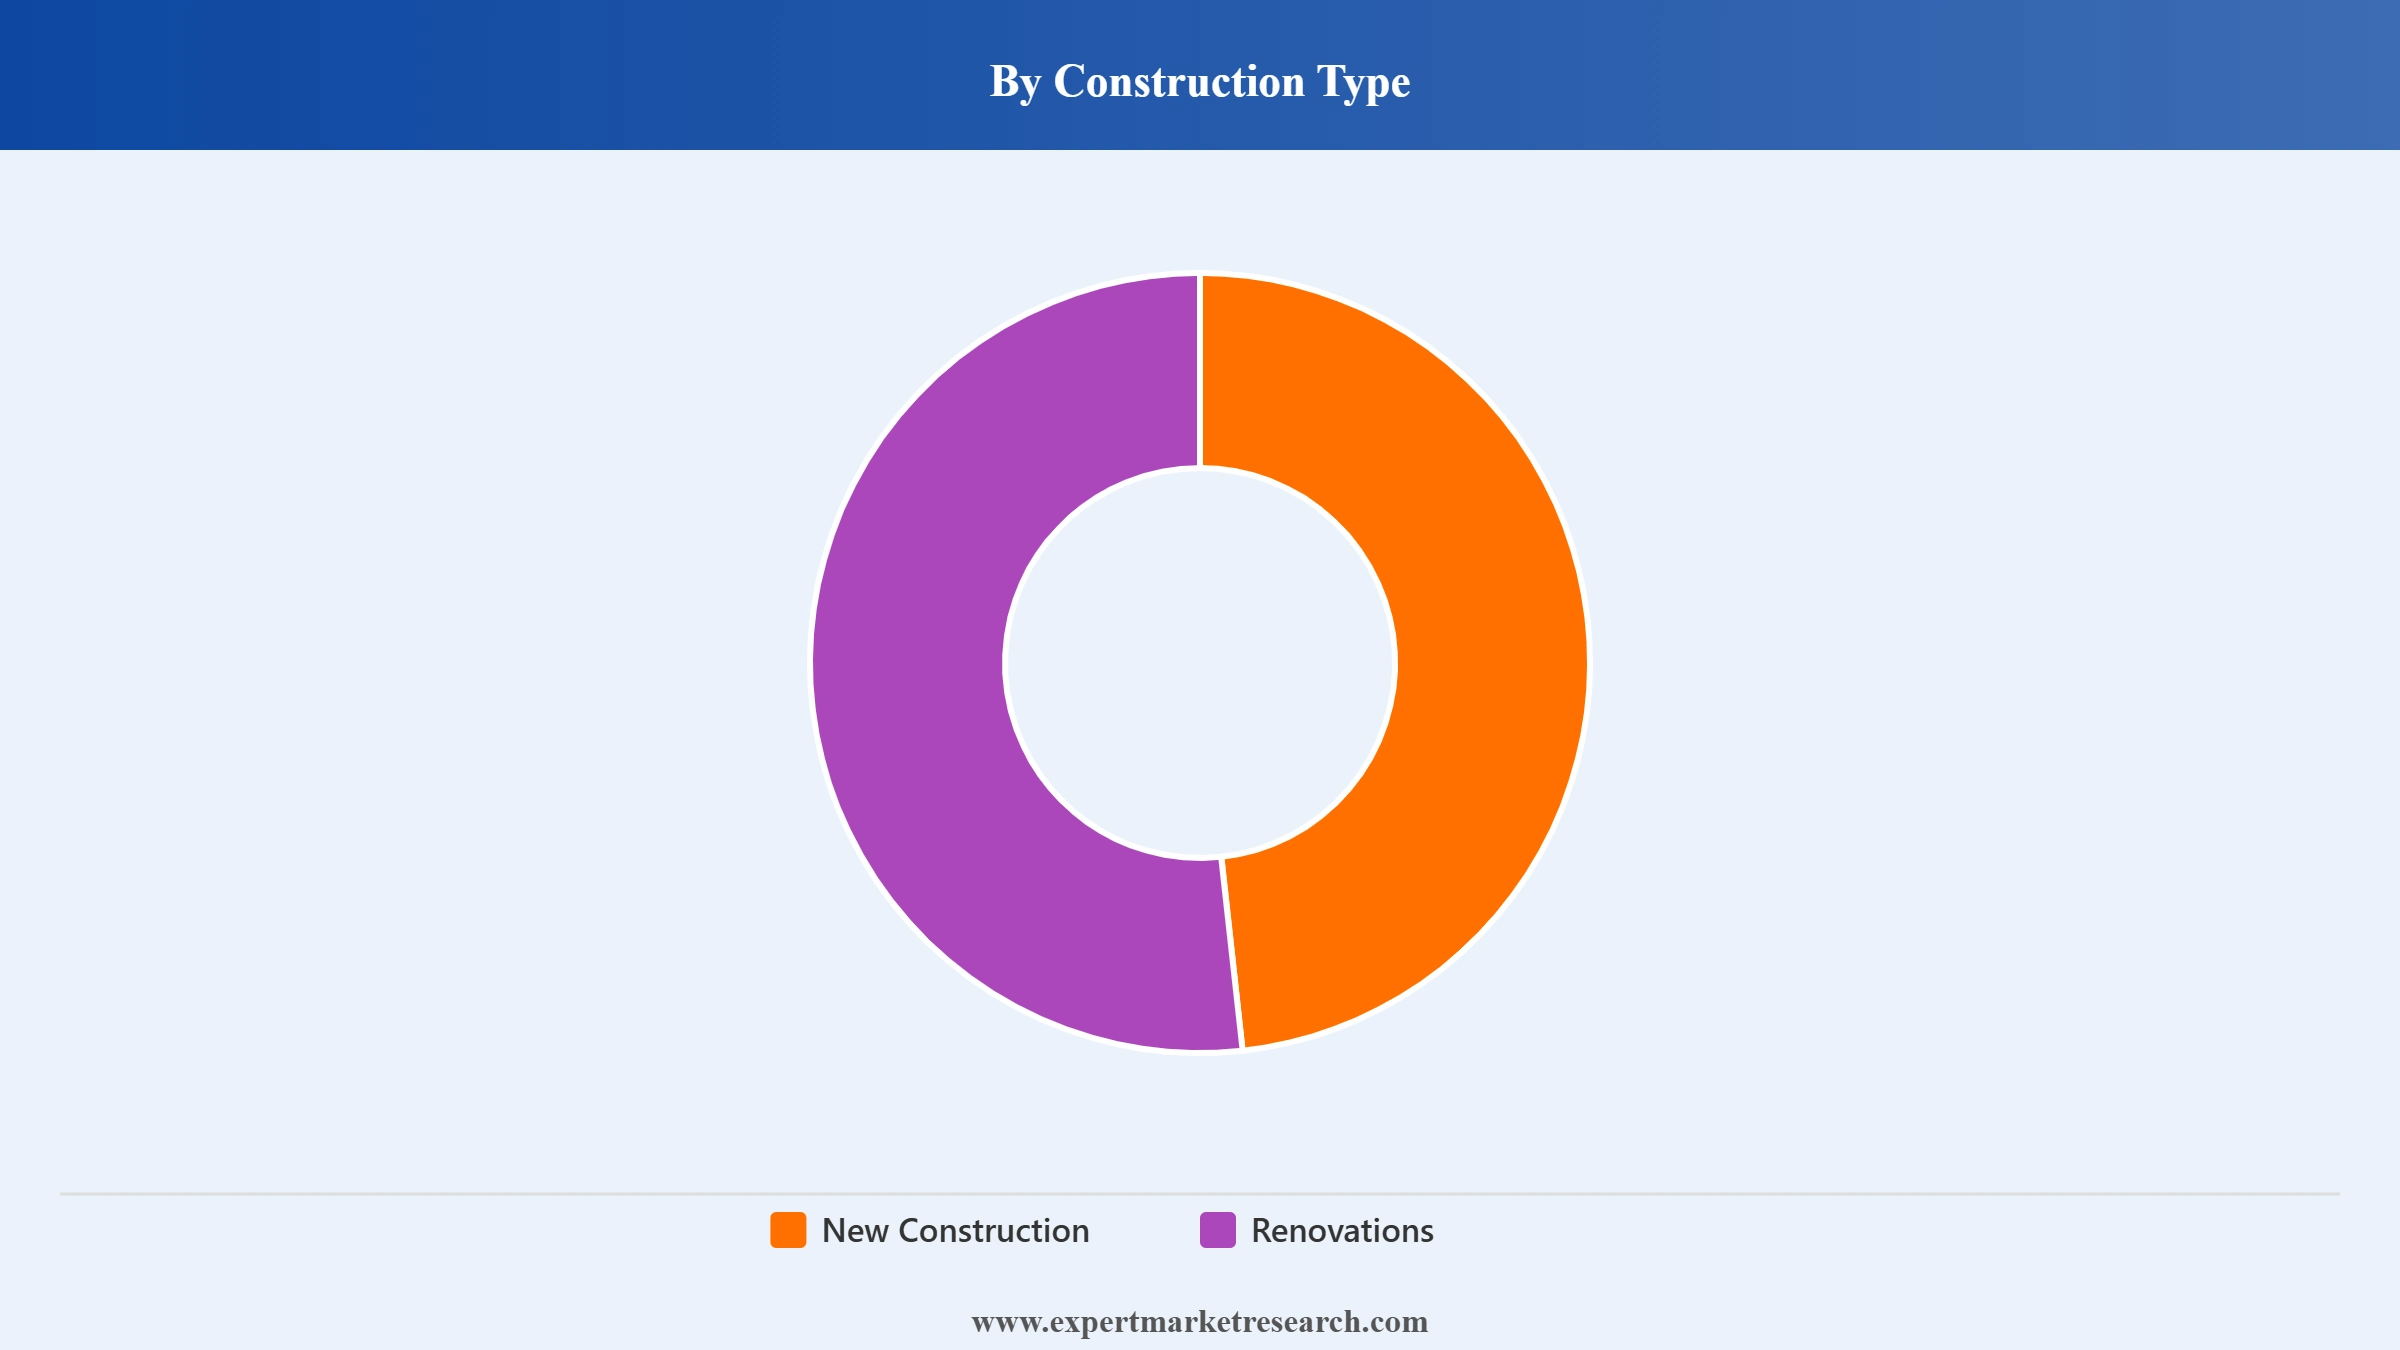
By construction type, new construction dominates the market through sustained residential and infrastructure development
New construction accounts for the largest activity share of the Spain construction market, supported by sustained residential and infrastructure development across major Spanish cities. In March 2026, COMSA reported 2025 sales of 1.007 billion euros, a 2 percent increase over the prior year, supported by an order backlog covering roughly two years of activity across its construction, industrial engineering, and maintenance divisions, with international operations contributing a growing share of overall group turnover, a trend the company expects to continue through 2026.
Read more about this report - Request a Free Sample
Renovations are growing quickly as building owners pursue energy efficiency compliance under Spain's updated technical building code, which tightens standards for existing structures. In October 2025, regional governments including Valencia and Galicia continued operating dedicated renovation subsidy programmes, covering window replacement, insulation upgrades, and appliance efficiency improvements for qualifying households across urban and rural housing stock alike, with demand continuing to outpace available contractor capacity in most participating regions, lengthening typical project waiting times for homeowners.
By end use, residential dominates the market while institutional registers the fastest growth through accelerating government programmes
Residential construction accounts for the largest end use share of the Spain construction market, anchored by sustained housing demand across major metropolitan areas. In March 2026, Neinor Homes completed its acquisition of AEDAS Homes, reaching 96.83 percent ownership and consolidating its position as Spain's leading residential development platform, with a combined project pipeline spanning affordable housing through premium urban developments, giving the merged group unmatched geographic reach in every major Spanish city.
Read more about this report - Request a Free Sample
Institutional construction is registering the fastest growth as government infrastructure programmes accelerate spending on hospitals, schools, and public buildings. In October 2025, OHLA won a 550-million-euro contract to build Malaga's new hospital, beating several competing bids for one of Andalusia's largest healthcare infrastructure projects, a result that reinforced regional confidence in the company's capacity to deliver technically demanding public facilities on schedule, ahead of similar tenders expected across neighbouring provinces.
Read more about this report - Request a Free Sample
Madrid dominates the market through concentrated public infrastructure tenders and corporate investment
Madrid leads the Spain construction market, anchored by concentrated public infrastructure tenders and corporate headquarters investment across the capital region. The city's status as the seat of national government keeps public procurement activity unusually high relative to other Spanish regions, spanning transportation, healthcare, and water infrastructure programmes. Established contractors maintain permanent regional offices in Madrid to manage this steady pipeline, while national interest rates and comparatively high construction financing costs continue to weigh on private residential development across most price segments.
Madrid is also registering the fastest regional growth as major infrastructure tenders accelerate across water, healthcare, and transportation categories. In February 2026, progress continued on a major electricity interconnection project between France and Spain, part of a broader energy infrastructure programme designed to strengthen the country's grid capacity and cross border transmission reliability as renewable electricity demand rises across the wider Iberian Peninsula and both countries pursue increasingly ambitious decarbonisation targets under their respective national energy plans.
The Spain construction companies are becoming increasingly competitive as major Spain construction companies invest in digital project management, sustainable building practices, and international diversification to differentiate their portfolios across residential, commercial, and infrastructure categories. Companies are prioritising consortium bidding, renewable energy integration, and renovation services to appeal to public authorities and private developers seeking modern, compliant construction partners. Established Spain construction companies are also deepening engineering capabilities, battery storage partnerships, and cross border project delivery to strengthen market positioning, while investing in energy efficiency retrofits to defend market share against rising domestic and international competition.
Major Spain construction market players are also focusing on large scale international contracts and joint venture partnerships to capture growing demand across infrastructure and institutional categories. Strategic emphasis on geographic diversification and public private partnership expertise is allowing established companies to capture market share as government tender programmes and recovery fund allocations reshape competitive dynamics across the sector. The market players continue to pursue partnerships with international energy operators and regional business allies, particularly across the Middle East, North America, and the Canary Islands, to diversify revenue beyond the domestic market while smaller regional contractors compete on local project delivery expertise to retain municipal and provincial customers.
Founded in 1997 and headquartered in Madrid, Spain, this is a leading Spanish construction and services group operating through Turner, Cimic, and engineering and construction business segments across highways, railroads, and building construction. The company employs more than 157,000 people worldwide, with a geographical revenue mix spanning the United States, Australia, Canada, and Germany alongside its Spanish operations.
Founded in 1952 and headquartered in Amsterdam, Netherlands, this is a global infrastructure company operating across airports, highways, construction, and services divisions spanning more than 20 countries. Originally established in Spain focused on railway construction, the company has grown into a major international toll road and airport infrastructure operator.
Founded in 1986 and headquartered in Madrid, Spain, this is a diversified infrastructure and construction group operating across engineering, concessions, water management, and services businesses internationally. The company maintains an active presence in rail maintenance, highway concessions, and large-scale civil engineering projects across Europe and Latin America.
Founded in 1959 and headquartered in Madrid, Spain, this is an international engineering and construction company specialising in industrial plants for the energy, oil and gas, and power generation sectors. The company has designed and built more than 1,000 industrial plants globally, with the Middle East representing a key growth market for its engineering services.
Other key players in the market include Acciona SA, Fomento de Construcciones y Contratas SA, ELECNOR, S.A., Cobra Gestion De Infraestructuras, SLU, Obrascon Huarte Lain S.A., and Grupo Empresarial San Jose SA, among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our Spain construction market trends 2026 report. Discover regional growth patterns, construction type and end use economics, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.
United States Higher Education Construction Market
Europe Data Center Construction Market


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 185.68 Billion.
The market is projected to grow at a CAGR of 2.70% between 2026 and 2035.
The market is assessed to witness a healthy growth in the forecast period to reach around USD 242.36 Billion in 2035.
The different construction types in the market include new construction and renovations.
The major end users of construction include commercial, residential, industrial, and institutional.
The major regions in the market include Andalusia, Catalonia, Madrid, Valencian Community, and rest of Spain.
The key players in the market include ACS, Actividades De Construccion Y Servicios, SA, Acciona SA, Fomento de Construcciones y Contratas SA, ELECNOR, S.A., Cobra Gestion De Infraestructuras, SLU, Ferrovial S.E., Obrascon Huarte Lain S.A., SACYR S.A., Grupo Empresarial San Jose SA, and Tecnicas Reunidas SA, among others.
Madrid dominates the market, supported by concentrated public infrastructure tenders and corporate headquarters investment.
New construction holds the largest share, supported by sustained residential and infrastructure development across major cities.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Construction Type |
|
| Breakup by End Use |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




