

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
The India toothpaste market attained a value of USD 1501.02 Million in 2025 and is projected to grow at a CAGR of 4.23% through 2035, reaching USD 2271.51 Million by 2035, driven by rising oral health awareness, expanding rural distribution reach, and sustained demand for herbal and Ayurvedic formulations across the country.
Rising oral health awareness and expanding rural distribution reach continue to anchor steady demand across the India toothpaste market. Colgate-Palmolive continues to command approximately 43 percent of the market by value as of 2025, ahead of Unilever's Pepsodent at roughly 23 percent and Dabur at around 17 percent, reflecting the category's continued concentration among a small number of established brands.
The India toothpaste market is witnessing further developments as multinational brands increasingly partner with government health bodies to expand oral hygiene awareness alongside commercial distribution. Colgate-Palmolive India partnered with the Government of Haryana in February 2026 on its Bright Smiles, Bright Futures initiative, targeting 57 lakh school children with oral hygiene education and dental kits across the state.
In addition, herbal and Ayurvedic formulations continue gaining share as domestic manufacturers position natural ingredients against conventional fluoride-based products. Dabur launched a nationwide campaign in September 2025 positioning its toothpaste as a domestically made alternative amid US-India trade tensions, reflecting the category's growing intersection with consumer nationalism and local sourcing sentiment.

Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Herbal and Ayurvedic oral care formulations continue outpacing conventional fluoride-based toothpaste as Indian consumers increasingly favour natural ingredient positioning. Industry data published in August 2026 valued the ayurvedic toothpaste segment at approximately USD1.6 billion, projected to grow at a 14.08 percent CAGR through 2031, with Patanjali Ayurved and Dabur together commanding the majority of the natural category's revenue. Companies can prioritise natural ingredient positioning to capture the fastest-growing segment within the broader toothpaste category.
Premium sensitivity-focused oral care brands continue partnering with government health bodies and professional dental associations to expand preventive care awareness nationwide. Sensodyne, marketed by Haleon, launched its Know Your Dental Age initiative in March 2026 alongside India's Ministry of Health and Family Welfare and the Indian Dental Association, introducing a QR-based dental age assessment tool and extending screenings to passengers on select Vande Bharat Express train routes. Companies can partner with government health bodies and professional associations to expand preventive oral health awareness while reinforcing brand credibility nationwide.
Market-leading oral care brands continue expanding corporate social responsibility programmes that combine public health education with long-term brand awareness among younger consumers. Colgate-Palmolive India partnered with the Government of Haryana in February 2026 to roll out its Bright Smiles, Bright Futures initiative, targeting 57 lakh school children with oral hygiene education, brushing technique training, and dental kits across the state. Companies can combine public health education programmes with long-term brand awareness campaigns to build loyalty among younger consumers.
Domestic FMCG conglomerates continue leveraging nationalist consumer sentiment to challenge established multinational brands amid shifting geopolitical trade dynamics. Dabur, India's third-largest oral care player, launched a front-page advertising campaign in September 2025 positioning its toothpaste as the domestically made alternative to Colgate-Palmolive, using unbranded packaging styled in red, white, and blue to highlight its American ownership amid worsening US-India trade relations. Companies can leverage domestic sourcing narratives to differentiate against multinational competitors during periods of heightened trade tension.
Established oral care leaders continue introducing integrated multi-product systems designed to address multiple oral health concerns through a single coordinated regime. Colgate-Palmolive launched its Total Active Prevention System in February 2025, combining a reformulated toothpaste, toothbrush, and mouthwash designed to work together as an integrated oral care regime, responding to rising consumer adoption of multi-product routines. Companies can develop integrated multi-product oral care systems to capture rising consumer demand for coordinated treatment regimes.
Oral care manufacturers continue investing in smaller, more affordable pack sizes to overcome persistent affordability barriers limiting penetration across rural India. Industry data published in May 2026 confirmed that rural markets continue contributing to volume growth through increased penetration of affordable SKUs, even as urban markets drive premiumisation and quick-commerce expansion reshapes overall distribution dynamics nationwide. Companies can introduce smaller, more affordable pack sizes to expand penetration across price-sensitive rural markets nationwide.
Digital-first retail platforms continue capturing a growing share of oral care purchases as legacy FMCG conglomerates increasingly invest directly in digital-native consumer brands. Dabur launched a dedicated INR500 crore investment platform in October 2025 to back high-growth direct-to-consumer businesses across personal care, healthcare, wellness, and Ayurveda, signalling continued legacy FMCG investment in digital consumer channels beyond organic e-commerce growth. Companies can invest directly in digital-native consumer brands to strengthen online distribution capabilities.
Therapeutic toothpaste formulations addressing sensitivity, gum care, and whitening continue gaining share as dental awareness campaigns expand across India's urban and semi-urban population. Lion Corporation launched two new medicated toothpaste products in its Dent Health range in October 2026, formulated to prevent periodontitis through anti-inflammatory and multi-function ingredients, reflecting sustained global innovation investment in therapeutic oral care formulations. Companies can invest in anti-inflammatory and multi-function therapeutic formulations to capture accelerating demand for targeted oral health benefits nationwide.
This Expert Market Research Report titled "India Toothpaste Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Product Type
Key Insight: Standard Toothpaste accounts for the largest share of the market, reflecting sustained demand for everyday cleaning formulations across mass and premium price tiers nationwide. Functional/Medicated Toothpaste is growing fastest at a projected 6.30 percent CAGR as consumers increasingly seek therapeutic benefits, illustrated by Sensodyne's March 2026 Know Your Dental Age campaign launched with India's Ministry of Health and the Indian Dental Association.
Market Breakup by Category
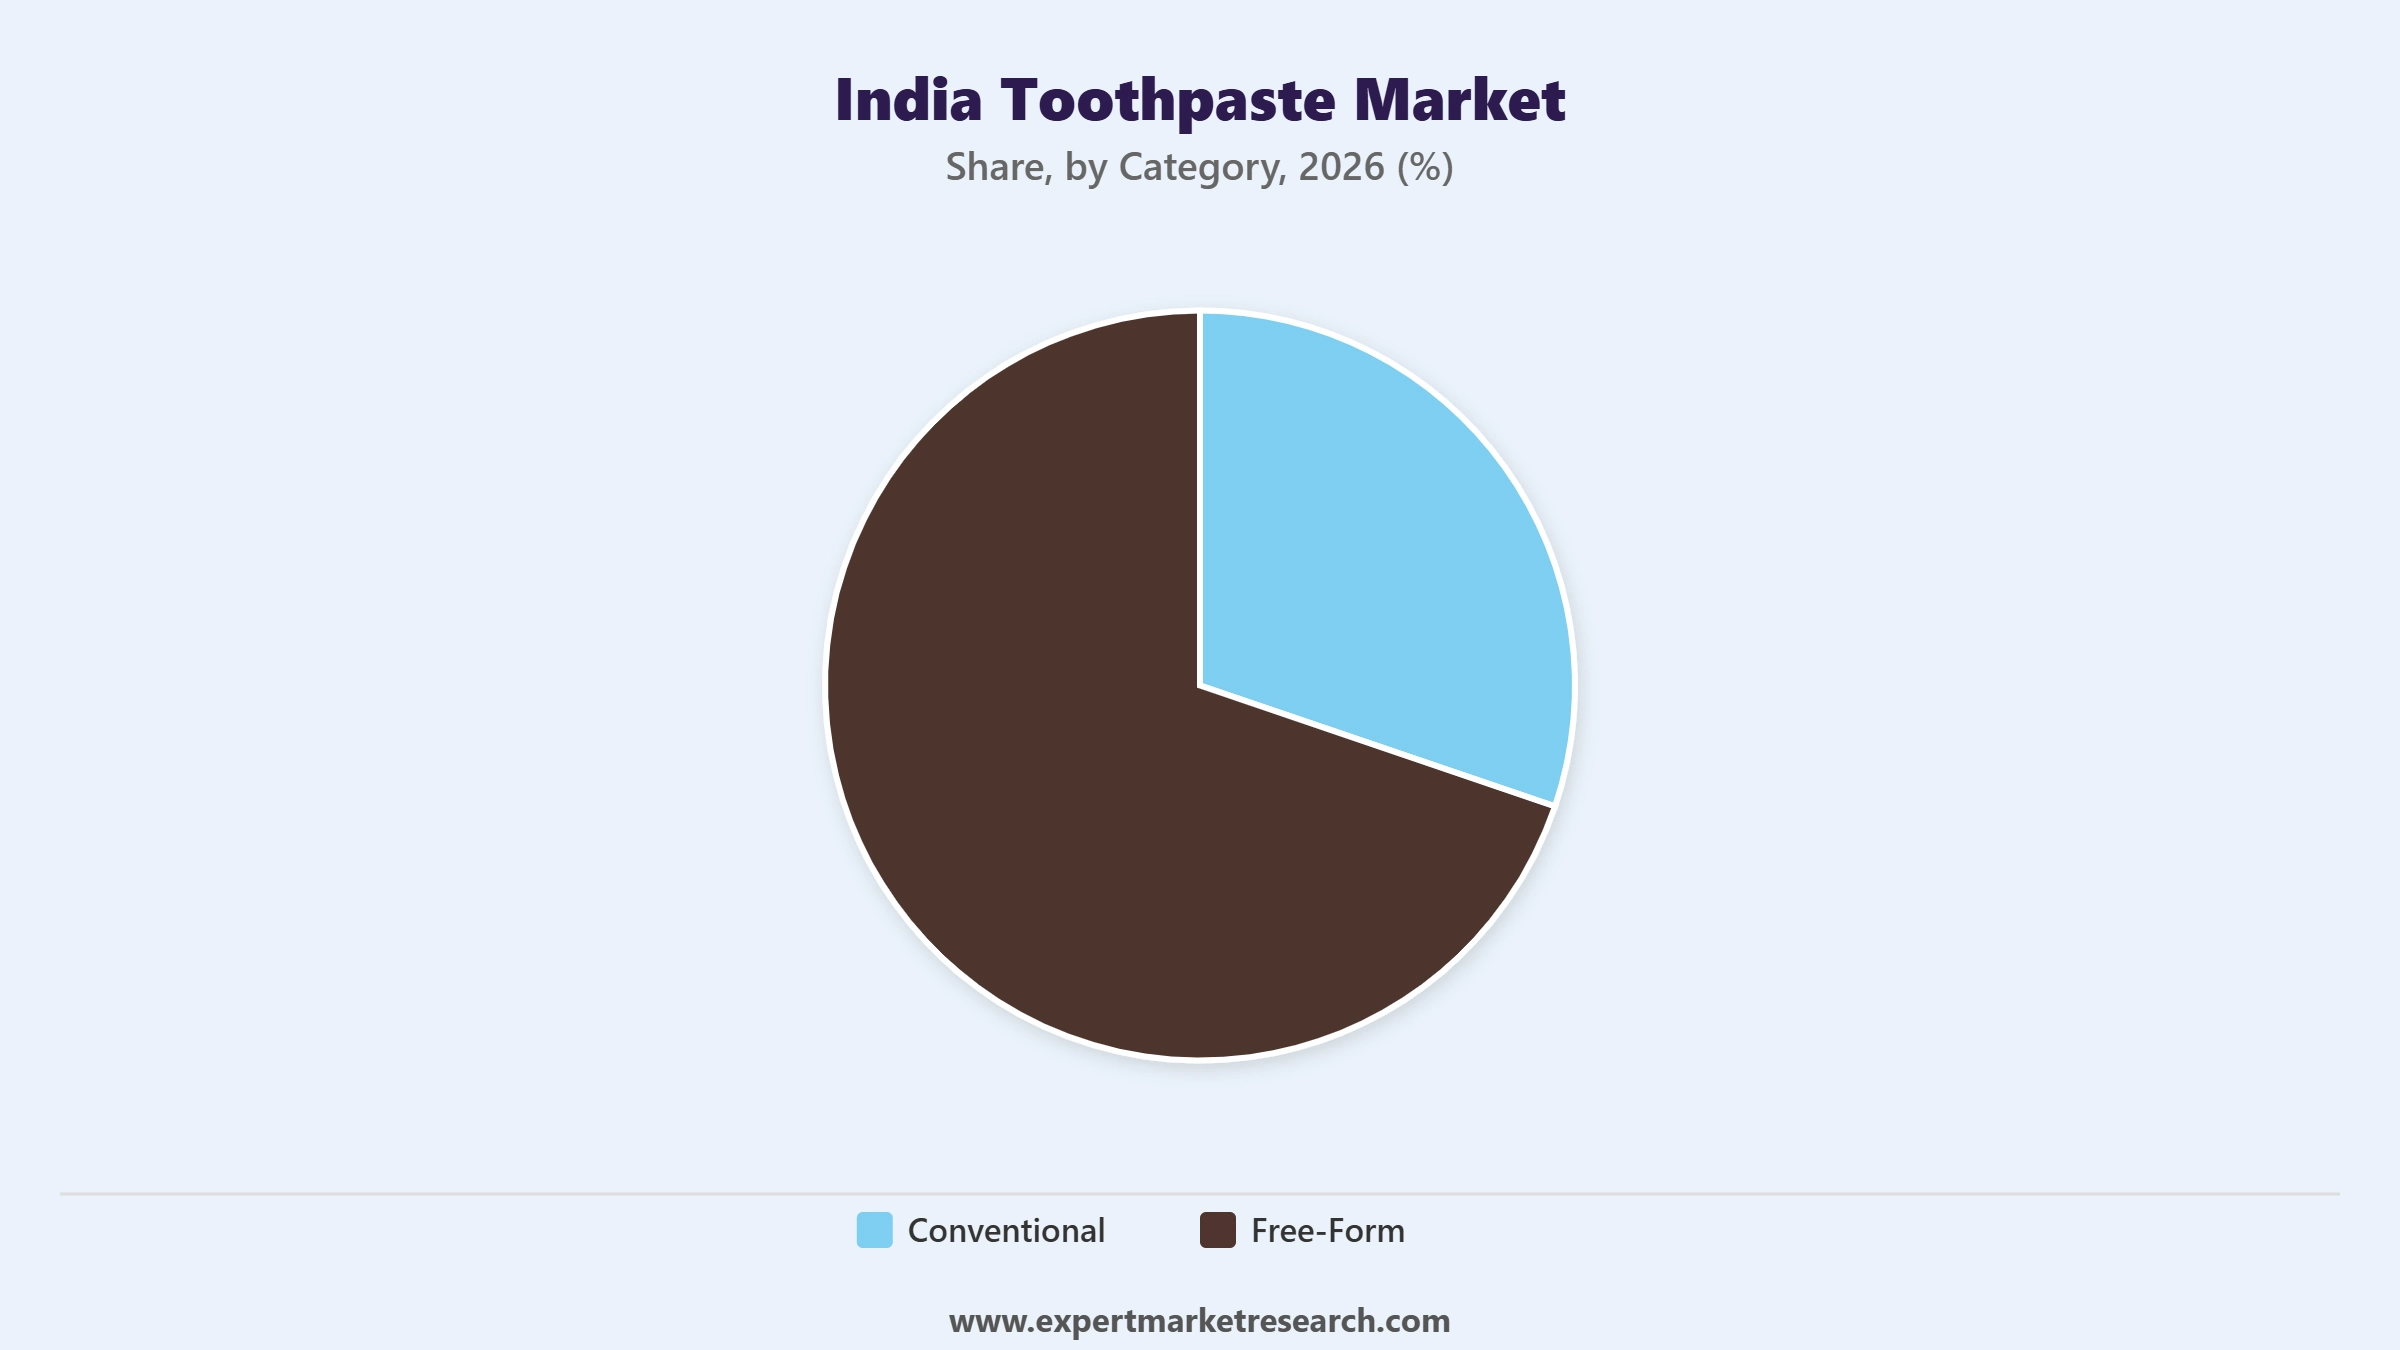
Key Insight: Conventional formulations account for the largest share of the market, reflecting continued reliance on fluoride-based cleaning agents across most price tiers nationwide. Free-Form formulations, including natural and Ayurvedic variants free of synthetic additives, are gaining share fastest, reinforced by August 2026 industry data valuing the ayurvedic toothpaste segment at approximately USD1.6 billion and growing at a 14.08 percent CAGR through 2031.
Market Breakup by End Use
Key Insight: Adults accounts for the largest share of the market, reflecting the broadest historical product range and highest cumulative marketing investment across decades of brand development nationwide. Kids continues to represent a distinct and growing category, with Sensodyne's Haleon parent expanding its Pronamel Kids formulation and dental screening initiatives targeting younger consumers and their families across the country. Industry data published in August 2026 confirmed kids' toothpaste as one of the fastest-growing end-use categories, as parents increasingly seek age-appropriate, low-fluoride formulations with child-friendly flavours and packaging.
Market Breakup by Distribution Channel
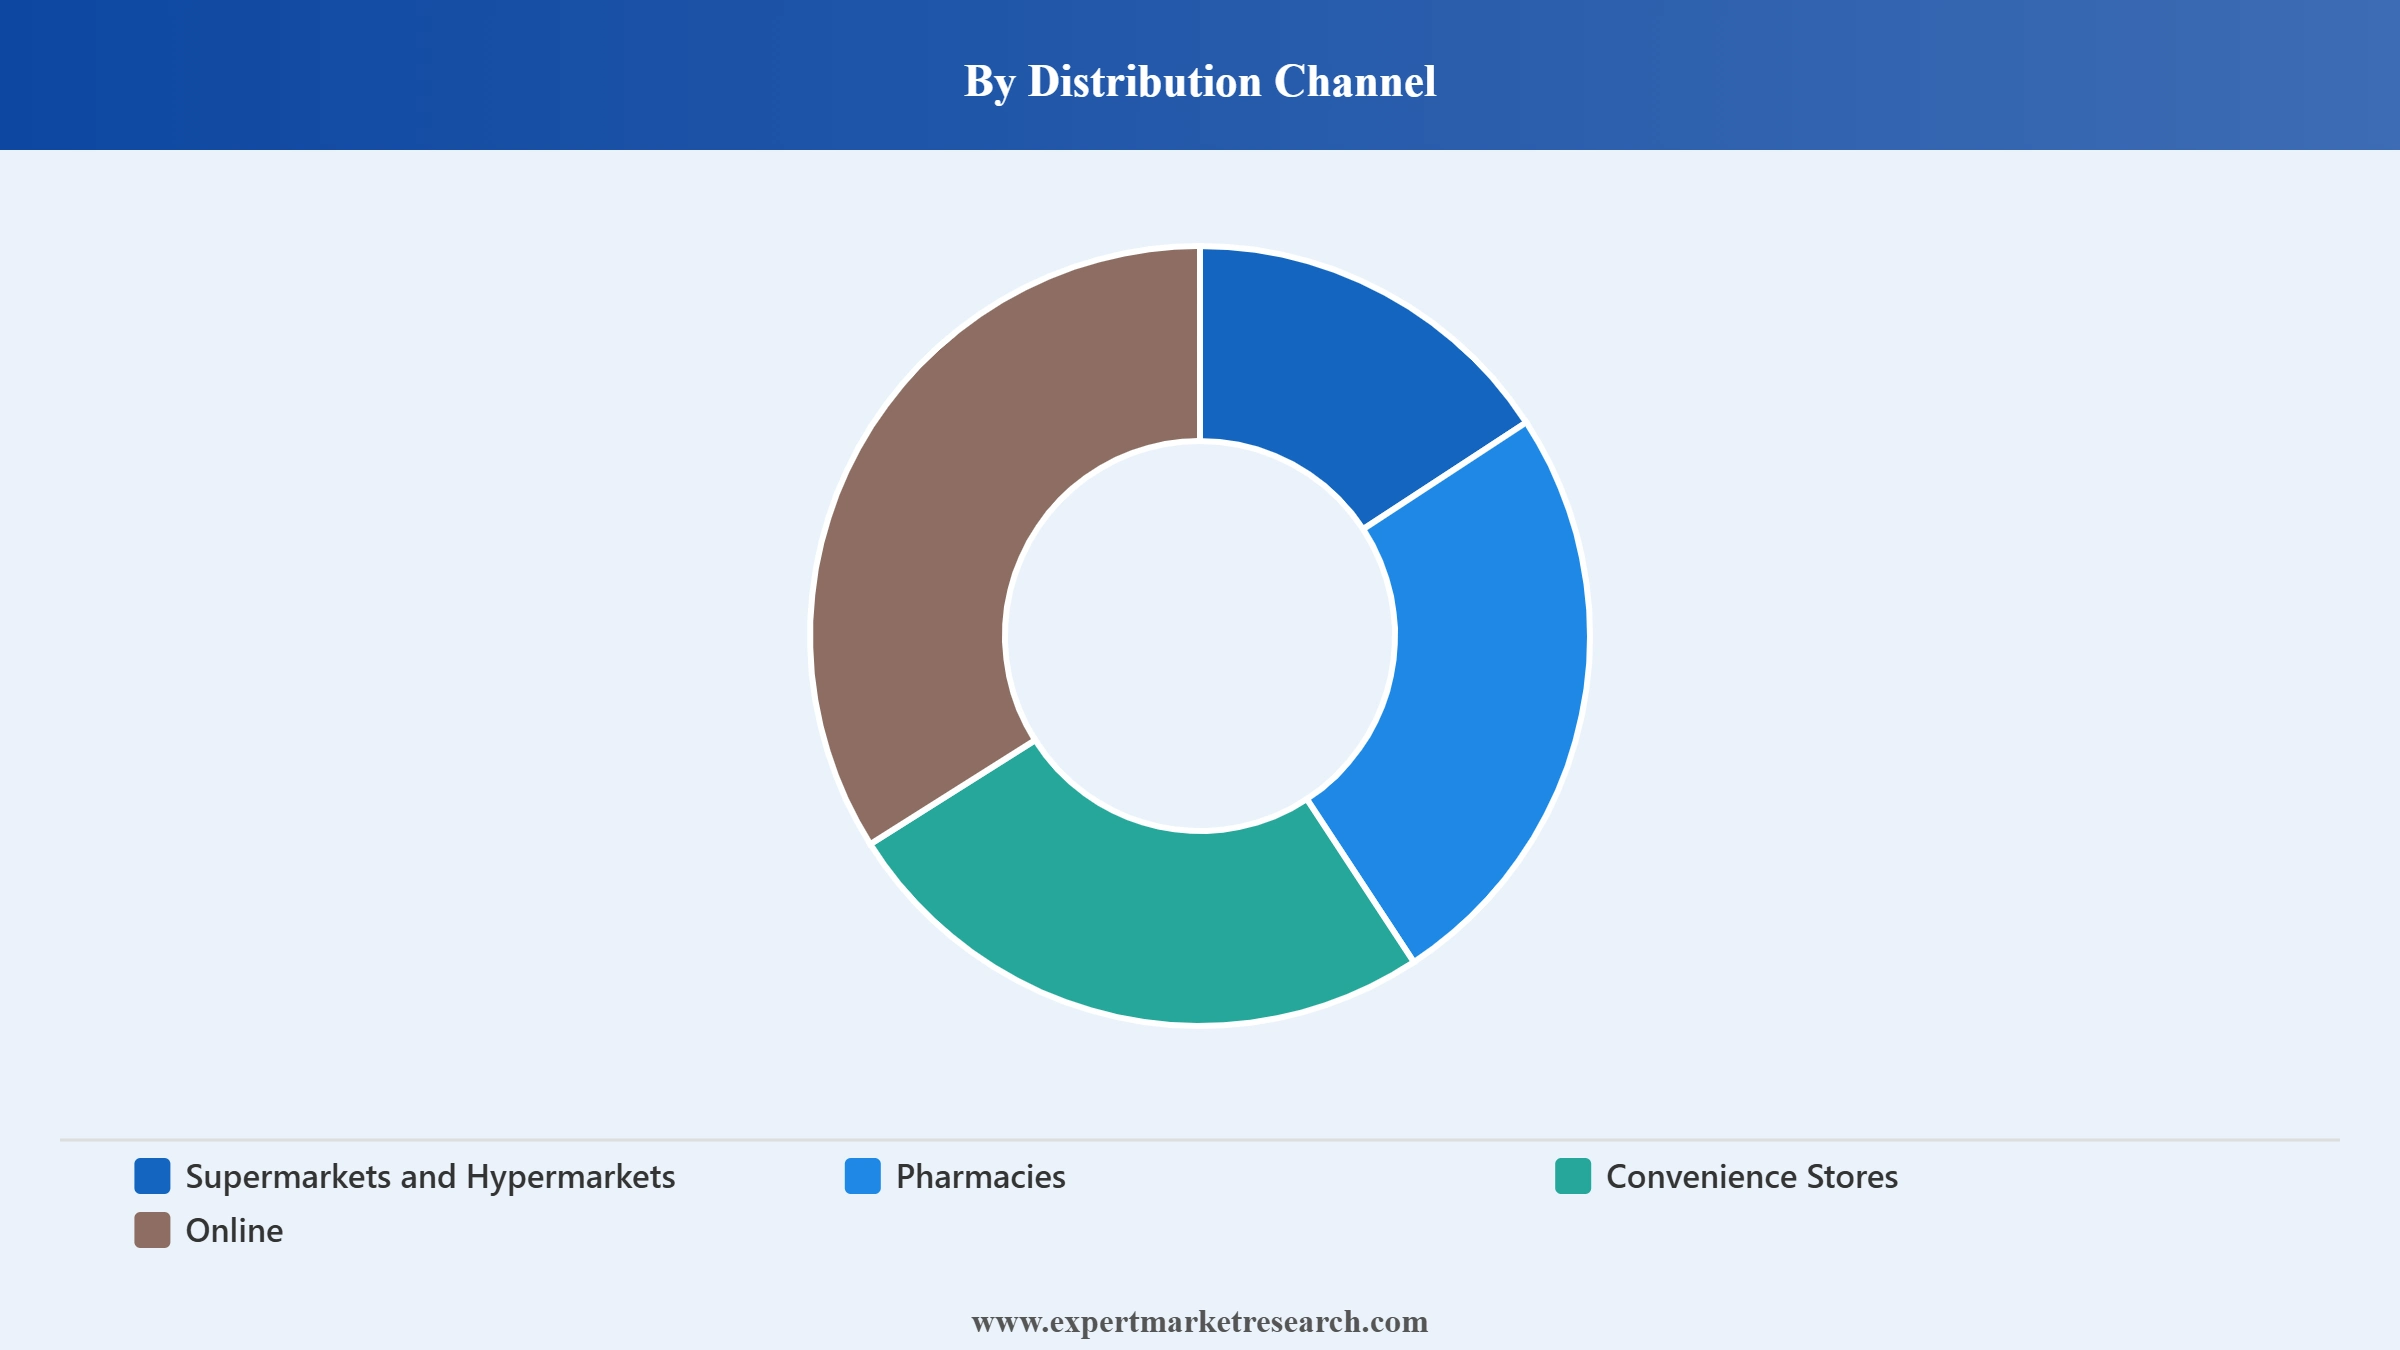
Key Insight: Supermarkets and Hypermarkets accounts for the largest share of the market, offering broad assortment across mass and premium brands through organised retail nationwide. Pharmacies continue to serve consumers seeking therapeutic and dentist-recommended formulations, while Convenience Stores and Others, including kirana stores, remain central to rural and semi-urban distribution. Online is growing fastest at a projected 7.80 percent CAGR, reinforced by industry data published in September 2026 showing quick-commerce platforms increasingly stocking niche herbal and sensitivity-focused toothpaste brands alongside mainstream options nationwide.
Market Breakup by Region
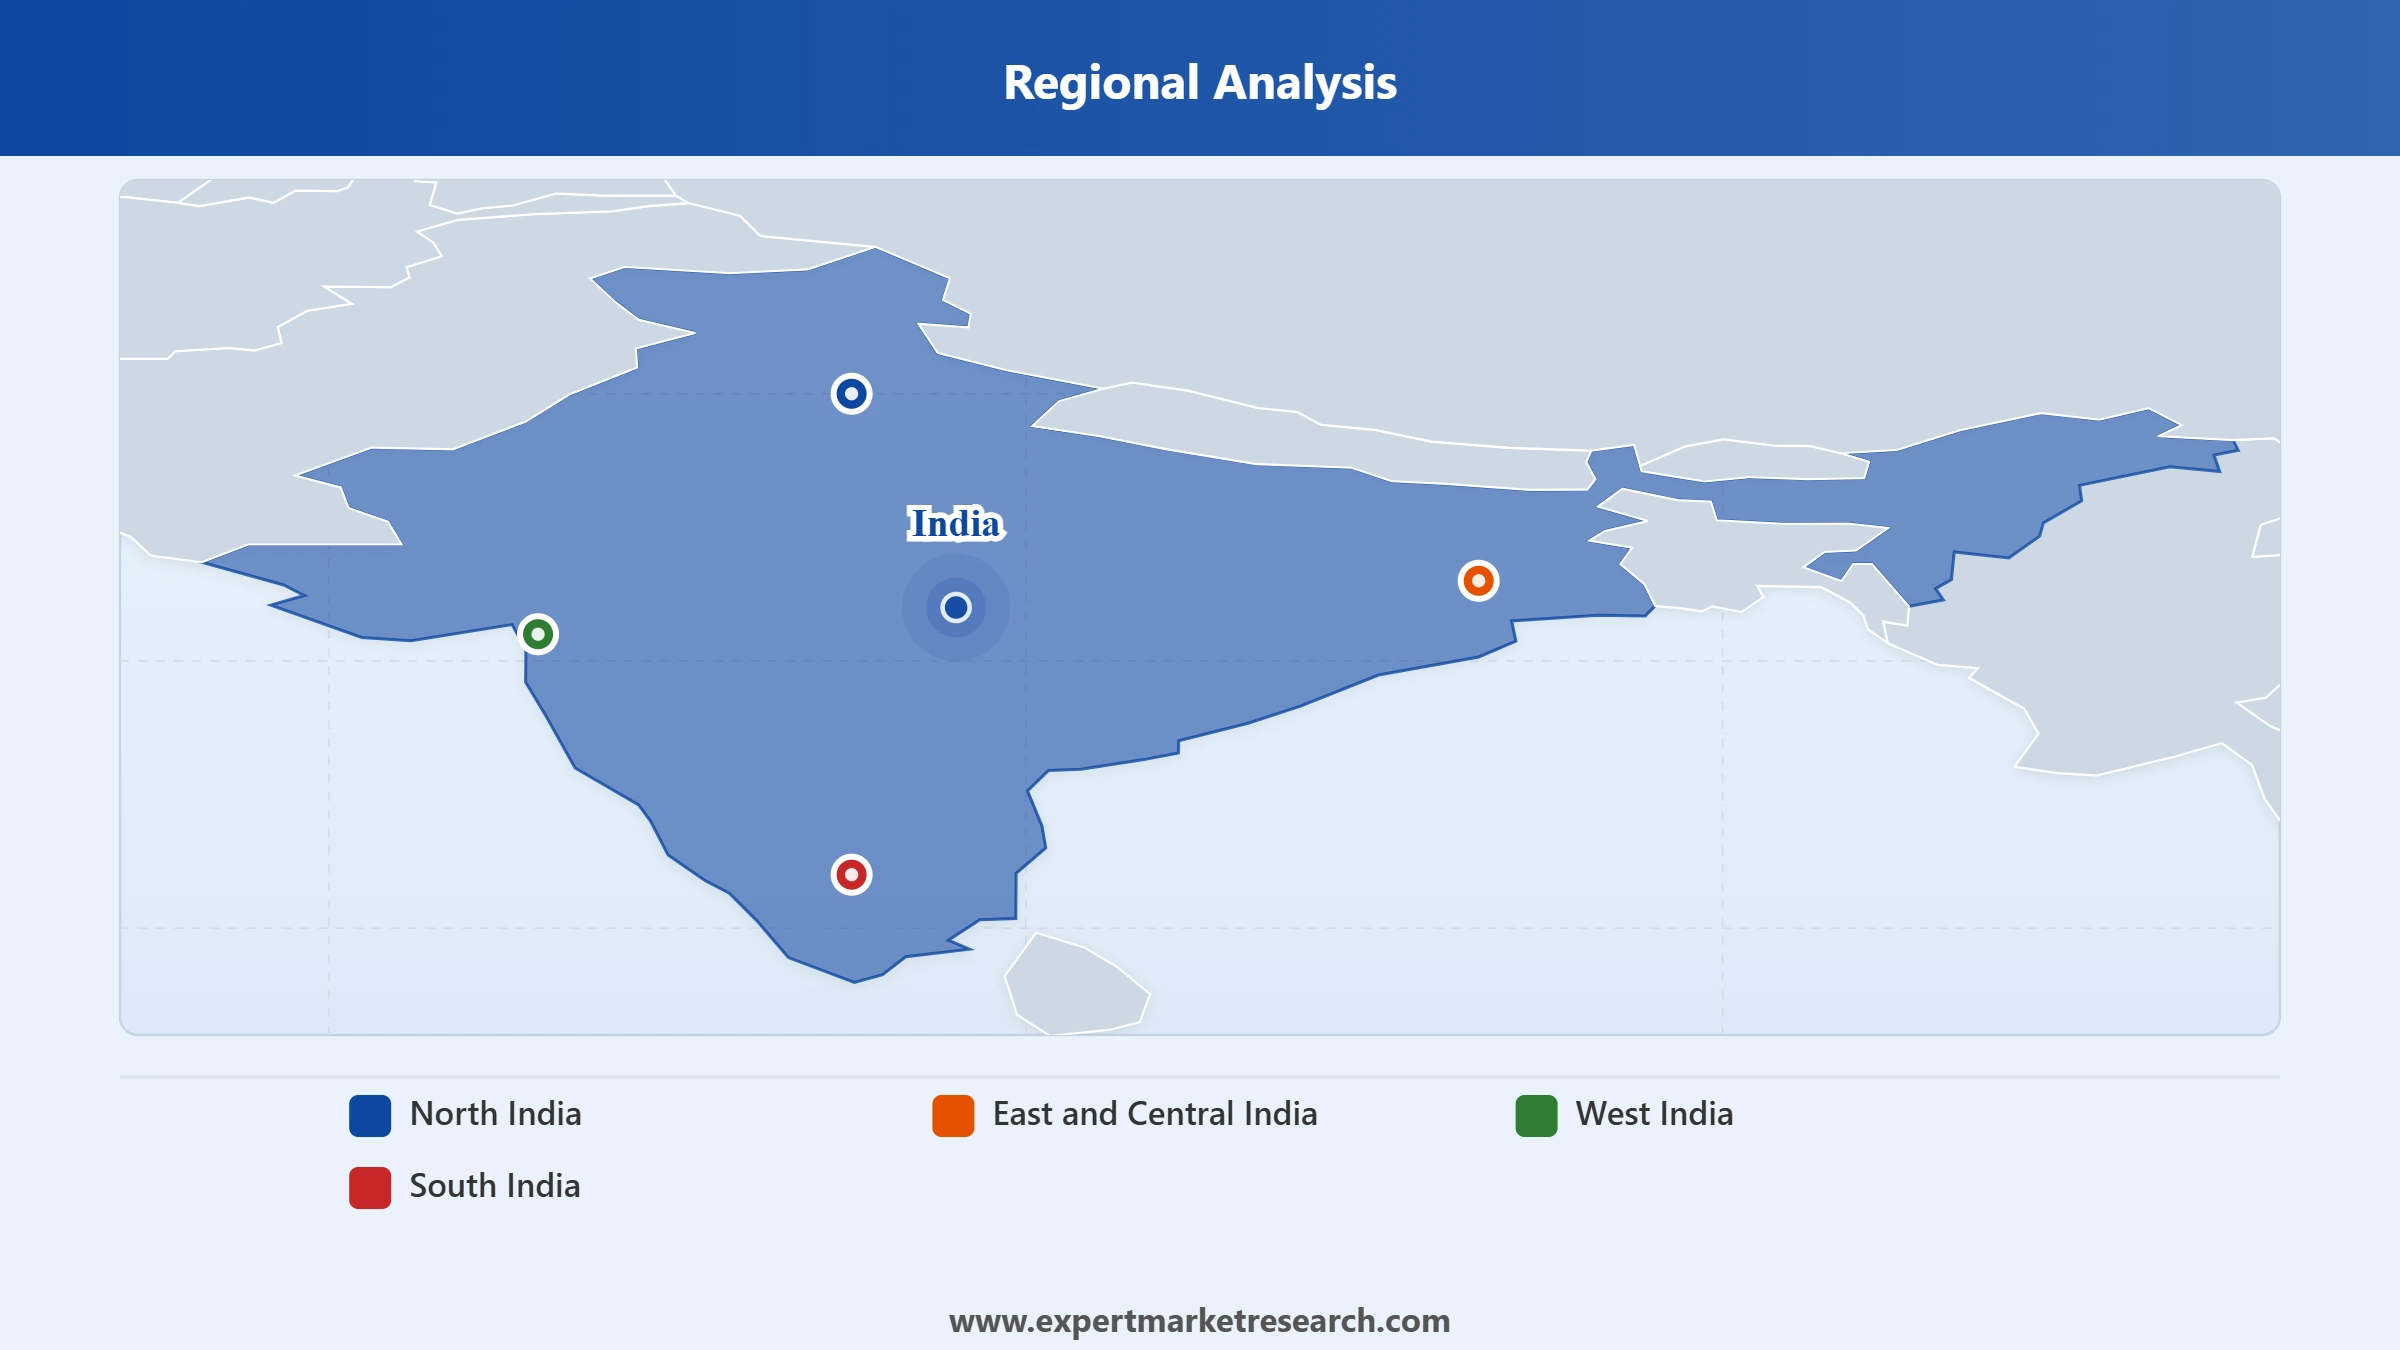
Key Insight: North India accounts for the largest share of the market, supported by its large population base and concentrated urban distribution across Delhi NCR. West India continues to represent substantial demand tied to Mumbai and Pune's dense organised retail networks. East and Central India serves a smaller but steadily expanding base as rural distribution reach improves. South India is growing fastest at an estimated 5.60 percent CAGR, supported by rising urban oral hygiene awareness and expanding organised retail penetration across Bengaluru, Chennai, and Hyderabad, with industry data published in July 2026 highlighting Karnataka and Tamil Nadu as among the fastest-growing state-level markets for premium and herbal toothpaste variants.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Standard Toothpaste continues to account for the largest share of the market, reflecting sustained demand for everyday cleaning formulations across mass and premium price tiers nationwide. Colgate-Palmolive continues to command approximately 43 percent of overall market value as of 2025, anchoring the standard formulation segment across both urban and rural distribution channels.

Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Functional/Medicated is the fastest-growing product type at a projected 6.30 percent CAGR. Industry data published in May 2026 confirmed accelerating adoption of specialised products such as sensitivity toothpaste and gum care solutions, as urban consumers increasingly seek formulations addressing specific oral health concerns beyond basic cleaning.
Conventional formulations continue to account for the largest share of the market, reflecting continued reliance on fluoride-based cleaning agents across most price tiers and distribution channels nationwide. Established multinational brands continue anchoring the conventional segment through extensive rural and urban distribution networks built over decades.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Free-Form is growing fastest as natural and Ayurvedic positioning gains traction among health-conscious consumers. Industry analysis published in March 2026 noted that India's oral care e-commerce activity, within a broader digital retail market exceeding USD90 billion, increasingly drives discovery of natural and herbal formulations even as offline purchase remains common among rural and semi-urban consumers.
Adults continues to account for the largest share of the market, reflecting the broadest historical product range and highest cumulative marketing investment across decades of brand development nationwide. Established brands continue prioritising adult-focused therapeutic and whitening formulations across premium price tiers.

Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Kids is gaining share as dental awareness campaigns increasingly target families and younger consumers. Dabur's September 2025 Swadeshi campaign reinforced domestic brand positioning across family-oriented retail channels, appealing to price-conscious households seeking trusted, locally made alternatives.
Supermarkets and Hypermarkets continues to account for the largest share of the market, offering broad assortment across mass and premium brands through organised retail nationwide. Colgate-Palmolive's February 2026 partnership with the Government of Haryana reinforced brand visibility across both organised and school-linked distribution channels statewide.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Online is the fastest-growing distribution channel at a projected 7.80 percent CAGR as e-commerce platforms expand ingredient filters and subscription-based replenishment options nationwide, appealing particularly to premium and herbal formulation buyers seeking convenience and ingredient transparency.
Delhi NCR and surrounding urban centres continue to anchor the region's outsized contribution to national toothpaste demand, supported by dense organised retail networks and sustained multinational brand investment across North India.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
West India continues to represent substantial demand tied to Mumbai and Pune's dense organised retail networks, while East and Central India serves a smaller but steadily expanding base as rural distribution reach improves. South India is the fastest-growing region at an estimated 5.60 percent CAGR, supported by rising urban oral hygiene awareness and expanding organised retail penetration across Bengaluru, Chennai, and Hyderabad, reinforced by Colgate-Palmolive's continued school-linked awareness programmes across southern states.
The industry is fragmented, with India toothpaste market companies ranging from global multinational conglomerates to domestic Ayurvedic specialists competing across product type, category, end use, and distribution channel segments nationwide.
Competitive dynamics among India toothpaste players are increasingly shaped by the depth of natural ingredient positioning, the strength of government health partnerships, and the reach of rural distribution networks. Manufacturers are investing in therapeutic formulation research, dental association partnerships, and affordable pack sizes to secure long-term relationships with both urban and rural consumers.
Founded in 1806 and headquartered in New York, United States, Colgate-Palmolive is the leading oral care company in India, commanding approximately 43 percent of the market by value as of 2025. The company partnered with the Government of Haryana in February 2026 to roll out its Bright Smiles, Bright Futures initiative, targeting 57 lakh school children with oral hygiene education and dental kits. Colgate-Palmolive's sustained market leadership and government partnership depth differentiate its offering from smaller domestic and multinational competitors.
Founded in 1884 and headquartered in Ghaziabad, India, Dabur is a leading Ayurveda-focused FMCG company commanding approximately 17 percent of India's oral care market by value. The company launched a nationwide Swadeshi campaign in September 2025 positioning its toothpaste as a domestically made alternative to Colgate amid worsening US-India trade relations. Dabur's Ayurvedic heritage and domestic sourcing narrative differentiate its offering from multinational competitors reliant on imported brand positioning.
Founded in 2000 and headquartered in London, United Kingdom, GSK's consumer healthcare lineage continues through Haleon, the spun-off company now marketing the Sensodyne brand across India. Sensodyne launched its Know Your Dental Age campaign in March 2026 alongside India's Ministry of Health and the Indian Dental Association, introducing a QR-based dental age assessment tool nationwide. GSK's therapeutic sensitivity-focused positioning differentiates its offering from mass-market conventional toothpaste competitors.
Founded in 2006 and headquartered in Haridwar, India, Patanjali Ayurved is a leading Ayurvedic personal care company whose Dant Kanti toothpaste range has become one of the fastest-growing brands within India's natural oral care segment. The company remains one of the two largest players within the ayurvedic toothpaste segment, valued at approximately USD1.6 billion as of 2026 and growing at a 14.08 percent CAGR through 2031. Patanjali's Ayurvedic authenticity and loyal domestic consumer base differentiate its offering from multinational conventional toothpaste competitors.
Other key players in the India toothpaste market include Procter & Gamble Co., Unilever Plc, SUNSTAR Suisse SA, Lion Corp., Amway Corp., and Kobayashi Pharmaceutical Co., Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our India toothpaste market trends 2026 report. Discover regional growth patterns, product type and distribution channel adoption trends, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 1501.02 Million.
The market is projected to grow at a CAGR of 4.23% between 2026 and 2035.
The revenue generated from the toothpaste market is expected to reach USD 2271.51 Million in 2035.
Based on product type, the toothpaste market is divided between standard toothpaste and functional/medicated toothpaste.
The key players in the market include Colgate-Palmolive Company, Dabur India Ltd., GSK Plc, Patanjali Ayurved Limited, Procter & Gamble Co., Unilever Plc, SUNSTAR Suisse SA, Lion Corp., Amway Corp., and Kobayashi Pharmaceutical Co., Ltd.
Based on the category, the market is divided into conventional and free forms.
The toothpaste market is categorised based on distribution channels, which include supermarkets and hypermarkets, convenience stores, speciality stores, and online, among others.
Based on region, the market is broken down into North India, East and Central India, West India, and South India.
Manufacturers face intense price competition, limited penetration in affordability-constrained rural areas, and the need for continuous differentiation amid a highly saturated field of global and domestic brands.
Partnering with government health bodies and dental associations, expanding natural and Ayurvedic ingredient positioning, launching affordable pack sizes for rural markets, and strengthening digital-first distribution.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Product Type |
|
| Breakup by Category |
|
| Breakup by End Use |
|
| Breakup by Distribution Channel |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




