

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
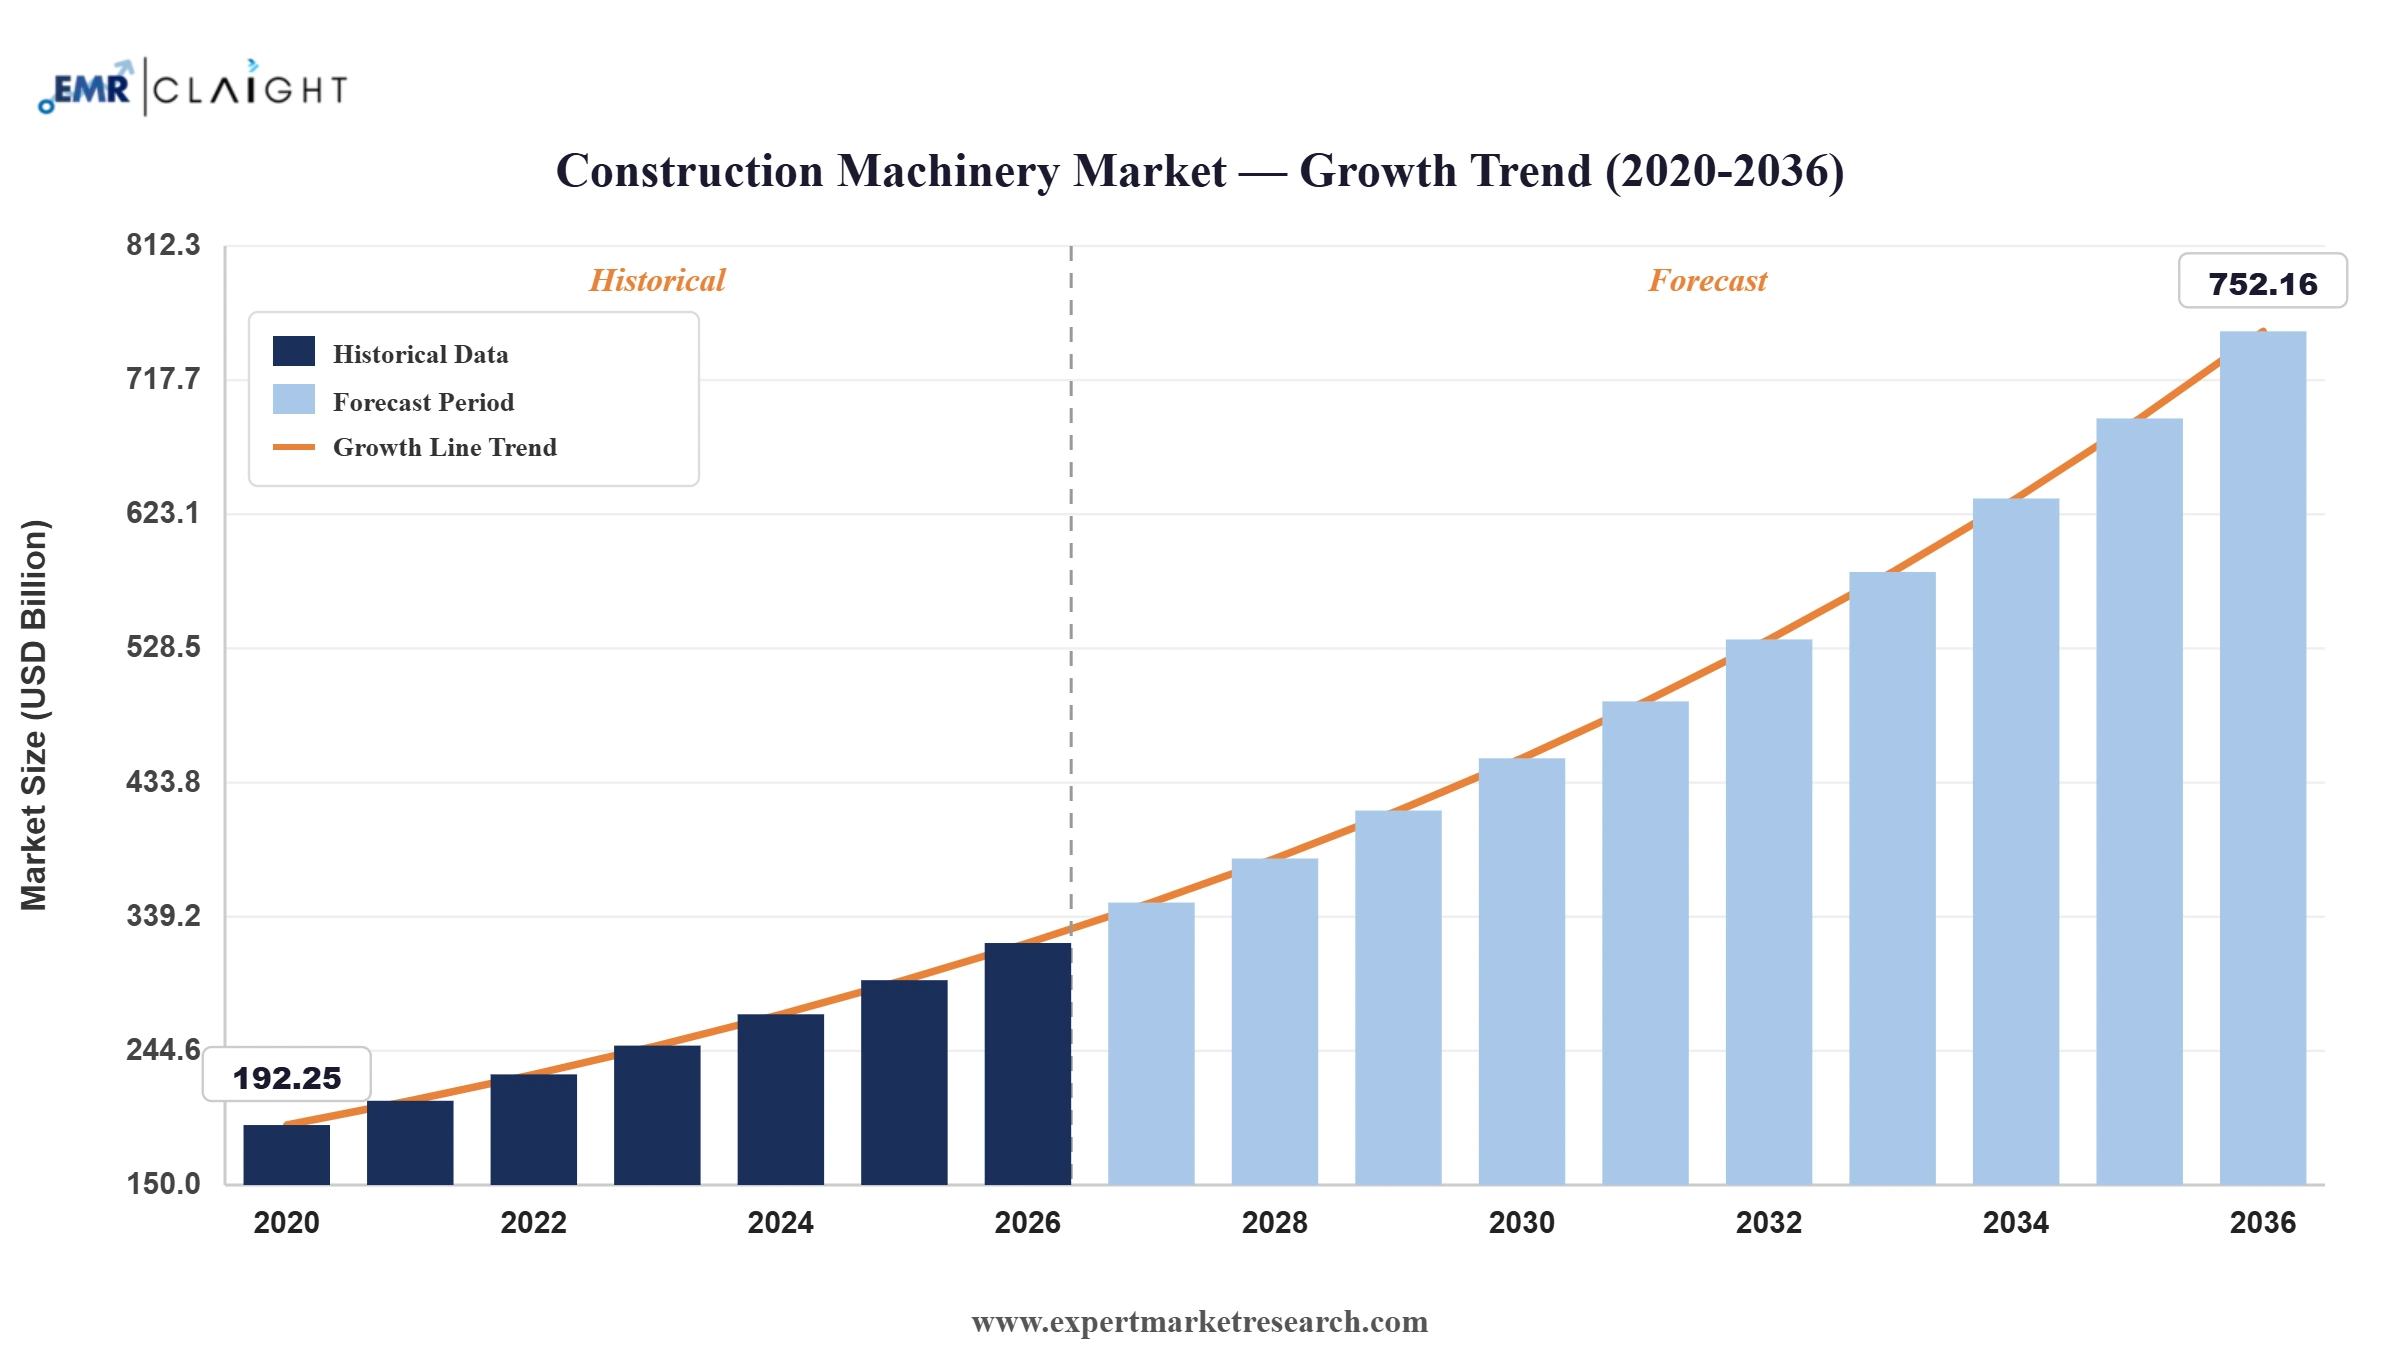
The global construction machinery market attained a value of USD 294.44 Billion in 2025 and is projected to expand at a CAGR of 8.90% through 2035. The market is further expected to achieve USD 690.68 Billion by 2035, driven by infrastructure and urbanisation spending, replacement of ageing fleets, rental fleet expansion, and the shift toward electric, hybrid, and digitally connected equipment worldwide.
Demand momentum is visible in manufacturer results. Volvo Construction Equipment reported in July 2026 that organic net sales rose 13% in the three months ended June 2026, with machine sales up 14%, service sales up 9%, and an adjusted operating margin of 14.4%. Infrastructure investment, high machine utilisation, and fleet replacement supported demand in Europe, while data centres and energy projects kept North America resilient. These results show that manufacturers with strong service businesses and healthy margins are well placed to benefit while demand stays firm across both regions.
Policy and pricing shape the outlook as much as volume. Deere and Company said in August 2026 that it expects construction equipment industry sales in the United States and Canada to rise 5% to 10% in 2026, with global roadbuilding up about 10% and compact construction equipment up about 5%. It also recorded tariff recoveries of USD 110 million in the three months ended August 2026. Together these points show that equipment makers must weigh industry growth against trade costs, and that roadbuilding and compact equipment may move at different speeds across the market.
Emerging markets add a different growth profile. The Indian industry body ICEMA reported in May 2026 that construction equipment sales in the year ended March 2026 were 136,995 units, down about 2%, while exports rose about 32%. It attributed the dip to slower infrastructure execution rather than structural weakness, expects demand to recover as project implementation improves, and pointed to a new incentive scheme for equipment makers. Suppliers watching this market need to balance a soft near-term domestic picture against export momentum and the prospect of faster project execution, which is why buyers and manufacturers follow these indicators.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
XCMG Machinery reported results for the six months ended June 2026 in September 2026, with revenue of RMB 61.25 billion, up 11.75%, and overseas revenue of RMB 30.92 billion, up 21.03%, exceeding half of the total for the first time. Earthmoving machinery revenue rose 27.80% over the same period. Companies can leverage overseas dealer and service networks to capture export demand when domestic growth moderates.
Sany Heavy Industry reported in September 2026 that revenue for the six months ended June 2026 rose 19.49% to USD 7.89 billion, with overseas revenue up 21.82% to USD 4.72 billion, or 61.33% of core business revenue. Net profit attributable to shareholders rose 9.13% to USD 838.9 million. Companies can expand export capacity and local service to turn global infrastructure demand into profitable growth.
Komatsu reported in July 2026 that construction equipment net sales in North America rose 34.8% to USD 1.2 billion in the three months ended June 2026, while global construction, mining, and utility equipment sales rose 14.4% to USD 5.9 billion. The company credited a weaker yen, which offset higher costs and a shift toward lower-margin machines. Companies can protect margins by pricing for currency swings and mix shifts.
Terex reported in July 2026 that net sales for the three months ended June 2026 rose 50.5% to USD 2,238 million, or 8.5% pro forma, while bookings rose 25.2% pro forma to USD 2.0 billion and backlog reached USD 6.9 billion. It raised its 2026 net sales outlook to USD 7.9 billion to USD 8.2 billion. Companies can leverage strong order books to plan capacity and secure supply.
JCB showed 21 products, 10 of them new, from a pavilion of about 2,000 square metres at bauma CONEXPO INDIA 2026 in Greater Noida, as reported in September 2026. The new range includes the 3DX, 3DX Plus, and 3DX Super backhoe loaders, built in India for a customer base spanning more than 135 export countries. Companies can leverage local manufacturing to serve domestic buyers and export markets together.
In April 2026, Hitachi Construction Machinery reported revenue of 1.41 trillion yen for the year ended March 2026, up 2.5%, with European revenue up 26.4% while Americas revenue fell 3.3%. Adjusted operating income declined 8.3% as tariff costs and growth investments weighed on earnings, and it guided for revenue to rise a further 1.7% in the year ending March 2027. Companies can leverage strong European demand and independent distribution to balance weaker regions.
Zoomlion reported in August 2026 that revenue for the six months ended June 2026 reached RMB 27.14 billion, up 9.17%, while international revenue rose 12.45% to RMB 15.54 billion, or 57.25% of the total. Operating cash flow rose 38.12% to RMB 2.42 billion, and sales growth in South America, Europe, Southeast Asia, Africa, and East Asia exceeded its overall international rate. Companies can leverage international growth and strong cash generation to fund localisation and new product launches.
Deere and Company announced in January 2026 a USD 70 million expansion of its excavator complex in Kernersville, North Carolina, to build future-generation excavators, with some production now in Japan moving there, alongside a parts distribution centre in Hebron, Indiana. The two sites will add more than 150 and about 150 jobs and are expected to open in 2027. Companies can secure supply resilience by localising excavator and parts capacity.
This Expert Market Research's Report titled "Construction Machinery Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
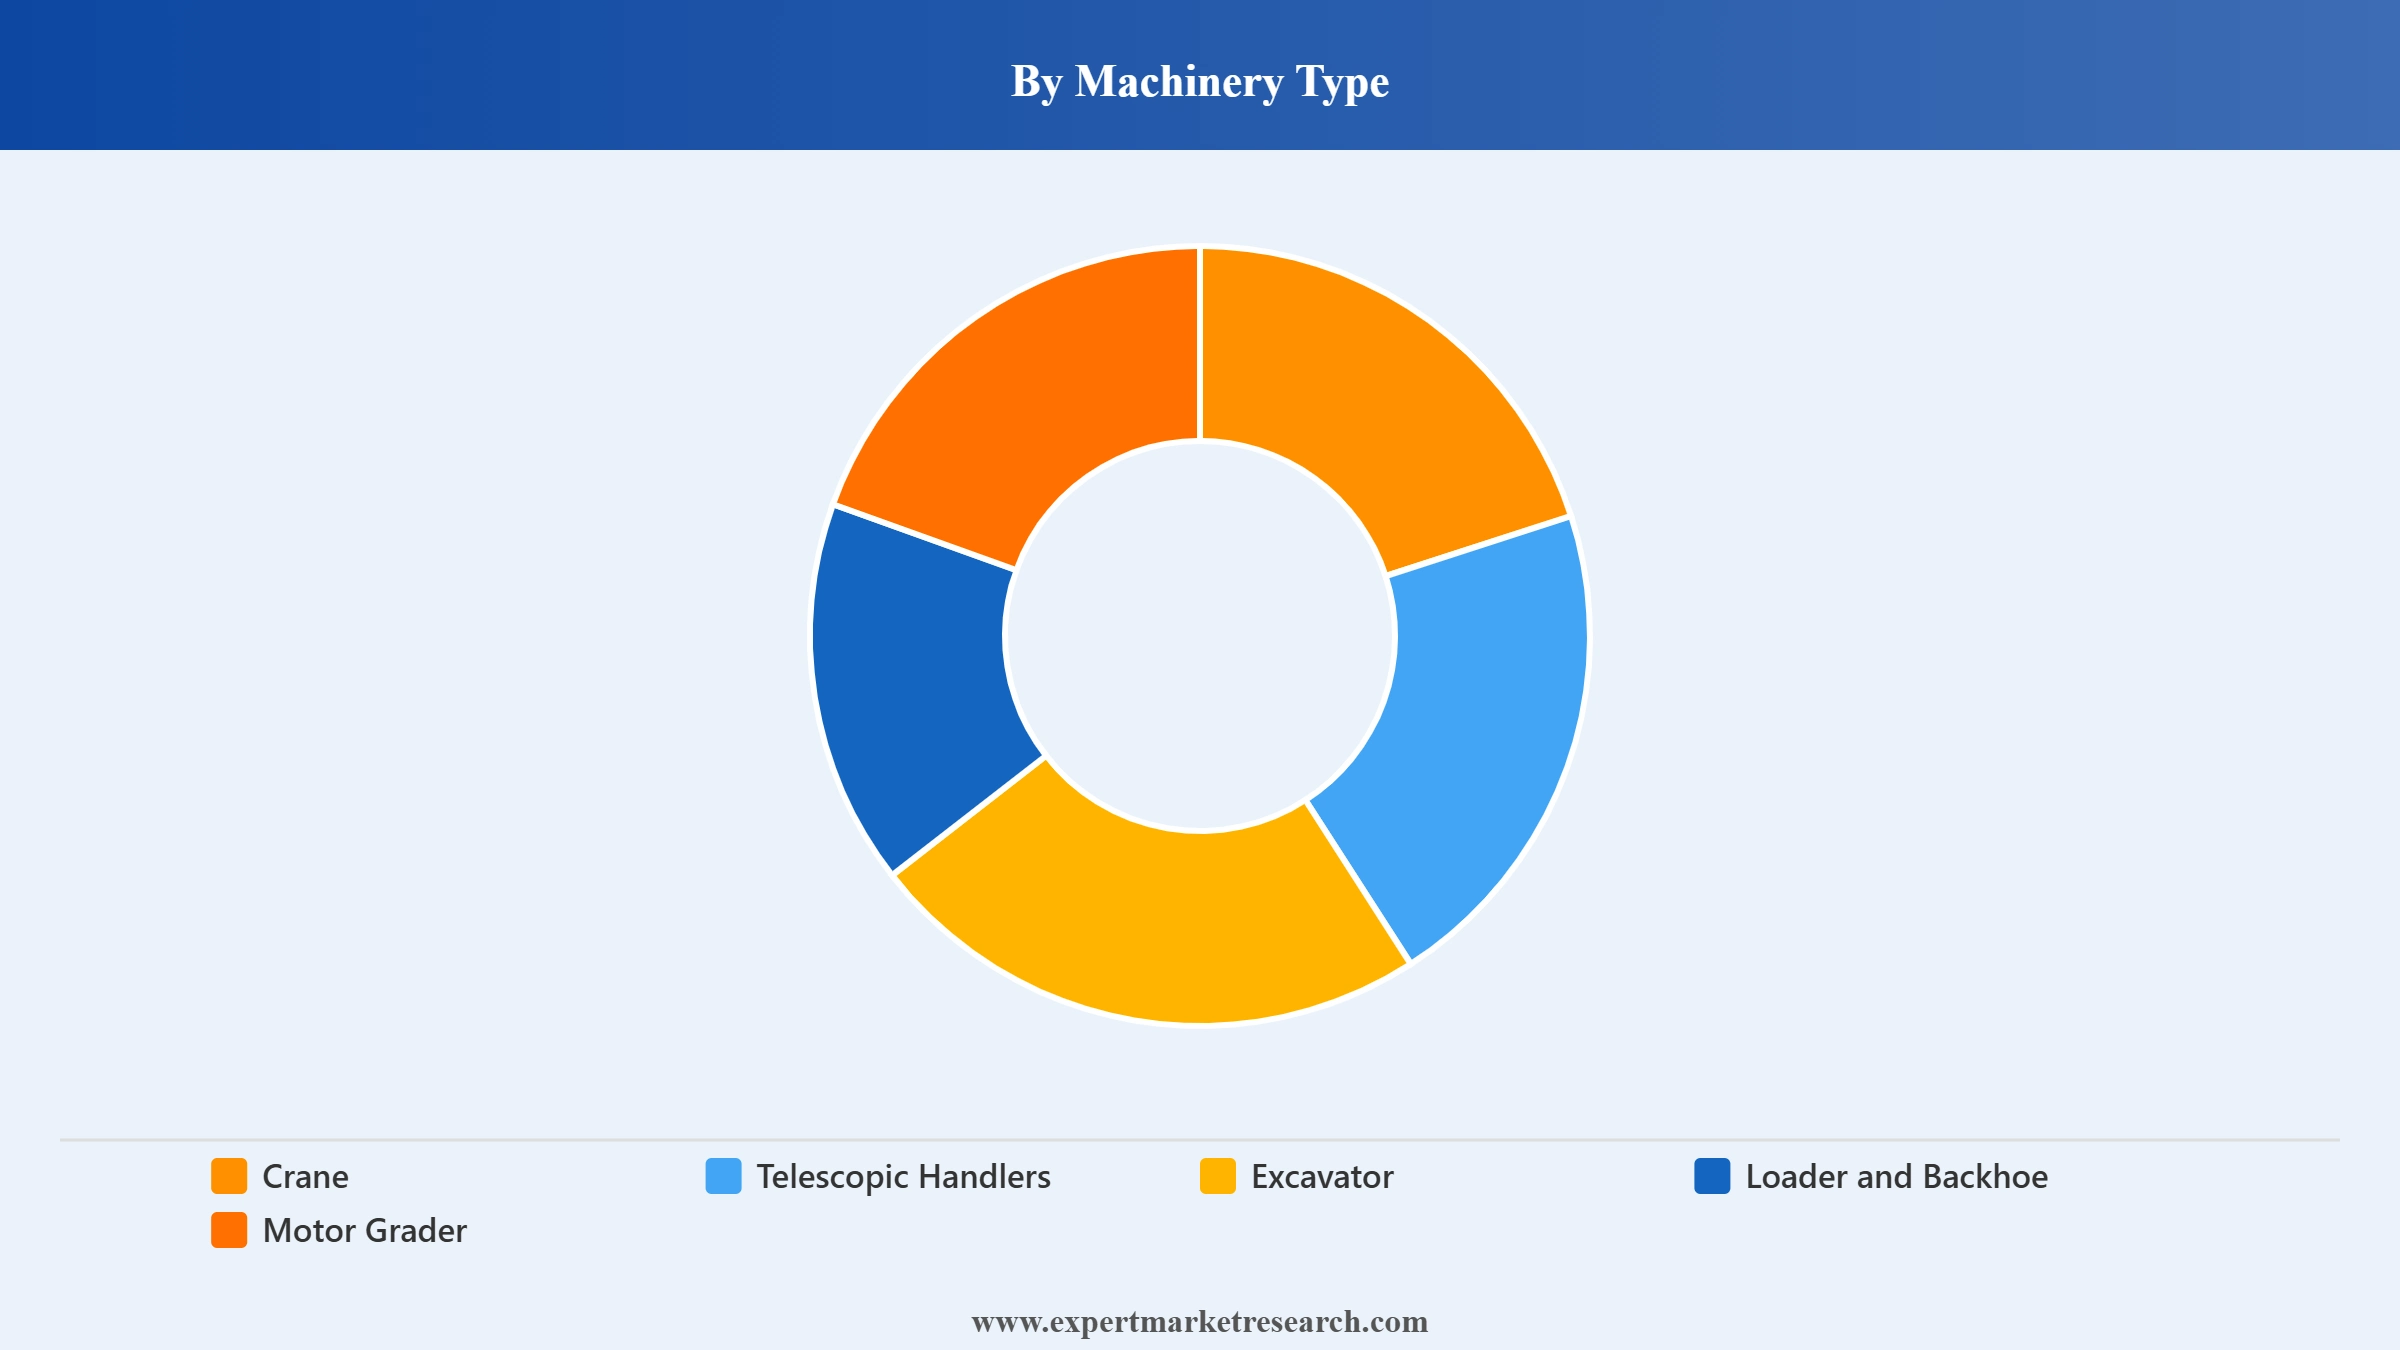
Market Breakup by Machinery Type
Key Insight: Crane demand is anchored by heavy lifting projects, with Liebherr delivering an LR 1700-1.0 crawler crane to Big B Crane at CONEXPO in March 2026, a model offering up to 15% more lifting capacity than the LR 1600/2 it was based on; Telescopic Handlers face softer North American demand, with Oshkosh reporting in August 2026 that telehandler sales fell 19% to USD 263.3 million in the three months ended June 2026; Excavator is the leading type, with Kubota reporting in May 2026 that its construction machinery revenue rose 28.6% to just over USD 1 billion in the three months ended March 2026, helped by new model launches in North America; Loader and Backhoe demand is supported by the recovery in compact equipment, with Doosan Bobcat reporting in July 2026 that revenue rose 4.1% to USD 1.63 billion in the three months ended June 2026, including a 10% gain in Europe, the Middle East, and Africa; Motor Grader supply into emerging regions is expanding, with the China Construction Machinery Association reporting in August 2026 that grader sales rose 16% to 5,763 units in January to July 2026, with exports up 24.3% to 5,036 units; and Others, including road machinery, are being refreshed, with Wirtgen Group announcing in September 2026 a W 215 P milling machine, a Vögele SUPER 3000-3i paver, and a Hamm HC 268i VC compactor for bauma China 2026.
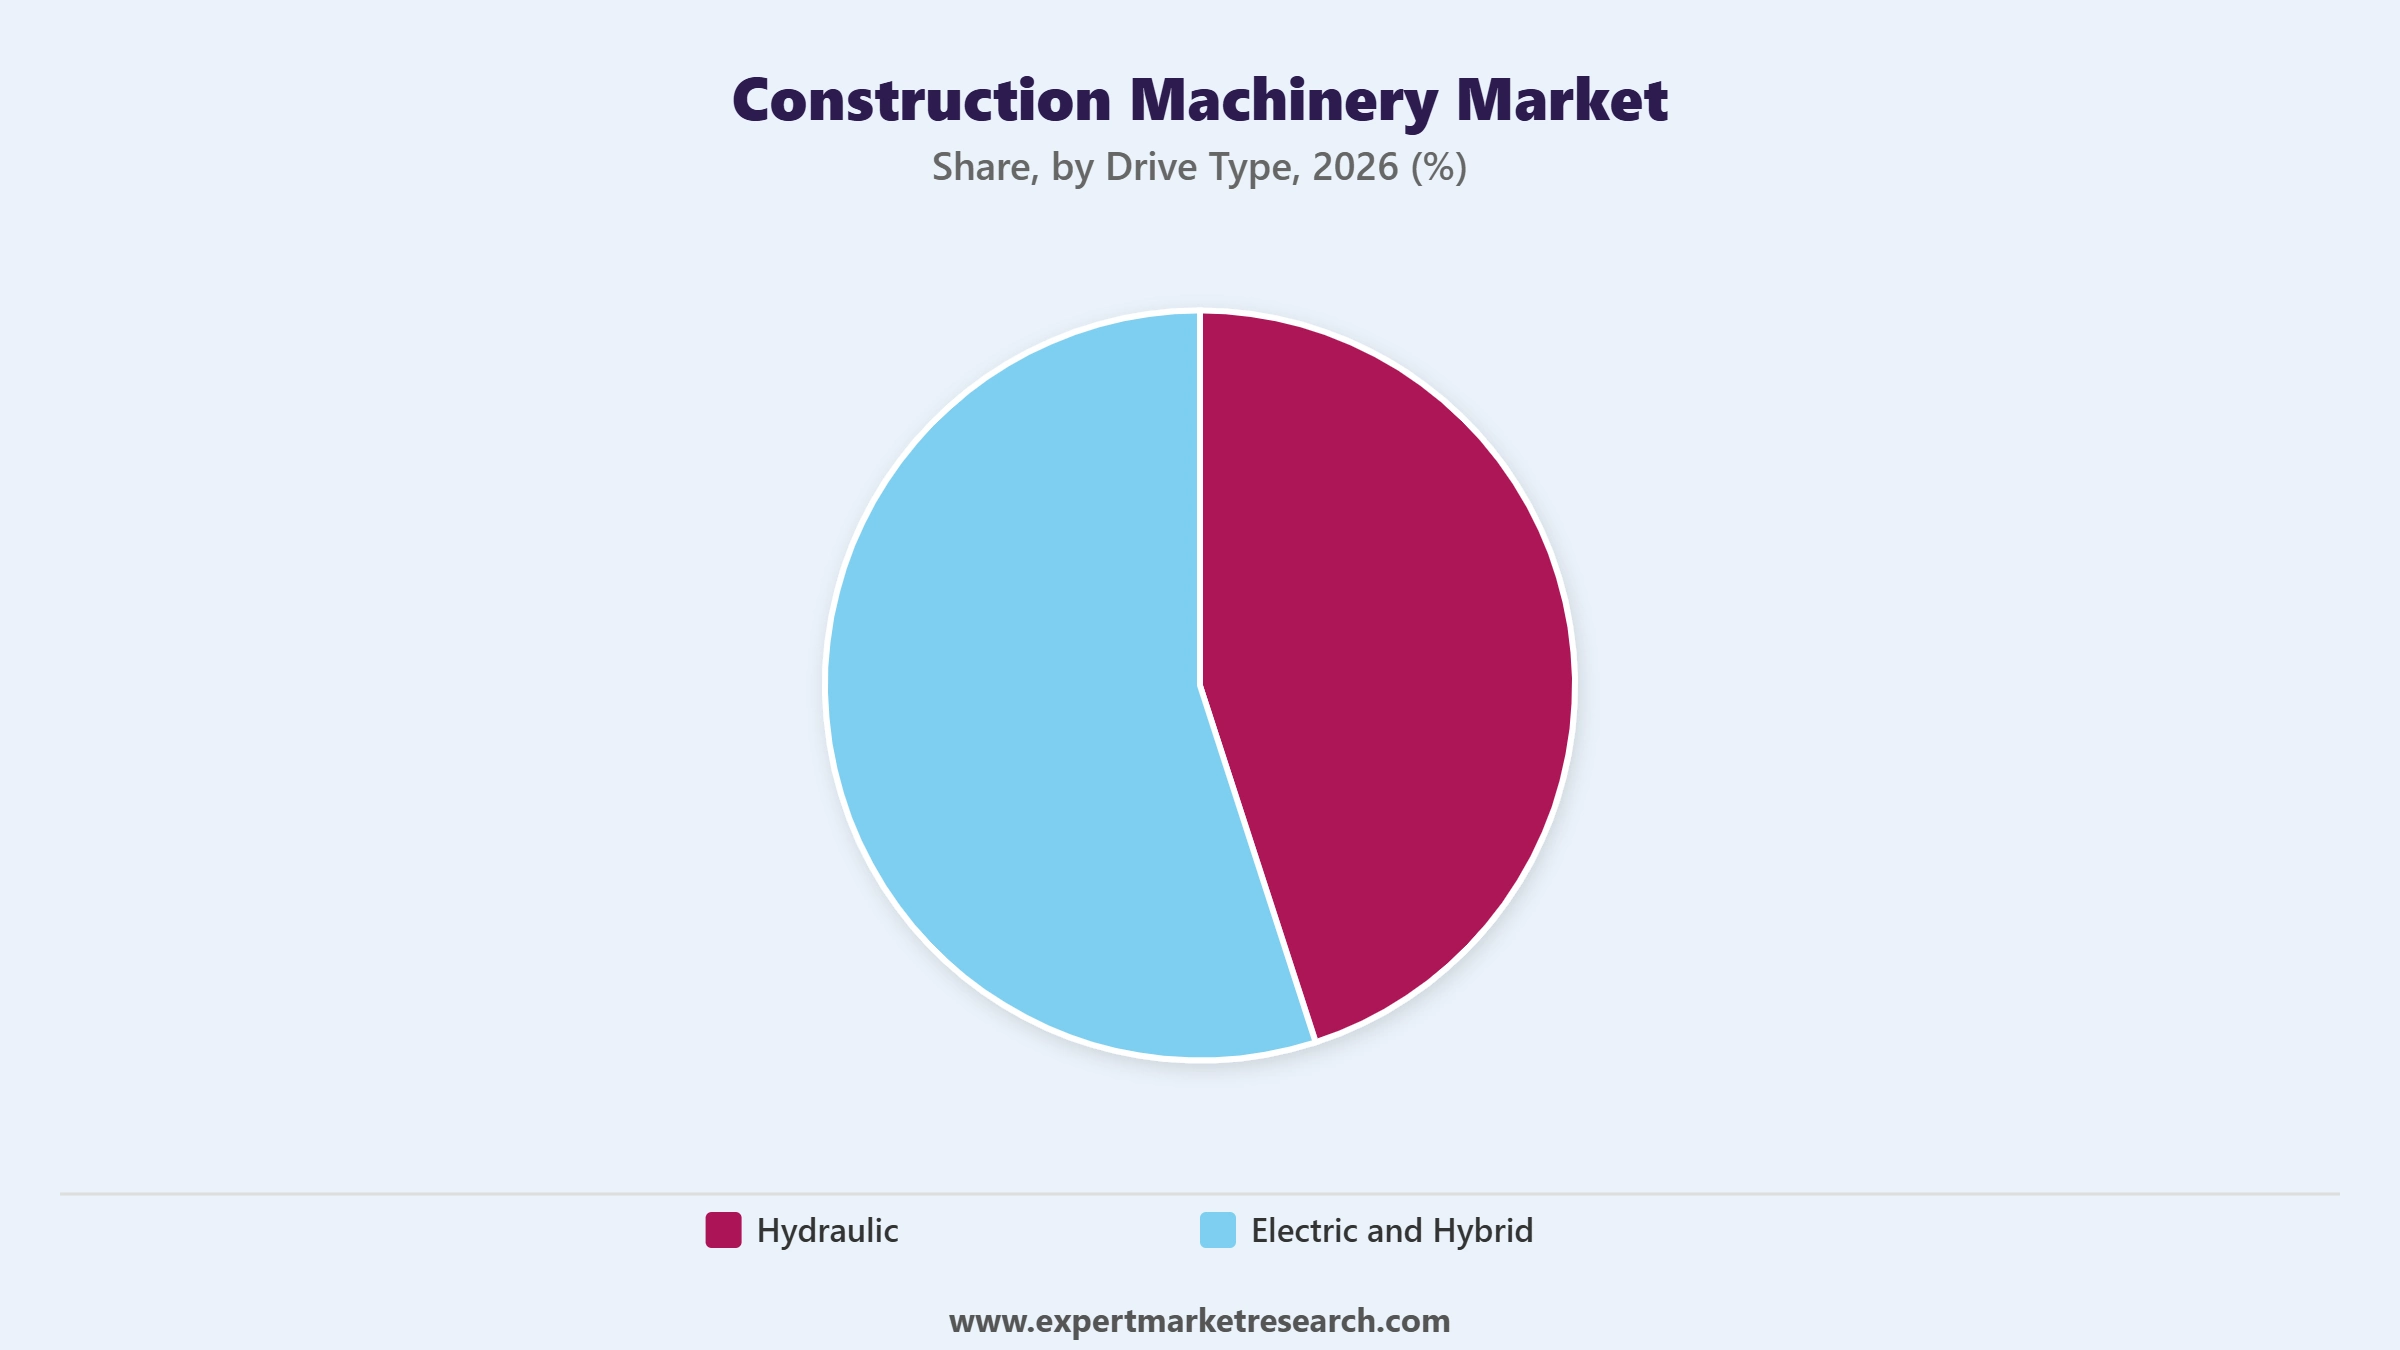
Market Breakup by Drive Type
Key Insight: Hydraulic is the leading drive type, with Hitachi Construction Machinery reporting in July 2026 that European demand for hydraulic excavators remained stable and that value-chain revenue from parts, maintenance, rentals, and used equipment rose 17.2% to 48% of total revenue in the three months ended June 2026; and Electric and Hybrid is the fastest-growing drive type, with XCMG Machinery's September 2026 interim report showing new energy product revenue up 25.82% to nearly RMB 10 billion.
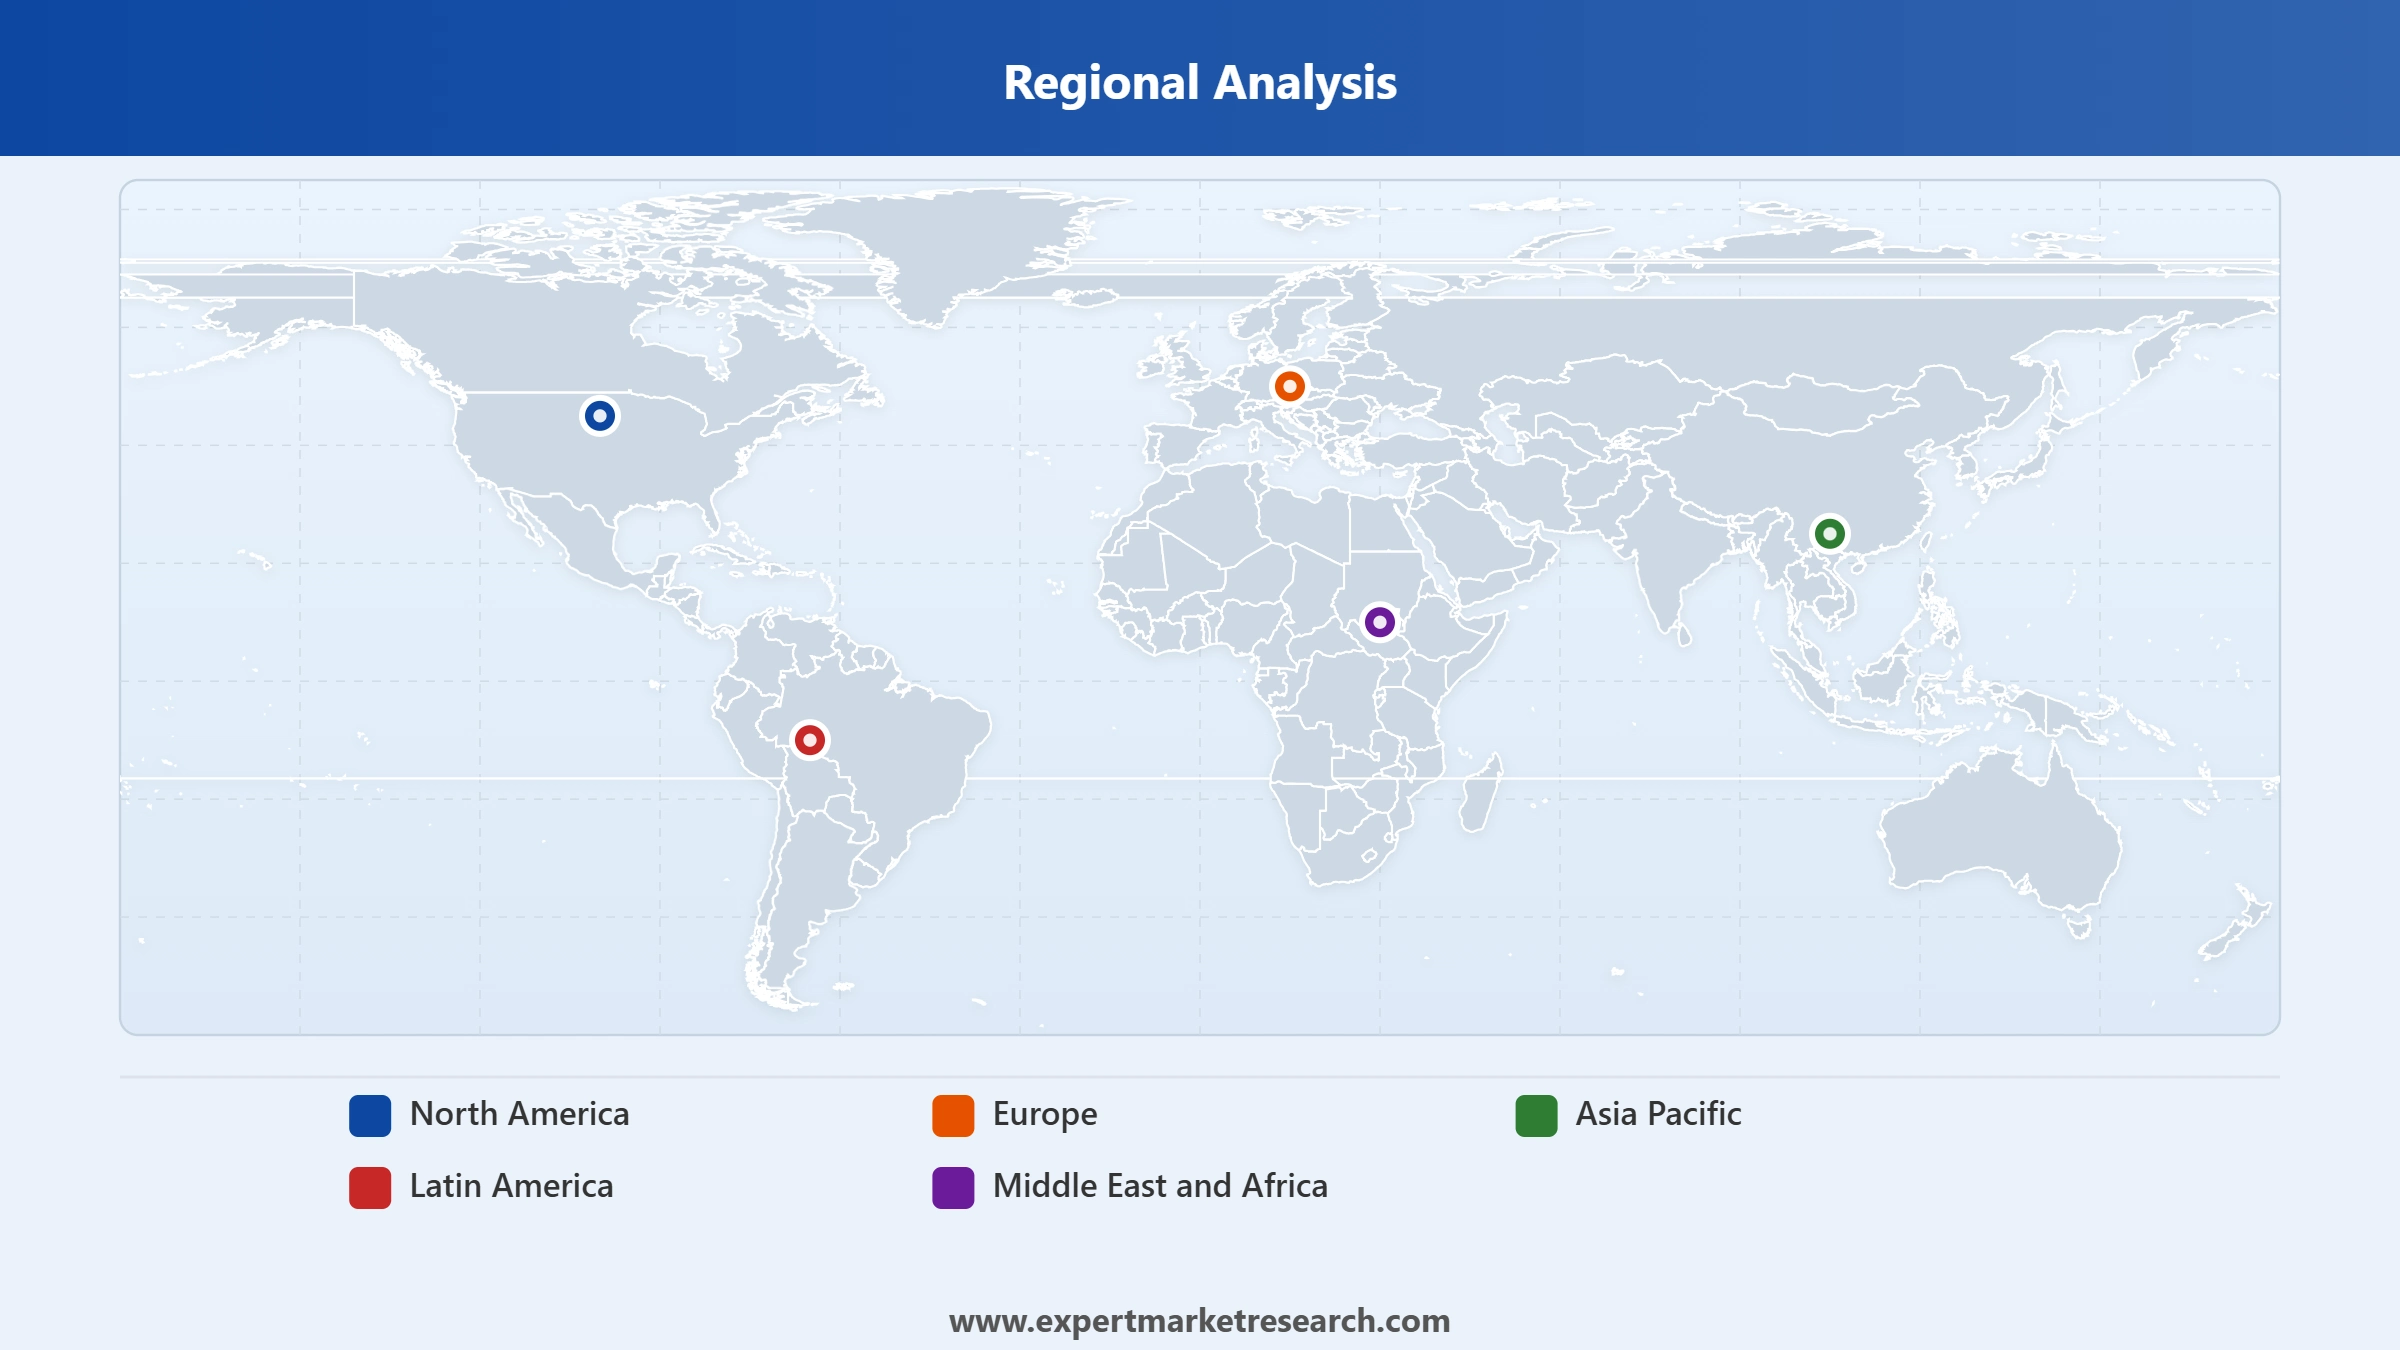
Market Breakup by Region
Key Insight: North America is a high-volume market, with Tadano reporting in August 2026 record net sales of JPY 182.6 billion for the six months ended June 2026, up 10.8%, as resilient North American demand supported results; Europe is a steady replacement market, with CECE, the European construction equipment committee, reporting in March 2026 that European sales rose 4.6% in 2025 and forecasting growth of 2% to 2.5% in 2026; Asia Pacific is the fastest-growing region, with the China Construction Machinery Association reporting in July 2026 that China's domestic excavator sales rose 20.4% to 79,025 units in the six months ended June 2026; Latin America is a recovering market, with Sobratema reporting in July 2026 that Brazilian yellow-line machine sales are expected to rise 4% to about 35,843 units in 2026; and Middle East and Africa is an emerging market, with Komatsu saying in July 2026 that Africa remained one of its strongest markets on gold-mining investment while Middle East sales were expected to be lower.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By Machinery Type, Excavator leads the market while Crane grows fastest because infrastructure and heavy-lift projects keep demand for large lifting equipment rising.
Excavator leads because the machine suits almost every earthmoving task, from trenching to quarry loading. Zoomlion reported in August 2026 that earthmoving, mining, aerial work platforms, and agricultural machinery together generated about RMB 12.5 billion in the six months ended June 2026, up roughly 10%, with earthmoving alone about 20% of revenue and the largest contributor to its international sales, which shows how strongly overseas customers are buying earthmoving machines. That pull matters for suppliers planning dealer coverage and parts.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Crane grows fastest as heavy-lift demand rises with energy and industrial projects. Manitowoc reported in August 2026 that orders for the three months ended June 2026 rose 56.1% to USD 708.7 million, lifting backlog to USD 1,050.1 million and raising its 2026 net sales outlook to USD 2.3 billion to USD 2.4 billion. Rising orders widen the project base open to large crane makers and give buyers more choice in heavy-lift capacity. Buyers value that breadth when scheduling large lifts.
By Drive Type, Hydraulic leads the market while Electric and Hybrid grows fastest because operators are adding lower-emission machines to meet site and fleet requirements.
Hydraulic leads because hydraulic circuits deliver the breakout force, precision, and durability that earthmoving work requires. ICEMA reported in May 2026 that earthmoving equipment accounted for 97,236 of the 136,995 construction equipment units sold in India in the year ended March 2026, about 71% of the market, the category in which hydraulic machines dominate, even as domestic demand softened, with public capital spending of INR 12.2 lakh crore planned for the year ending March 2027 expected to sustain earthmoving demand.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Electric and Hybrid grows fastest as fleets add zero-emission machines. Volvo Construction Equipment said in July 2026 that it had delivered the world's first serial-produced A30 Electric articulated haulers to the Norwegian customer LNS, a milestone showing electric drivelines moving from trials to series production, where lower noise and zero tailpipe emissions help contractors work in emission-restricted zones and meet customer emissions targets on both public and private projects. Suppliers that master battery packs and charging integration gain an edge.
Asia Pacific commands the largest regional share of the construction machinery market in 2025, shaped by rapid infrastructure development, urbanisation, and the manufacturing scale of China, India, and ASEAN.
This is supported by Sany Heavy Industry's September 2026 disclosure that revenue from Asia and Australia reached USD 1.98 billion in the six months ended June 2026, up 17.38% and the largest overseas region in its accounts, ahead of Europe at USD 1.02 billion and the Americas at USD 0.93 billion. The figure shows Chinese manufacturers growing outside their home market while the customer base across Southeast Asia, Australia, India, and the wider subcontinent keeps expanding.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Asia Pacific is also the fastest-growing regional market, with the China Construction Machinery Association reporting in July 2026 that China's excavator exports rose 33.5% to 73,295 units in the six months ended June 2026. Elsewhere, Hitachi Construction Machinery said in July 2026 that its Central and South America revenue more than doubled to USD 95.5 million in the three months ended June 2026 on mining activity, while North American revenue fell 7.4% to USD 413.2 million on lower sales to original equipment manufacturers.
The global construction machinery market is moderately consolidated at the top, with a handful of multinational manufacturers from the United States, Europe, Japan, and China holding large shares alongside many regional producers serving local contractors and rental fleets.
Competitive dynamics are increasingly shaped by electrification and hydrogen trials, expansion of overseas manufacturing and service networks, tariff management, and investment in digital and autonomous technologies, as manufacturers seek to protect margins while demand shifts between regions.
Headquartered in Irving, Texas, Caterpillar Inc. makes excavators, wheel loaders, backhoe loaders, motor graders, and other construction machinery. In August 2026, it reported adjusted profit per share of USD 8.17 for the three months ended June 2026, up from USD 4.72 a year earlier, on total sales and revenues of USD 20.54 billion, up 24%.
Deere and Company builds construction and forestry equipment, including excavators, alongside its agricultural machinery. In August 2026, its Construction and Forestry segment reported net sales of USD 3,618 million, up 18%, and operating profit of USD 436 million, a 12.1% margin, for the three months ended August 2026, as higher shipment volumes and favourable price realisation lifted results.
Manitou Group makes telehandlers and other handling equipment for construction, agriculture, and industry. In July 2026, it reported revenue of EUR 1,428 million for the six months ended June 2026, up 12%, and recurring operating income of EUR 87 million, a 6.1% margin, and raised its 2026 revenue growth outlook to between 6.5% and 8.0%.
J.C Bamford Excavators builds backhoe loaders and Loadall telehandlers, and describes itself as the world's number one backhoe loader manufacturer. In May 2026, it launched its first production 3CX Hydrogen backhoe loader, powered by a 55 kW hydrogen combustion engine and backed by more than GBP 100 million of investment in hydrogen engine technology over five years.
Other key players in the construction machinery market include CNH Industrial N.V., Zoomlion Heavy Industry Science and Technology Co., Ltd., and Hitachi Construction Machinery Co., Ltd., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
For a detailed assessment of opportunities across the construction machinery market's machinery type, drive type, and regional segments through 2026 and beyond, connect with Expert Market Research for a customized consultation.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
The construction machinery market is projected to grow at a CAGR of 8.90% from 2026 to 2035.
Key strategies include expanding overseas production and service networks, launching electric, hybrid, and hydrogen models, localising manufacturing to manage tariffs, and growing rental, parts, and digital services alongside new machine sales.
Rapid developments in the infrastructure sector is a key trend propelling the growth of the market.
The major regions in the market are North America, Latin America, the Middle East and Africa, Europe, and the Asia Pacific.
The leading machinery types in the global construction machinery market are crane, telescope handlers, excavator, loader and backhoe, and motor grader, among others.
The drive types in the market are hydraulic, electric, and hybrid.
Key players in the construction machinery market include CNH Industrial N.V., Deere and Company, Manitou Group, Zoomlion Heavy Industry Science and Technology Co., Ltd., Hitachi Construction Machinery Co., Ltd., J.C Bamford Excavators, and Caterpillar Inc., among others.
The global construction machinery market attained a value of USD 294.44 Billion in 2025.
Key challenges include tariff-driven cost pressure, uneven regional demand, volatile currencies, the cost and charging or fuelling infrastructure needed for electric and hydrogen machines, and the cyclical nature of construction and infrastructure spending.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Machinery Type |
|
| Breakup by Drive Type |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




