

Consumer Insights
Uncover trends and behaviors shaping consumer choices today
Procurement Insights
Optimize your sourcing strategy with key market data
Industry Stats
Stay ahead with the latest trends and market analysis.
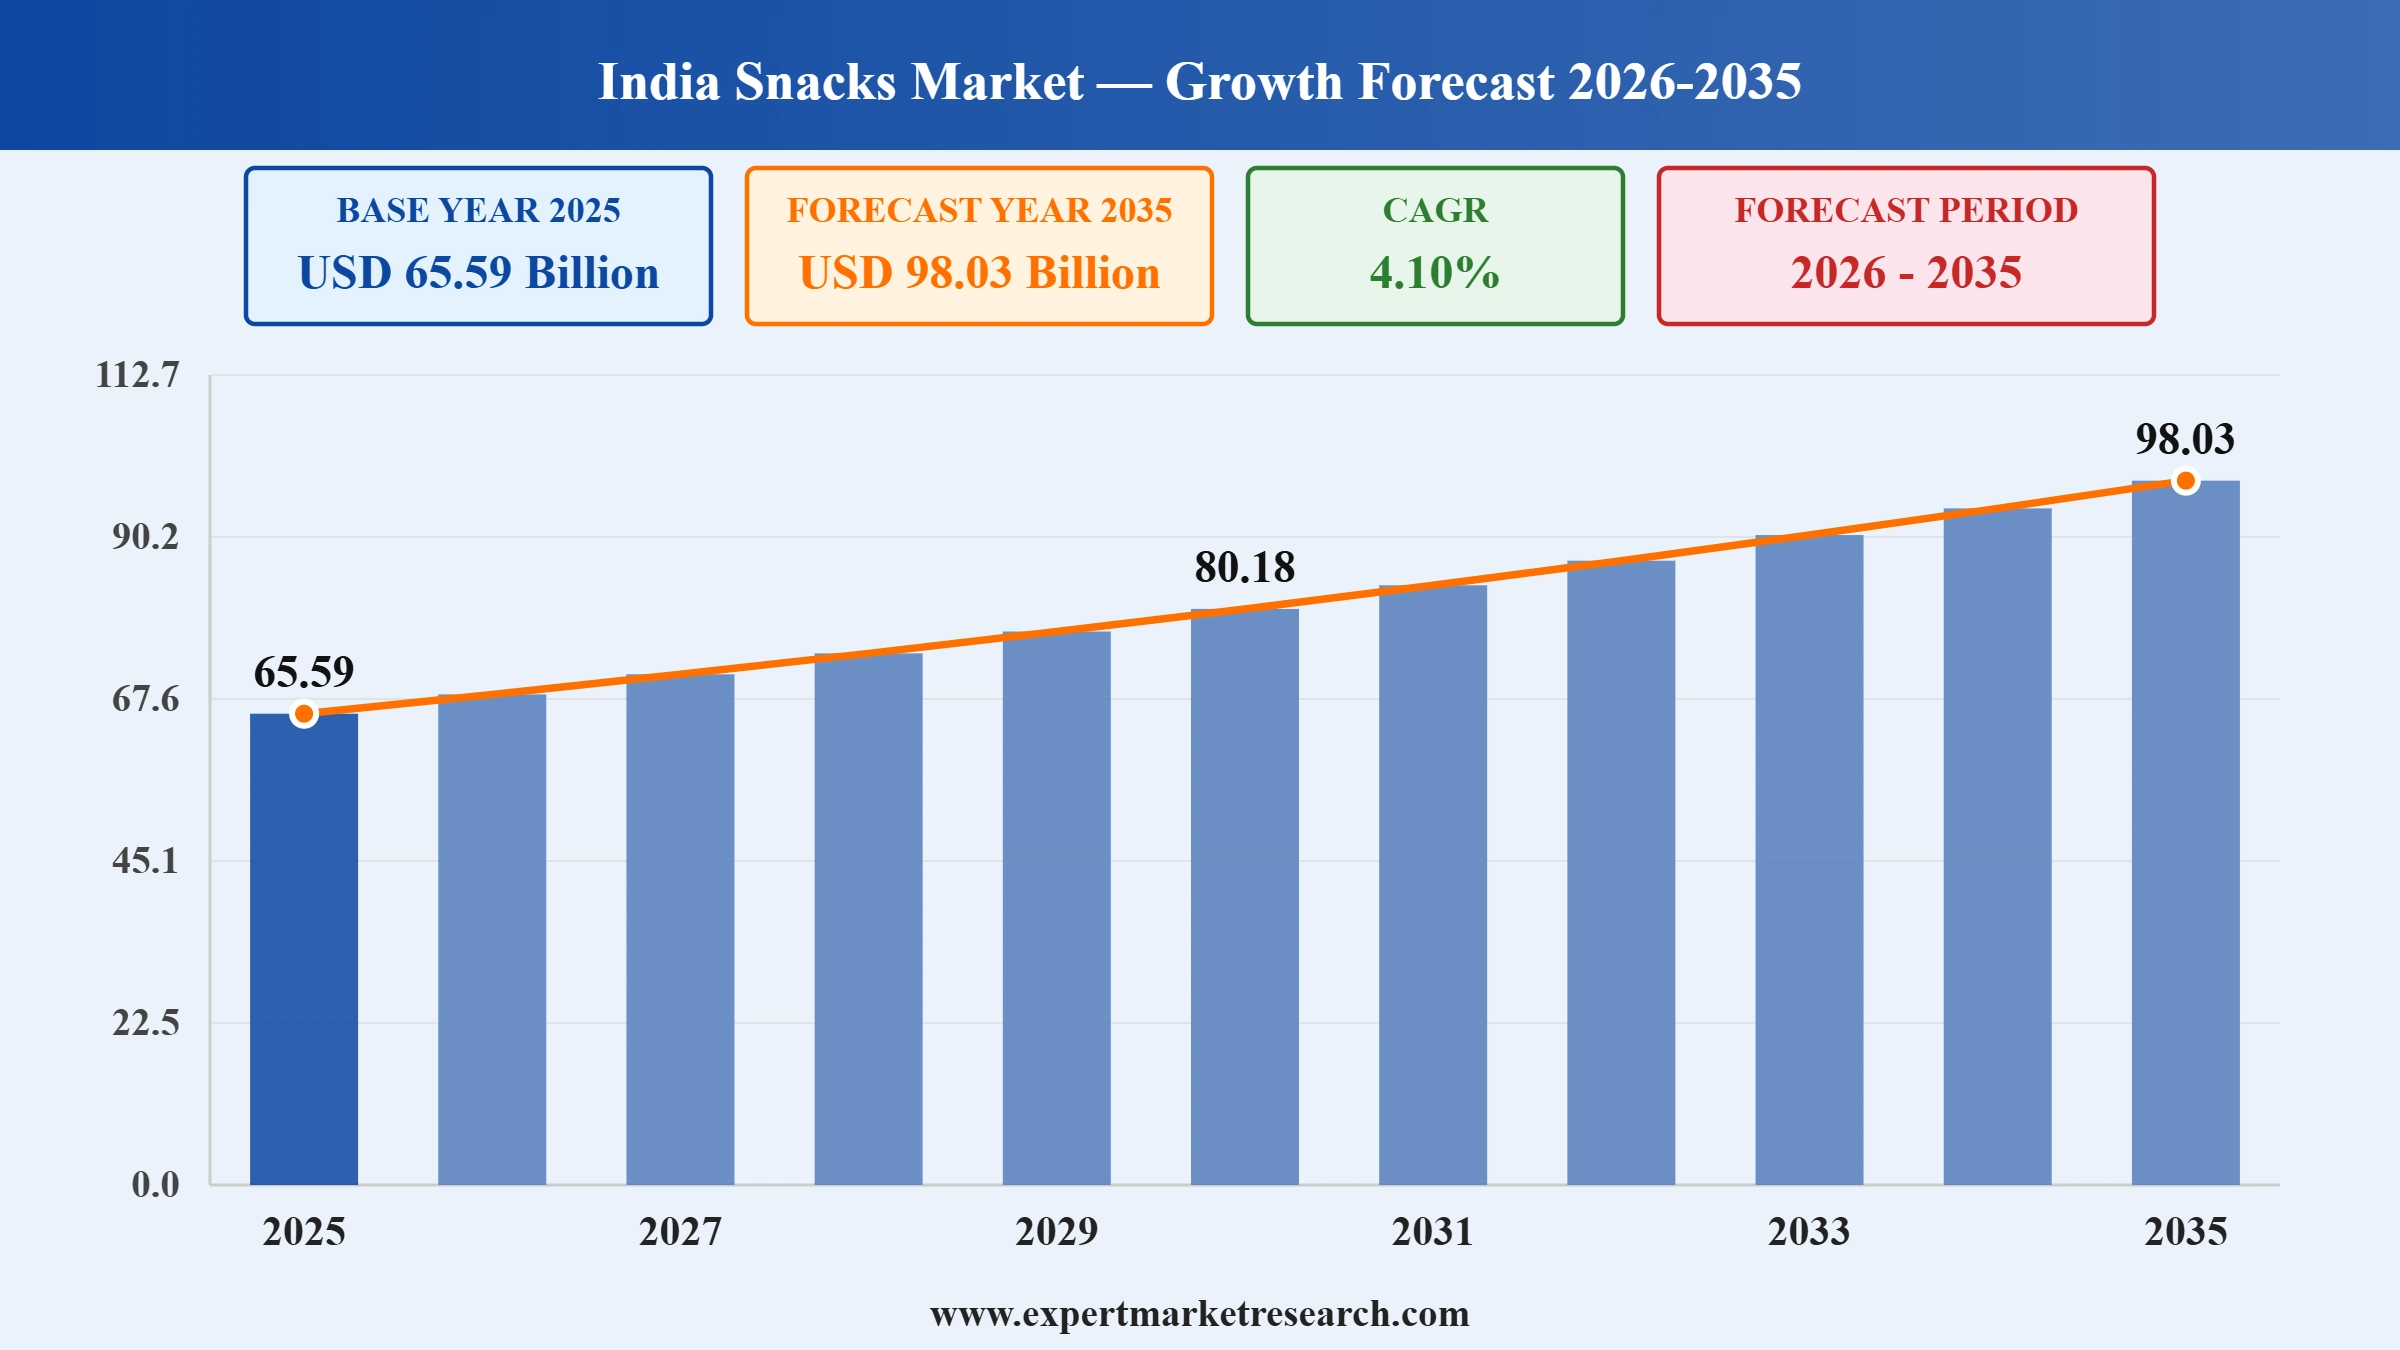
The India snacks market attained a value of USD 65.59 Billion in 2025 and is projected to expand at a CAGR of 4.10% through 2035. The market is further expected to achieve USD 98.03 Billion by 2035. Rising disposable incomes, rapid urbanisation, and a growing appetite for convenient, ready to eat products are lifting consumption across bakery, confectionery, frozen, and fruit categories, supported by expanding quick commerce platforms and new regional manufacturing capacity.
Packaged snacks span bakery, confectionery, frozen, and fruit-based products consumed as between meal food across households, offices, and social occasions across the India snacks market. The India savoury and confectionery market includes biscuits, chips, namkeen, chocolates, candies, frozen appetisers, and dried fruit-based bites sold through modern retail, general trade, and digital channels. Adoption is concentrated among urban and semi urban households, while rural penetration is gradually widening as distribution networks reach smaller towns. Rising incomes, smaller family sizes, and a preference for convenient food continue to support steady investment in new manufacturing capacity and product lines.
Demand in the India savoury and confectionery market is concentrating around indulgent confectionery formats as companies blend global dessert trends with recognisable domestic brands to capture premium spending occasions. Manufacturers are simultaneously widening distribution through quick commerce platforms that now account for a meaningful share of packaged food sales in major cities. In June 2026, Mondelez India launched a limited-edition Cadbury Dairy Milk Silk Dubai Chocolate combining a smooth chocolate shell with crispy kadayfi pastry and pistachio creme, priced at Rs 550 and sold through quick commerce platforms and select retail outlets.
Major India snacks market players are directing investment toward new manufacturing capacity, regional product lines, and flavour innovation that extend their reach across bakery, confectionery, and frozen categories. Companies are forming closer partnerships with modern retail and quick commerce platforms to secure faster, wider product availability. Firms are also widening portfolios into premium, healthier, and regionally inspired formats, positioning the industry to serve a broad base of urban and emerging rural customers through one expanding production and distribution base.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
| India Snacks Market Report Summary | Description | Value |
| Base Year | USD Billion | 2025 |
| Historical Period | USD Billion | 2019-2025 |
| Forecast Period | USD Billion | 2026-2035 |
| Market Size 2025 | USD Billion | 65.59 |
| Market Size 2035 | USD Billion | 98.03 |
| CAGR 2019-2025 | Percentage | XX% |
| CAGR 2026-2035 | Percentage | 4.10% |
| CAGR 2026-2035 - Market by Region | West India | 4.5% |
| CAGR 2026-2035 - Market by Region | North India | 4.3% |
| CAGR 2026-2035 - Market by Type | Fruit Snacks | 4.6% |
| CAGR 2026-2035 - Market by Distribution Channel | Online Channels | 7.0% |
| 2025 Market Share by Region | West India | 28.8% |
The new ready to eat snack pairs a crunchy churros format with an indulgent chocolate dipping sauce carrying a choco cinnamon flavour, sold through Blinkit, Zepto, and BigBasket across metropolitan cities. The launch extends the Bingo portfolio into dessert occasions beyond chips and namkeen. Snack makers across the India snacks market can use quick commerce exclusive launches to test new formats before wider retail rollout.
The foods arm of Emami Group entered the over Rs 50,000 crore packaged food category with potato chips, Jhuri Aloo Bhaja, and a chocolate hazelnut spread sold in Rs 10 packs, rolling out first in Kolkata. The company plans to invest Rs 750 crore, including a new West Bengal plant, to build the brand into a Rs 1,000 crore business.
The company posted revenue of Rs 1,723 crore, up 8 percent year on year, and net profit of Rs 129 crore, supported by stronger traction in food and nutrition categories including wider Pringles distribution and continued scaling of the Chocos brand. The turnaround reversed the prior decline in profitability. Food companies across the India snacks market can use focused investment to drive a faster recovery.
The dried fruit and nut brand secured funding led by L Catterton, with existing investors DSG Consumer Partners and BC Jindal Group also participating, after achieving around 55 percent annual revenue growth over two years. The capital will support expansion in flavoured makhana and date bites alongside entry into new markets. Food brands across the India snacks market can use growth capital to widen reach.
Confectionery makers across the India snacks market are steadily blending global dessert trends with recognisable domestic brands to capture premium spending occasions across retail and quick commerce channels every year. Parle Products is widening its confectionery portfolio with choco hazelnut and caramel inspired formats targeting consumers seeking indulgent treats. In June 2026, Parle Products Chief Marketing Officer Mayank Shah confirmed the national rollout of its new Parle Duet line across traditional and digital formats. Continued flavour experimentation is helping manufacturers defend consumption occasions nationwide.
Manufacturers across the India snacks market are steadily expanding production capacity for ready to eat and cook formats as urban households seek faster meal solutions every passing year. Nestle India is widening its Maggi noodles production base to meet sustained demand growth among time pressed consumers across the country. In July 2025, Nestle India confirmed a capital expenditure of Rs 105 crore for a new production line at its Sanand facility in Gujarat. Steady capacity investment is helping established players defend market share.
Private equity investors across the India snacks market are steadily reassessing branded snack holdings as strategic buyers and funds compete for scale in a rapidly consolidating category every passing year. Advent International is exploring a sale of its controlling stake in DFM Foods, the maker of the Crax corn ring brand, after six years of ownership. In July 2026, Advent confirmed strategic buyers and private equity firms including Kedaara Capital were evaluating the opportunity. Continued consolidation is reshaping ownership across branded snack manufacturing.
Frozen food companies across the India snacks market are steadily committing capital to new processing plants that strengthen farming networks and supply chains nationwide every passing year. McCain Foods is building a large food processing facility in Madhya Pradesh, engaging thousands of local potato growers through contract farming arrangements. In September 2025, McCain Foods confirmed an investment of Rs 4,000 crore, equivalent to USD 480 million, for the three-phase project. Expanding frozen appetiser capacity is positioning the state as a growing manufacturing hub.
Namkeen and sweets manufacturers are steadily attracting large institutional investment as investors seek exposure to branded Indian snacking categories every passing year. Haldiram Snacks is strengthening its balance sheet through new investor backing to support continued domestic and international expansion plans across retail. In March 2025, the namkeen major confirmed a fundraising round led by Temasek and Alpha Wave Global at a USD 10 billion valuation. Sustained investor confidence is reflecting long term growth expectations for branded snacking.
The Expert Market Research's report titled "India Snacks Market Report and Forecast 2026-2035" offers a detailed analysis of the market based on the following segments:
Market Breakup by Snacks Type
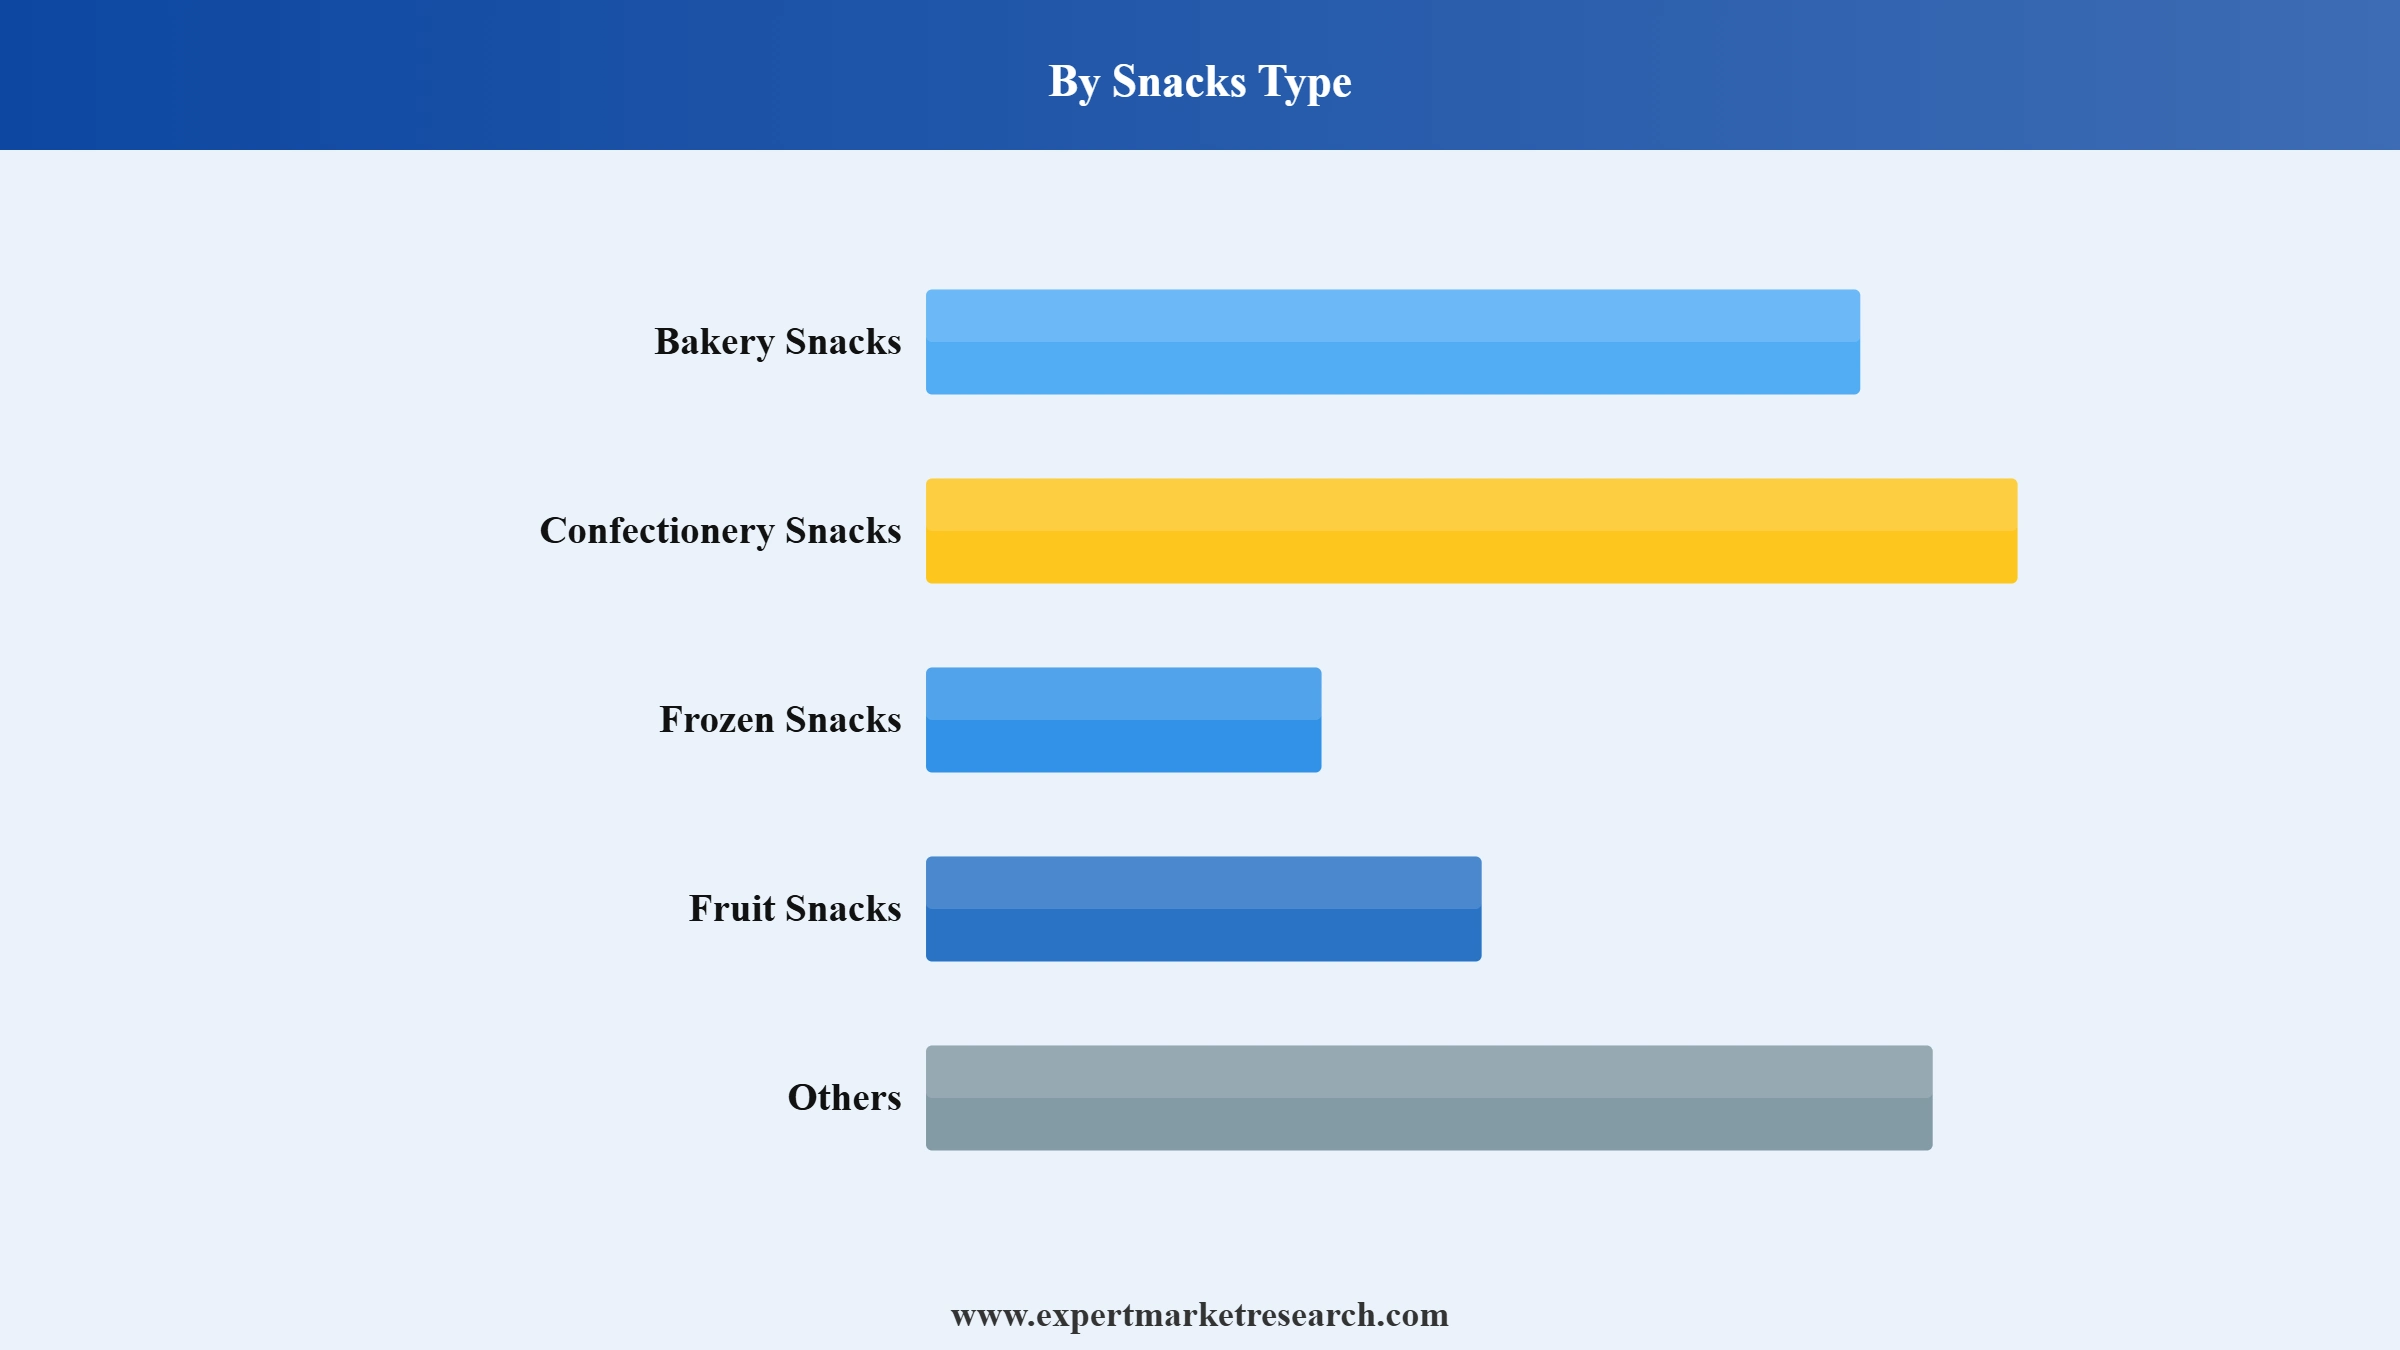
Key Insight: Bakery items account for the largest share of the India snacks market, supported by widespread biscuit consumption across urban and rural households and an established domestic manufacturing base. Confectionery is the fastest growing type as companies introduce indulgent chocolate and candy formats targeting younger consumers and premium gifting occasions. Frozen items are expanding steadily as cold chain infrastructure improves, and quick service restaurants widen demand for appetisers and ready to cook products. Fruit based bites, including dried fruit and makhana, are gaining traction among health-conscious consumers seeking lighter between meal options. Others cover extruded, namkeen, and savoury mixture formats sold widely through general trade and modern retail outlets. In January 2026, Balaji Wafers secured a strategic growth investment from General Atlantic to expand its manufacturing capacity and distribution reach across the country.
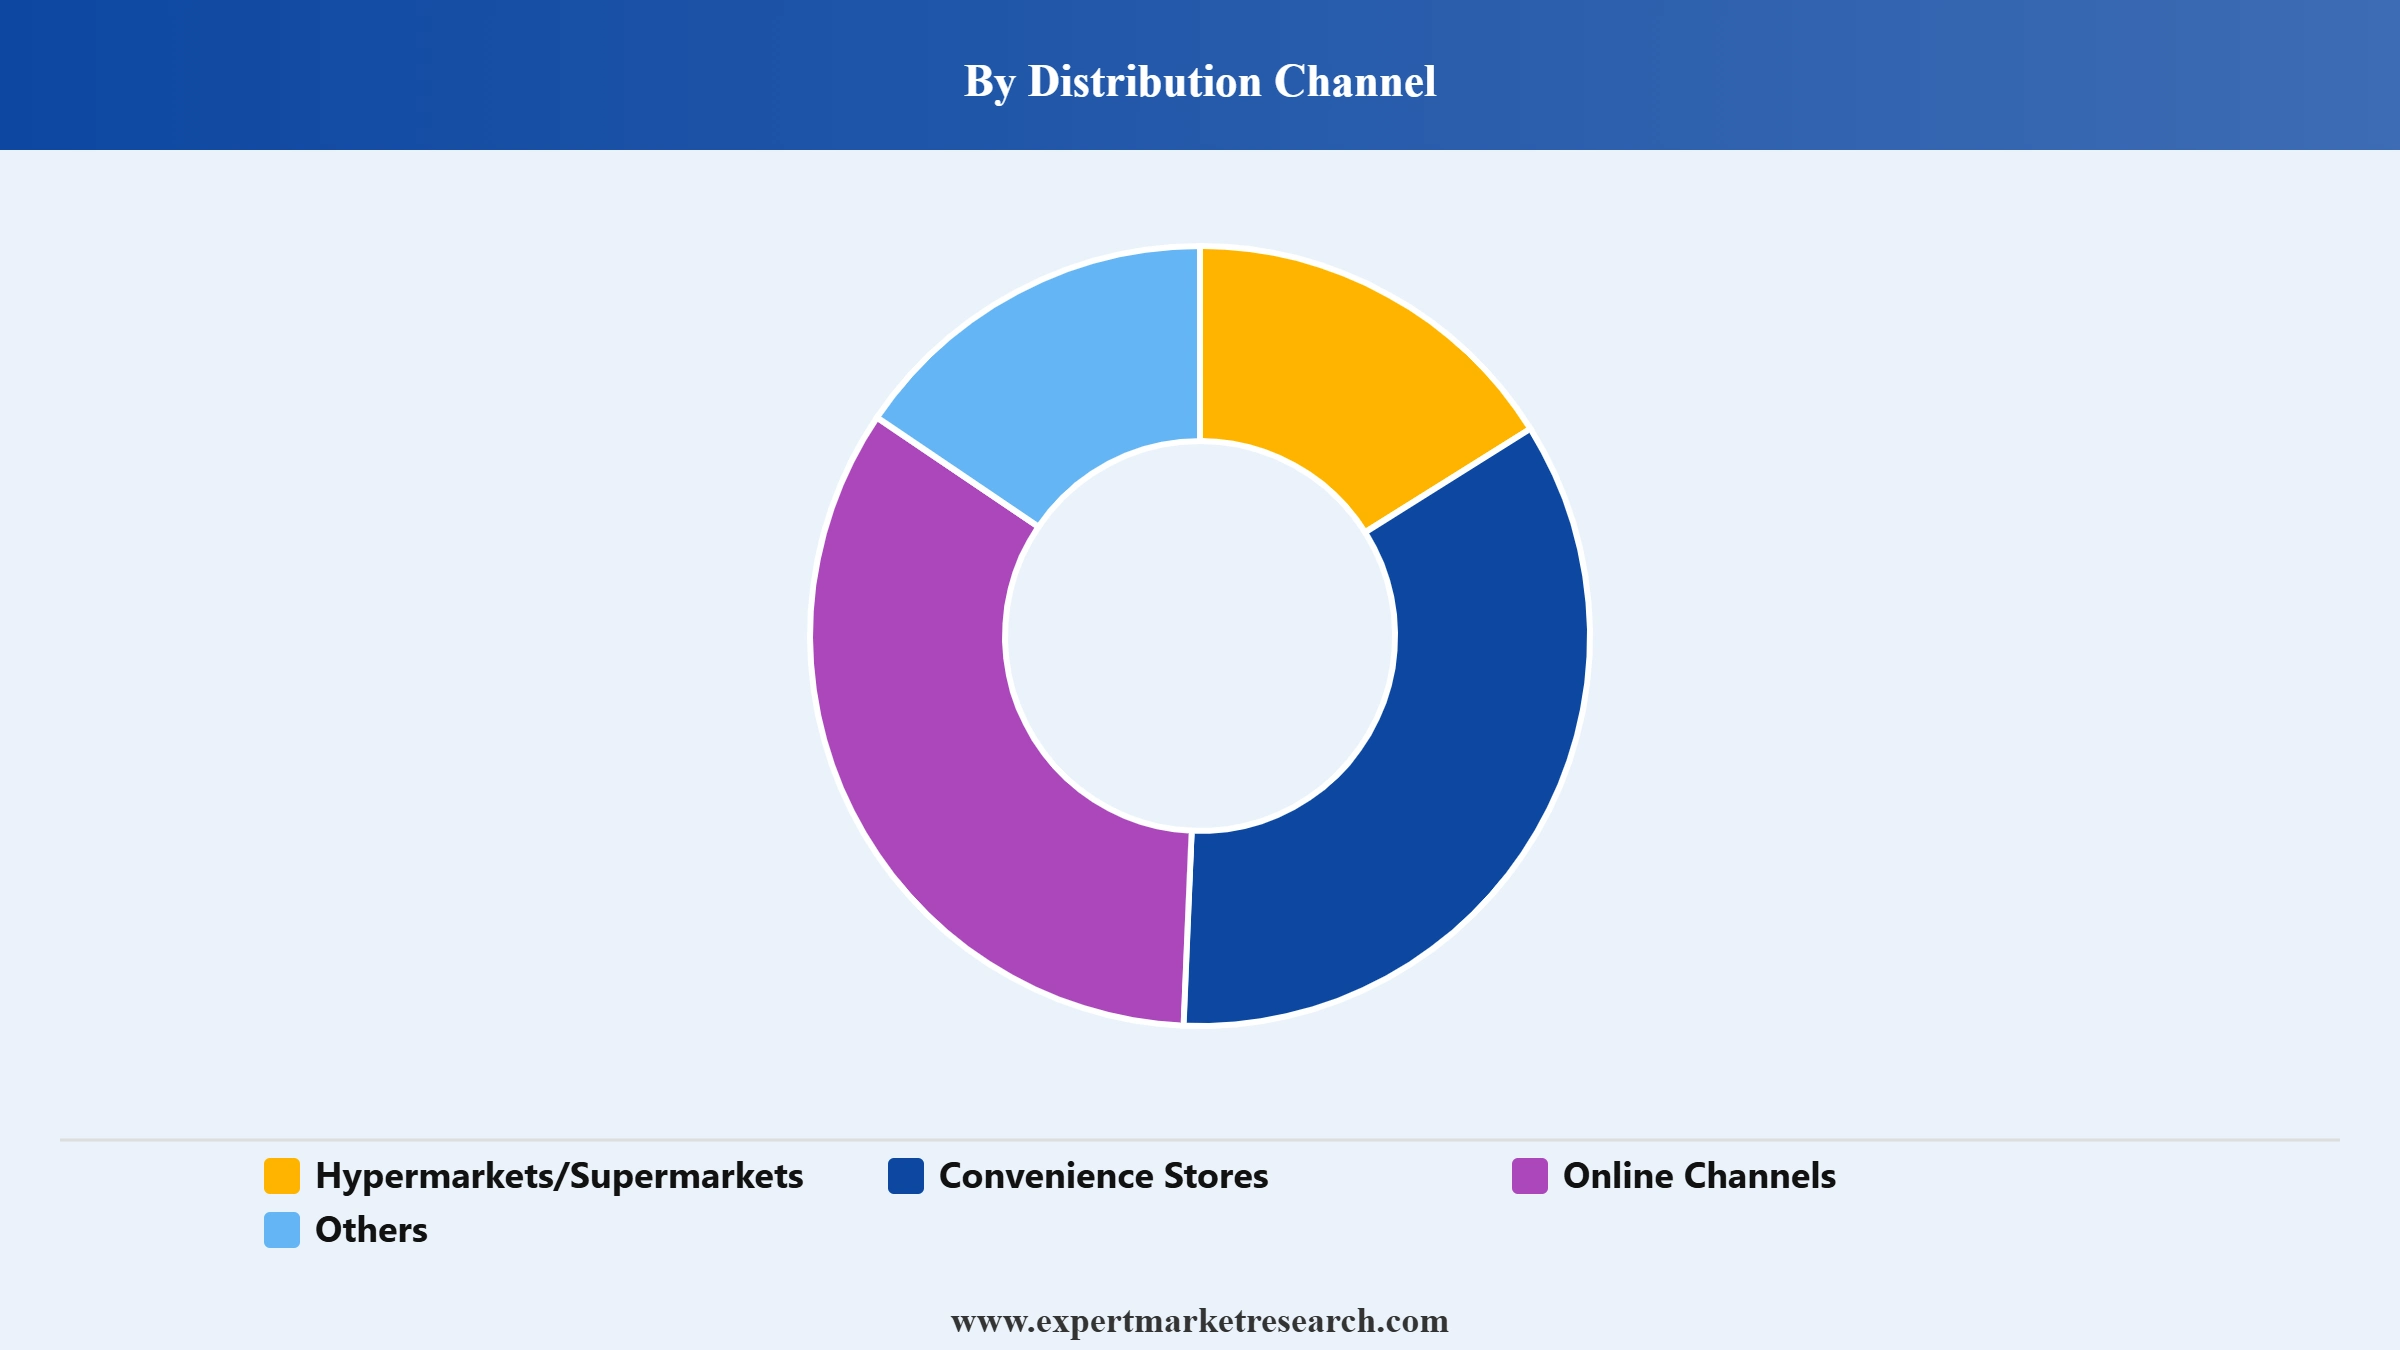
Market Breakup by Distribution Channel
Key Insight: Hypermarkets and supermarkets hold a substantial share of the India snacks market, offering shoppers wide assortment and in store promotions across packaged snack categories. Online channels are growing the fastest as quick commerce platforms shorten delivery times and widen access to packaged food in dense urban neighbourhoods. Convenience stores remain an important channel for impulse purchases of smaller snack packs near homes, offices, and transit points. Others include general trade kirana stores and institutional catering channels that continue to serve a wide base of price sensitive consumers across the country.
Market Breakup by Region
Key Insight: North India leads the India snacks market, anchored by a dense concentration of namkeen and biscuit manufacturing alongside a large urban consumer base across the National Capital Region and surrounding states. South India is registering the fastest regional growth as rising incomes and a strong café and quick service culture widen demand for packaged food and confectionery. East India is seeing new manufacturing investment as regional conglomerates enter the packaged food category to serve previously underserved markets. West and Central India benefit from an established food manufacturing base and strong modern retail and quick commerce penetration across major metropolitan centres.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
By snacks type, bakery snacks dominate the market owing to an established domestic biscuit manufacturing base
Bakery snacks account for the largest share of the India snacks market because established manufacturers operate dense distribution networks reaching rural households. Continued investment in new product lines is helping bakery companies defend consumption occasions against emerging confectionery alternatives. In the quarter ended June 2026, Britannia Industries reported consolidated net profit up 14 percent year on year to Rs 593 crore, with revenue rising 9.5 percent to Rs 4,964 crore on volume growth and e commerce momentum.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Confectionery snacks are growing at the fastest pace in the India savoury and confectionery market as companies steadily introduce globally inspired chocolate and candy formats to capture premium spending among younger, urban consumers across the whole country. Leading players are steadily widening flavour portfolios to sustain repeat purchases during festive and gifting seasons each year. In March 2025, Mars Wrigley India launched a Snickers Peanut Brownie variant, combining classic caramel, peanut, and chocolate elements with a brownie inspired format.
By distribution channel, hypermarkets and supermarkets lead the market owing to wide assortment and promotional reach
Hypermarkets and supermarkets hold the largest share of the India snacks market, giving shoppers access to wide product assortment, seasonal promotions, and private label alternatives across packaged food categories. Large retail groups are steadily expanding store networks and automation to strengthen cost leadership in food retailing. In August 2025, Reliance Retail announced plans to invest Rs 40,000 crore to build integrated food parks with automation and robotics, targeting a 20 percent compound annual growth rate in retail revenue.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
Online channels are expanding at the fastest pace in the India savoury and confectionery market as quick commerce platforms shorten delivery windows and widen packaged food availability across dense urban neighbourhoods. Leading food companies are steadily adjusting pack sizes and assortments to suit rapid delivery formats. In June 2025, Nestle India's managing director noted that quick commerce already accounted for 60 percent of the company's online sales, reflecting rapid category penetration led by platforms including Blinkit, Zepto, and Swiggy Instamart.
North India leads the market through its dense namkeen and biscuit manufacturing base
North India holds the largest share of the India snacks market, anchored by a dense concentration of namkeen and biscuit manufacturing clusters serving the National Capital Region and surrounding states with established distribution reach. Regional manufacturers headquartered in Rajasthan and neighbouring states continue to widen their product portfolios into new categories. In the quarter ended December 2025, Bikaji Foods reported a 122 percent surge in profit after tax alongside a strategic expansion into frozen and bakery product segments.
Read more about this report - REQUEST FREE SAMPLE COPY IN PDF
South India is registering the fastest regional growth in the India snacks market as rising incomes and a strong café culture widen demand for packaged food and confectionery among younger consumers across the region. Regional snack brands based in Tamil Nadu and neighbouring states are scaling rapidly through digital first distribution models. In February 2026, Chennai based Sweet Karam Coffee reported FY25 revenue of Rs 46 crore, up 307 percent year on year, driven by regional snack demand.
The industry is becoming more innovation driven as major packaged India snacks companies invest in new flavour variants, premium formats, and expanded manufacturing capacity to meet changing consumer preferences. Suppliers are prioritising faster product development cycles and wider quick commerce distribution to stand out in a field where shelf space and digital visibility are key commercial pressures. A strategic focus on regional manufacturing and flavour localisation is helping firms strengthen market share, while partnerships with modern retail and quick commerce platforms are widening consumer reach.
Leading India snacks market players are also working on healthier formulations, dried fruit and nut-based alternatives, and direct to consumer channels to widen their addressable categories. Opportunities are emerging in premium confectionery, frozen appetisers, and online first product lines as consumer preferences shift. Firms that combine strong distribution networks, dependable manufacturing scale, and established brand recognition are expected to strengthen their competitive position through the forecast period, supported by sustained investment in capacity and innovation.
Founded in 1910 and headquartered in Kolkata, West Bengal, India, the company manufactures packaged food products including the Bingo brand of savoury snacks distributed through retail and quick commerce platforms. It operates manufacturing facilities across several Indian states.
Founded in 1892 and headquartered in Kolkata, West Bengal, India, the company manufactures biscuits, bread, and dairy based food products distributed through retail and e commerce channels. It operates multiple manufacturing plants supporting its position as a leading domestic bakery company.
Founded in 1937 and headquartered in New Delhi, India, the company manufactures namkeen, sweets, and packaged snack products distributed across India and international markets. It operates an extensive manufacturing and retail network supporting its position as a leading domestic snacks brand.
Founded in 1929 and headquartered in Mumbai, Maharashtra, India, the company manufactures biscuits, confectionery, and snack products including the Parle G and Parle Chatkeens brands distributed. It operates an extensive network of manufacturing and distribution facilities across the country.
Other key players in the market include Pepsico Inc., Mondelez International Inc., Kellanova, Nestle S.A., Lotte Corporation, Mars Incorporated Inc., among others.
*Please note that this is only a partial list; the complete list of key players is available in the full report. Additionally, the list of key players can be customized to better suit your needs.*
Unlock the latest insights with our India snacks market trends 2026 report. Discover regional growth patterns, segment preferences, and key industry players. Stay ahead of competition with trusted data and expert analysis. Download your free sample report today and drive informed decisions in the market.


Upto 15% Off
USD
$2499 $2249
$3999 $3599
$4999 $4249
$5999 $5099


*While we strive to always give you current and accurate information, the numbers depicted on the website are indicative and may differ from the actual numbers in the main report. At Expert Market Research, we aim to bring you the latest insights and trends in the market. Using our analyses and forecasts, stakeholders can understand the market dynamics, navigate challenges, and capitalize on opportunities to make data-driven strategic decisions.*
In 2025, the market reached an approximate value of USD 65.59 Billion.
The market is projected to grow at a CAGR of 4.10% between 2026 and 2035.
The market is estimated to witness healthy growth in the forecast period of 2026-2035 to reach a value of around USD 98.03 Billion by 2035.
Key trends aiding the market expansion are introduction of low sugared snacks, increasing demand for baked snacks, and overall rising consumption of various snacks across India.
The different types of snacks in the market are bakery snacks, confectionery snacks, frozen snacks, and fruit snacks, among others.
The different distribution channels in the market are hypermarkets/supermarkets, convenience stores, and online channels, among others.
The key players in the market include Pepsico Inc., Mondelez International Inc., Kellanova, Parle Products Pvt. Ltd., Nestle S.A., ITC Limited, Lotte Corporation, Haldiram's India Pvt Ltd., Britannia Industries Limited, and Mars Incorporated Inc., among others.
The regional markets for the used cars include East India, West and Central India, North India, and South India.
North India leads the market, supported by its dense namkeen and biscuit manufacturing base.
Bakery snacks hold the largest category share, supported by sustained daily consumption across Indian households.
Companies face intense competition from new entrants, rising input and packaging costs, the need for continued flavour innovation, and growing pressure to widen quick commerce and digital distribution.
Expanding manufacturing capacity, launching new flavour and format variants, securing growth capital, widening quick commerce partnerships, and strengthening regional brand presence.
Explore our key highlights of the report and gain a concise overview of key findings, trends, and actionable insights that will empower your strategic decisions.
| REPORT FEATURES | DETAILS |
| Base Year | 2025 |
| Historical Period | 2019-2025 |
| Forecast Period | 2026-2035 |
| Scope of the Report |
Historical and Forecast Trends, Industry Drivers and Constraints, Historical and Forecast Market Analysis by Segment:
|
| Breakup by Snacks Type |
|
| Breakup by Distribution Channel |
|
| Breakup by Region |
|
| Market Dynamics |
|
| Competitive Landscape |
|
| Companies Covered |
|
Datasheet
One User
USD 2,499
USD 2,249
tax inclusive*
Single User License
One User
USD 3,999
USD 3,599
tax inclusive*
Five User License
Five User
USD 4,999
USD 4,249
tax inclusive*
Corporate License
Unlimited Users
USD 5,999
USD 5,099
tax inclusive*
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Small Business Bundle
Growth Bundle
Enterprise Bundle
*Please note that the prices mentioned below are starting prices for each bundle type. Kindly contact our team for further details.*
Flash Bundle
Number of Reports: 3
20%
tax inclusive*
Small Business Bundle
Number of Reports: 5
25%
tax inclusive*
Growth Bundle
Number of Reports: 8
30%
tax inclusive*
Enterprise Bundle
Number of Reports: 10
35%
tax inclusive*
How To Order

Select License Type
Choose the right license for your needs and access rights.

Click on ‘Buy Now’
Add the report to your cart with one click and proceed to register.

Select Mode of Payment
Choose a payment option for a secure checkout. You will be redirected accordingly.
Strategic Solutions for Informed Decision-Making
Gain insights to stay ahead and seize opportunities.

Get insights & trends for a competitive edge.

Track prices with detailed trend reports.

Analyse trade data for supply chain insights.

Leverage cost reports for smart savings

Enhance supply chain with partnerships.

Connect For More Information
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
Our expert team of analysts will offer full support and resolve any queries regarding the report, before and after the purchase.
We employ meticulous research methods, blending advanced analytics and expert insights to deliver accurate, actionable industry intelligence, staying ahead of competitors.
Our skilled analysts offer unparalleled competitive advantage with detailed insights on current and emerging markets, ensuring your strategic edge.
We offer an in-depth yet simplified presentation of industry insights and analysis to meet your specific requirements effectively.




